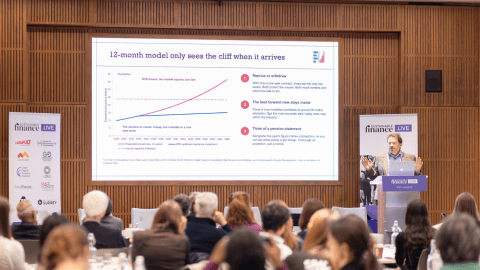
In the afternoon panel session at Finextra’s Sustainable Finance Live conference 2026, ‘From Field to Estate to Thriving Community’, speakers highlighted how community banking can empower local food vendors and fight food poverty.
Bumjoo Maclennan, co-lead of the Food Project, London Doughnut Economy Coalition, moderated the panel featuring speakers: Tom Chance, chief executive of Community Land Trust Network; Ben Makowiecki, agriculture sustainability director at Lloyds Banking Group; and Dominic Watters, founder of Food is Care.
Maclennan kicked off the session with the announcement of the England’s first organic action plan that was announced last week, which outlines a strategy for sector growth and to boost demand and production for organic food.
Lloyds' Makowiecki expressed scepticism on the plan, saying that while it is encouraging, there cannot be too much reliance on the public sector to step in and save the day, and the consumers need to be better informed to ensure that there is demand for the organic food.
Makowiecki detailed that 3% of Lloyds’ lending book is agriculture, and agriculture also makes up over a third of their finance emissions. He said that the bank is working in making farmers more resilient and regenerative, and as 70% of the UK is farmland, it is essential to support their growth.
He added: “Those farmers are really important in terms of changing perhaps the way they farm, helping them help nature. Improve habitats, improve water quality, water holding, and continue to feed the nation, I think that's really important thing. Perhaps is being missed out a bit today. They've got to work hand-in-hand. It can't be food or nature. It can't be land-sparing, it's got to be land-sharing. We need to help farmers continue to produce food, but in a much more nature-friendly, sustainable, regenerative way.”
Chance introduced the Community Land Trust Network and stressed that access to land is not equal. He explained that land access is dependent on very niche forms of finance and crowdfunding which is not easy to replicate to those facing class and race barriers.
He explained the challenge: “It feels that so much of the philanthropy world around this is interested in funding and demonstrator projects that kind of 'let's go and show portal and shine a light on it, show the model that someone should do it', but not attending to the systemic barriers. That means that no one else can copy it, and there's such a gulf between then the world of what community enterprises are trying to do with food and what Ben is describing, and it ought to be the case but there isn't. That we ought to be able to have consortia, intermediaries, market infrastructure to enable us to access for communities to be plugged into that, for lawyers to be supporting that kind of community-focused food enterprise, and if you look in other countries with much greater scale of cooperative economy, they have this kind of infrastructure.”
Chance added that he is looking to find a way to bring people together in financing and building this community at a greater scale to improve access to land.
Watters provided firsthand perspective of living in a council estate that was had scarcity of raw ingredients and nutrional foods, and said there needs to be more voices from people who have the lived experience to bring to light the reality of the problem and contribute to the solution. He highlighted that the food system does not serve his community, and often the groups and charities that look to support his community do not contain voices from those who have experienced food insecurity. Voices from those communities would help make that change sustainable.
“A lot of conversations are still controlled by voices that maybe haven't raised their child on free school meals. That maybe haven't lived in in a food insecure environment,” Watters said.
Food is Care, Watters explained, tries to reimagine what food insecurity is. “Food security is national security, and I agree. But then, why aren't the people experiencing food insecurity of national importance?”
Watters pointed out that there is a gap between the farmers and their product - that he has spoken to farmers with a deep connection and the passion have for the quality and nutrition for the produce they grow, who are at a loss to why their produce does not reach communities such as his.
Makowiecki highlighted that the “common denominator is unfairness in the food supply chain, and it's unfairness at your end as the consumer in your estate, and it's the farmer's end”. He pointed out that farmers are getting the same cut of their produce despite rises costs and increasing economic uncertainty.
The panel concluded that there needs to be collaboration across legal, governmental, financial structures to power our local community and food systems.
Anthony Hobley, founder, The Rosetta Initiative, delivered the final keynote of the day and emphasised how the struggle to mobilise climate finance persists due to missing signals across the financial system despite the plethora of risk data that exists from drones, satellites and probes.
“There are hundreds of companies springing up to produce this type of data and input, which is fantastic. But why then are you struggling to mobilise that finance? Why are the vast majority of investment decisions made by CFOs, asset managers, investment committee members as if that data doesn’t exist, and climate change is not happening? What is missing between the data and investment decisions? My view is we have a translation gap, and we need to look at the translation layer that translates that data into the right financial signals in the language that financial markets already use.”
Showcasing this translation gap in the insurance industry, Hobley used the example of the small UK town Tenbury Wells being refused flooding insurance by Zurich Municipal Insurance because of the volume of historic claims and the likelihood of future floods. He said that the insurer had “no feeling that they had any duty to work with their clients and help them understand the risks that were growing year on year to maintain their insurability.”
Taking this further, Hobley explored how there is a mismatch between how long-term climate risks develop and how short-term insurance decisions are made. Insurers may assess whether a property is safe to insure today without adequately considering whether it will remain insurable over the next 10, 15, or 20 years. Despite climate risk becoming prevalent in other areas of financial services, this is not considered within insurance at present.
Hobley made the case for forward-looking climate-risk modelling and how the financial industry already uses forward cost curves for commodities such as oil, gas, electricity, and coffee to support long-term investment decisions. If similar projections were available for climate-related insurance risks, investors and governments could see how losses and costs might develop over time.
He said: “The holy grail in climate finance [...] is to find what the investment case is, how do we build the investment case for adaptation or resilience? Well, this is how you do it. No curve, no investment case.” According to Hobley, the insurance industry faces a choice: to continue as is because it’s too difficult to change or risk becoming the villain.
Addressing climate risk requires a shift from short-term insurance pricing towards a more forward-looking approach that helps customers understand and manage their future exposure.
Analytical capabilities that provide longer term risk projections and practical advice on maintaining insurability could help unlock investment in climate resilience while protecting customer relationships. The choice financial decision makers have is between business as usual or taking a more proactive role in helping communities prepare for the risks ahead.