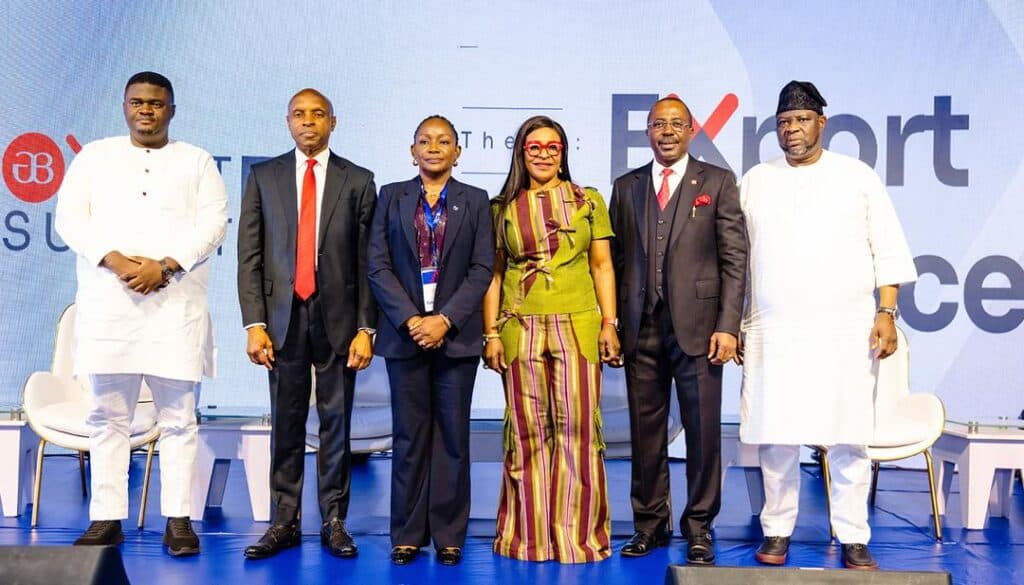
Globus Bank has called for increased export financing and local manufacturing to boost Nigeria’s non-oil exports, as stakeholders seek to address limited value addition, weak supply chains and infrastructure gaps hindering the country’s competitiveness in international markets.
Speaking at the Globus Bank Export Summit 2026 in Lagos, Elias Igbinakenzua, managing director and chief executive officer of the bank, said Nigeria had significant export opportunities but needed a more competitive, productive and reliable export ecosystem to realise its potential.
“Non-oil exports increased from $3.45 billion in 2021 to $6.1 billion in 2025, reflecting growth in the sector, but warned that the country continued to lose potential earnings because most commodities were exported with limited processing,” he said.
According to figures presented at the summit, raw shipments outnumber processed derivatives by about 10 to one. Cocoa exports, valued at about $2 billion, had only around 10 percent value addition, while cashew exports of $760 million included just $50 million worth of processed products.
Similarly, exports of gold, lead and zinc valued at $340 million had only $40 million processed, while ginger, hibiscus and spices generated between $130 million and $180 million in exports, with processed products accounting for just $10 million.
Igbinakenzua said the country needed to strengthen its capacity to process these commodities locally rather than depend on exporting raw materials.
He identified unreliable supply chains, limited access to finance, inadequate infrastructure, weak corporate governance, inconsistent policies and insufficient market intelligence as major constraints facing exporters.
He called for incentives to encourage local processing, accredited testing institutions, shared processing facilities and long-term supply agreements to improve production reliability and help businesses meet international standards.
The bank’s export financing activities have also expanded as it increases support for businesses involved in international trade.
“Globus Bank’s Nigeria Export Proceeds volume grew from $23 million in 2021 to more than $200 million, while direct export financing rose from $12 million to about $65 million in 2025,” Igbinakenzua said.
The bank ranked ninth among Nigerian banks by export volume, according to figures presented at the summit.
He urged exporters to establish sound governance structures and demonstrate the capacity to fulfil contracts, while encouraging financial institutions and government agencies to work together to address the challenges confronting the sector.
Nonye Ayeni, executive director and chief executive officer of the Nigerian Export Promotion Council (NEPC), said Nigeria recorded non-oil exports of $6.1 billion in 2025, with 8.02 million metric tonnes of products shipped to about 120 countries.
The exports covered 281 products, including cocoa, urea and fertiliser, cashew and sesame. However, Ayeni said the country still had room to expand production, improve processing and increase the number of businesses participating in international trade.
“Nigeria had almost 50,000 registered exporters, but a small number accounted for about 70 percent of export value, highlighting the need to support small and medium-sized enterprises seeking to enter export markets,” she said.
Ayeni urged banks to expand financing for small businesses, particularly those operating within agricultural clusters, while calling for improvements in product quality, certification and access to new markets.
She also highlighted opportunities under the African Continental Free Trade Area, which covers about 54 countries, a combined gross domestic product of $3.4 trillion and a population of 1.4 billion.
Abubakar Abba Bello, managing director and chief executive officer of the Nigerian Export-Import Bank, represented by Daniella Jarikre-Ikazoboh, head of the Lagos regional office, said access to finance remained a major constraint because exporters often pay for raw materials, labour, processing, certification and logistics before receiving payment from foreign buyers.
“Financing instruments such as pre-shipment and post-shipment facilities, export credit guarantees, receivables financing, letters of credit and equipment financing could help businesses execute contracts and manage transaction risks,” he said.
Bello also called for forward integration, which involves moving beyond the production of raw materials into processing, manufacturing, packaging, branding, distribution and direct market access.
He said the approach could increase domestic value addition, create jobs, facilitate technology transfer and strengthen local industries. However, its success would depend on reliable raw material supplies, adequate energy, skilled personnel, appropriate technology and proven market demand.
John Alamu, founder and group managing director of CapitalSage Holdings, said the cost of financing local processing remained a major obstacle for Nigerian manufacturers and exporters.
Using cocoa processing as an example, he said a combined processing capacity of 48,000 metric tonnes at between N7 million and N7.2 million per tonne would require working capital of about N330 billion. At an interest rate of 27 percent, the financing cost would exceed N90 billion.
Alamu said banks often favoured working capital over capital expenditure, leaving processors to rely on development finance institutions and international lenders for investments in equipment and production facilities.
Alamu also said processing cocoa into butter could multiply its value about six times, while converting it into chocolate could increase its value more than 30 times.
Beyond financing, exporters face increasing pressure to meet international traceability and sustainability requirements.
Read also: Egypt clears $454m Banque du Caire share sale as IPO process advances
Participants at the summit warned that Nigeria’s agricultural exports could face greater difficulties if producers failed to comply with the European Union Deforestation Regulation, which requires businesses to demonstrate the origin of commodities and establish that products are not linked to deforestation.
Tarun Kumar Das, managing director of Springfield Agro Limited, said Nigeria loses about $360 million through export bans, primarily affecting cocoa.
He warned that stricter sustainability requirements could create additional costs for smallholder farmers and exporters who lack the resources to maintain detailed production records.
He called for farmers to be organised into cooperatives and for aggregators and off-takers to help collect traceability information. Digital farm mapping, he said, could improve compliance and support access to international markets.
At a separate panel on trade facilitation, officials highlighted the National Single Window project as an initiative designed to streamline trade documentation and improve coordination among regulatory agencies.
Peter O. Ekukoya, director of the National Single Window Project, said the first phase went live on March 27 and had stabilised after initial implementation challenges.
Read also: Beyond 23% MPR, should CBN reconsider 45% CRR to unlock credit?
“The next phase was planned in two stages, with the first expected in December and the second, incorporating the Central Bank of Nigeria’s Trade Monitoring System, in the first quarter of the following year,” he said.
The summit concluded with Globus Bank recognising its partners and organisations for their contributions to Nigeria’s non-oil export sector.
Related News

Chinwe Michael is a Nigerian business journalist and media professional with over 4 years of experience covering companies, financial markets, banking, fintech, economic policy, financial inclusion, and corporate affairs. She currently leads the Companies & Markets desk at BusinessDay, where she drives coverage of Nigeria’s corporate and capital markets, translates complex financial data into accessible stories, and mentors younger journalists. Prior to that, she was the head of the financial inclusion/fintech desk. With a background in banking and finance and extensive experience in media and communications, Michael has developed expertise in financial journalism, economic analysis, investigative reporting and market intelligence. Her work examines how monetary policy, corporate performance, capital flows, technology, and regulatory decisions affect businesses, investors, and households. She was selected from about 3,000 applicants as one of 20 journalists for Cohort 4 of the MTN Media Innovation Programme, gaining exposure to new approaches to journalism, technology, and media innovation. Her international journalism experience and engagement with professionals across Russia, Dubai, Saudi Arabia, and others in different sectors have further broadened her understanding of global communication and development.

