Whoever wins Brazil's presidential runoff on October 25 will struggle to tame the country's debt and interest rates, economist Monica de Bolle argued in Foreign Affairs on October 22.
De Bolle, a senior fellow at the Peterson Institute for International Economics, says investors who cheered the right's strong first-round showing are misreading the outlook. Even if Senator Flavio Bolsonaro beats President Luiz Inacio Lula da Silva, "the prospects for the Brazilian economy are dim", she wrote, because his plans fall far short of the fiscal consolidation needed and his hostility to the country's institutions would scare investors off.
Investors took the opposite view. Brazil's benchmark Ibovespa jumped 7.7% to a record on October 5, its biggest one-day rise in more than six years, after Bolsonaro took 47.03% of the first-round vote against 45.16% for Lula. His right-wing Liberal Party (PL) also became the largest party in both houses of Congress.
Debt and dear money
Brazil's sovereign debt has climbed to 83% of GDP, deficits leave no room for extra spending and high interest rates are squeezing households and businesses. The Iran war has pushed up fuel and other prices on top of that, hitting families already carrying heavy debts.
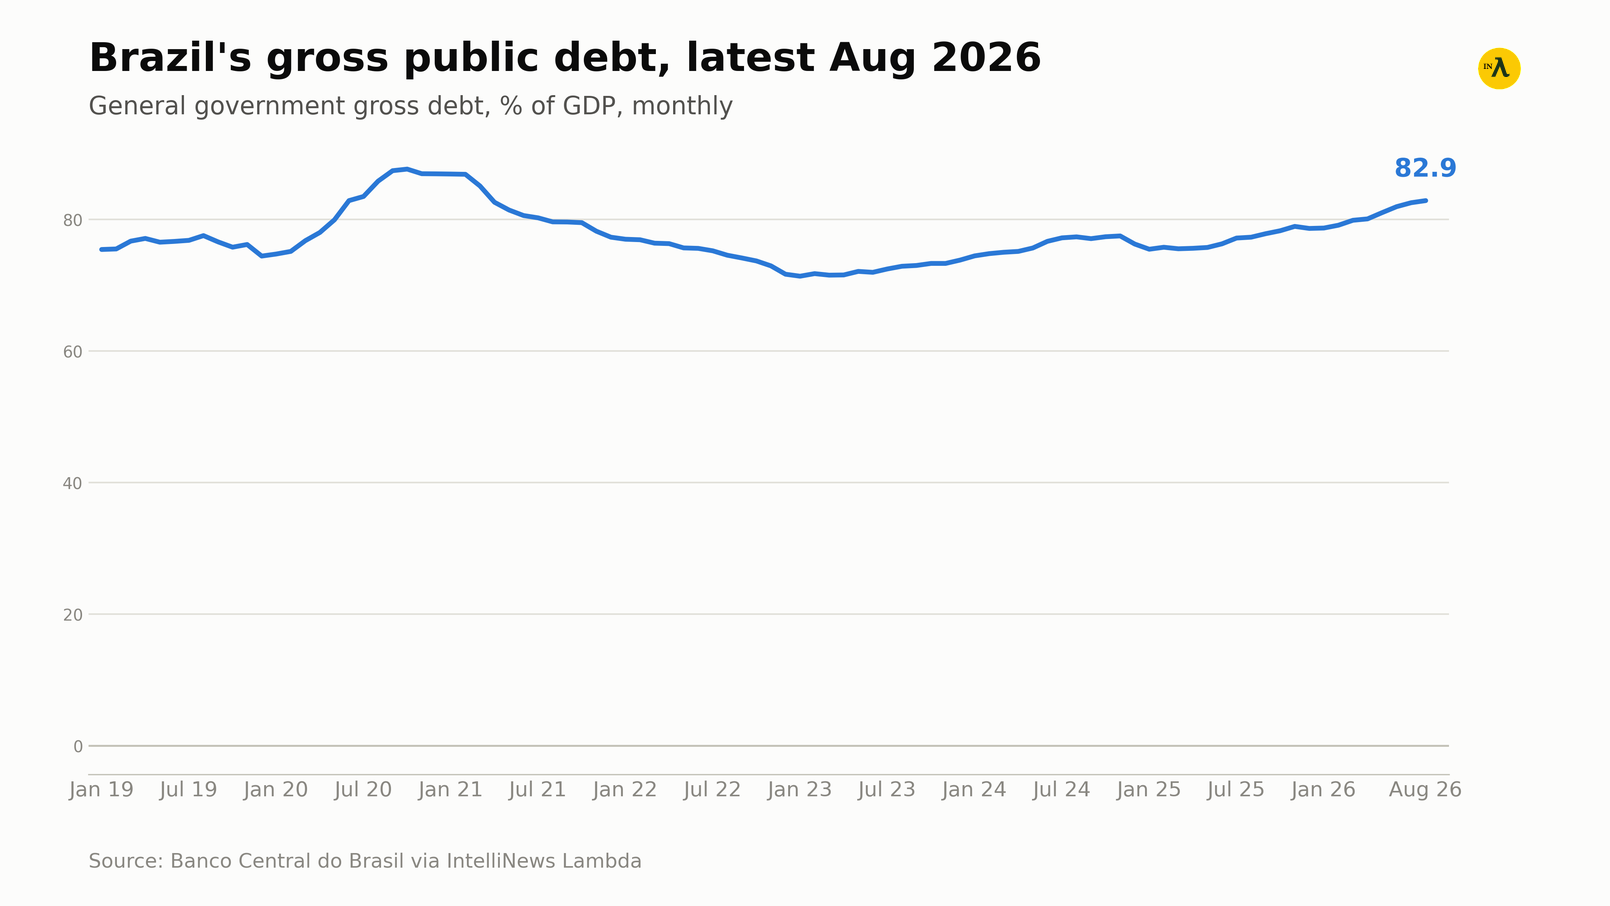
Brazil's gross public debt has risen by more than 11 percentage points of GDP since Lula took office in January 2023. Source: Banco Central do Brasil via IntelliNews Lambda.
Central bank data put general government gross debt at 82.9% of GDP, or about BRL11.1 trillion ($2.2 trillion), in August, up from 71.7% in December 2022, just before Lula returned to office. The consolidated public sector ran a primary deficit of BRL82.1bn ($16.3bn), or 0.62% of GDP, over the 12 months to August.
De Bolle traces the problem back a decade. President Michel Temer wrote a spending cap into the constitution so later governments could not loosen it, but Jair Bolsonaro raised the ceiling several times anyway, winning constitutional amendments from Congress in exchange for handing lawmakers effective control of the budget.
Lula inherited a system with little room to adjust and did little to change it. Large deficits and sticky inflation followed, the central bank raised rates hard, and investment and growth suffered.
The central bank's Selic rate stands at 13.75% after a quarter-point cut on September 16, which de Bolle calls "astronomical by Latin American standards". Servicing the public debt eats up about 8.7% of GDP, she wrote, so neither candidate could cut rates sharply without tipping the economy into recession.
Promises without numbers
A re-elected Lula would find reform close to impossible, de Bolle argues. He has promised to rein in spending and overhaul the tax system, but the PL and its allies now hold a majority in both chambers and could block his bills. The PL alone won 121 lower house seats.
Expecting Bolsonaro to do better is "overly optimistic, if not completely unrealistic", she wrote. His party has promised to cut government spending by BRL200bn ($39.6bn), or 1.5% of GDP, and to run primary surpluses, but has not explained how, and Bolsonaro has pledged not to touch pensions or key social programmes. Scrapping at least ten ministries comes with no estimate of savings, and his father's similar cuts in 2019 did little for the public finances.
Other pledges would widen the gap, de Bolle says. They include a lower value-added tax, phasing out the tax on financial transactions, cheaper electricity and fuel through tax cuts, $180bn of infrastructure spending over four years and 2.5mn new homes. Bolsonaro's advisers also want to reverse every tax created or raised under Finance Minister Fernando Haddad, which were meant to shift the burden onto higher earners and lifted revenue modestly without producing surpluses. Bolsonaro says those taxes deter investment, but "there is no evidence to support this idea", de Bolle wrote.
By her own estimate, Brazil needs to improve its primary balance by about 6% of GDP to stop debt rising, phased over at least three years to avoid a recession. Both candidates are instead courting self-employed, lower-middle-class voters who climbed out of poverty during Lula's first two terms and have since seen their incomes stall, with promises of income support and household debt relief that would deepen the hole.
The authoritarian risk
De Bolle's sharper warning is political. Bolsonaro has talked of "institutional reforms", including amending the 38-year-old constitution to loosen labour and environmental rules, reining in the Supreme Court and an amnesty for his father, who is in prison for a coup attempt. Removing a Supreme Court justice takes a two-thirds Senate vote and a constitutional amendment needs three-fifths of both houses, so the government would have to buy support from lawmakers outside its coalition with funds for their constituencies, adding to the deficit.
Flavio Bolsonaro has never disowned his father's praise for the 1964-85 military dictatorship, and his party descends from the one that sustained the regime, she wrote. His brother Eduardo, a former congressman likely to play a big role in any government, has said he wants to learn the "best practices" of Viktor Orban's government in Hungary. The senator is also under investigation in the same corruption scandal that has touched several Supreme Court justices.
The dictatorship years serve as a warning, de Bolle argues. The military regime spent unsustainably on state enterprises to stay in power, Brazil defaulted on its debt, hyperinflation set in, inequality soared and six stabilisation plans failed. No Latin American country that swapped democracy for authoritarian rule in the past century gained economically from the switch, she wrote, and the East Asian economies that prospered under such regimes became less authoritarian as they grew.
"A decisive turn toward illiberalism would all but assure economic disaster," she wrote, placing Brazil's far right alongside the movements in Argentina, Chile and Colombia that sell voters a libertarian vision with little to back it. What it offers, she concluded, is "empty promises".
A Quaest poll released on October 21 showed Bolsonaro's lead narrowing to one point, at 45% to 44%, within the margin of error, and the two candidates agreed on October 22 to disclose their bank and tax records after trading corruption accusations in a televised debate. Whoever takes office on January 1 will face a fiscal hole that neither campaign has offered to fill.