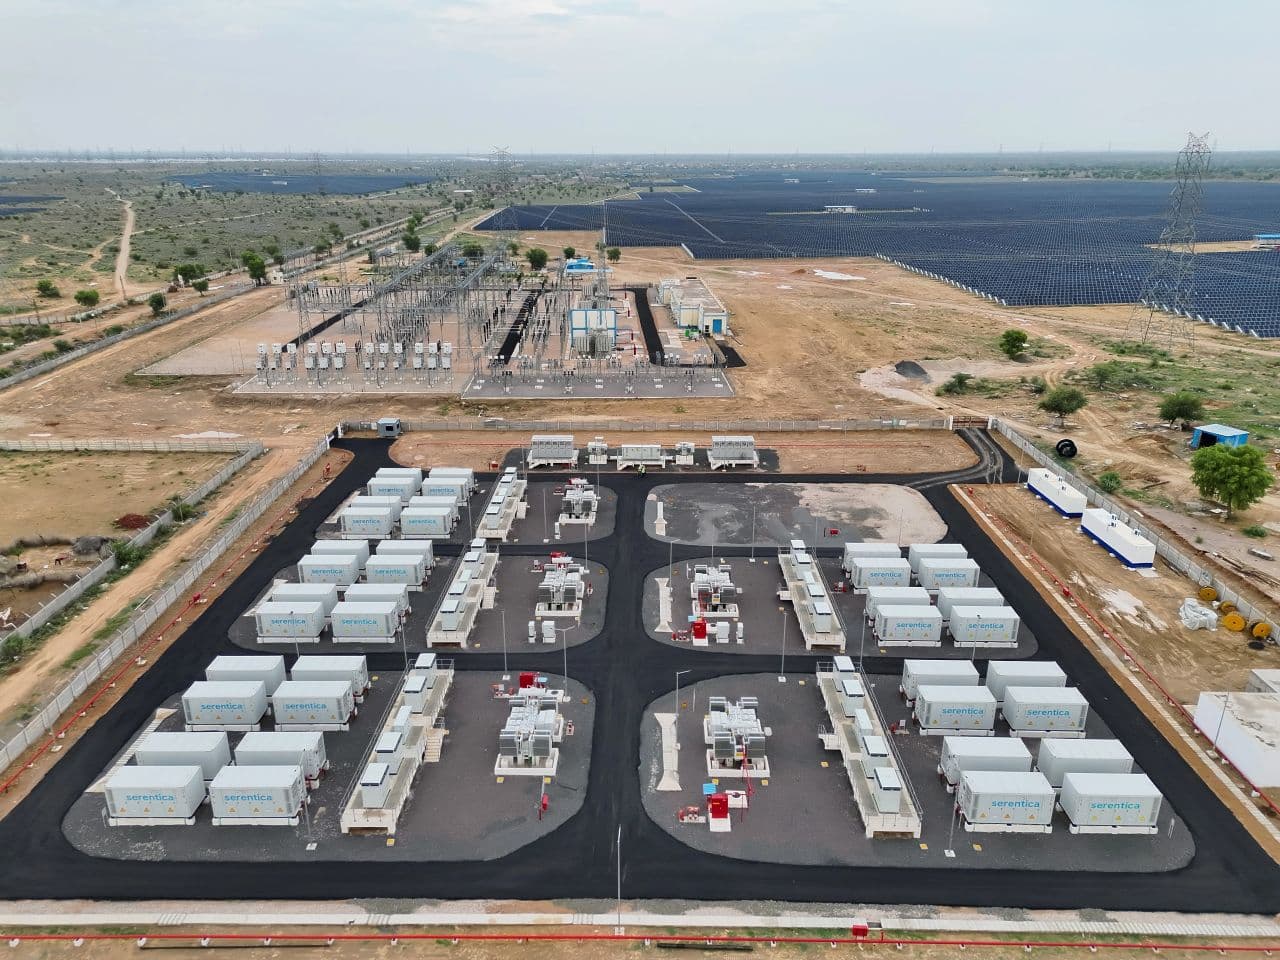
The volume is genuinely extraordinary. Government-owned undertakings including Solar Energy Corp. of India (SECI), Powergrid, NLC India, and NTPC – along with a widening range of local utilities in Gujarat, Rajasthan, Andhra Pradesh, Maharashtra, and other states – collectively floated more than 130 GWh of storage-linked tenders in 2025 alone. SECI’s FDRE-IX tender, seeking 1.2 GW of firm and dispatchable renewable capacity backed by roughly 4.8 GWh of storage, is now the largest single storage-linked pipeline the country has issued.
None of this would be bankable without Viability Gap Funding (VGF). Tranche I offered capital support of up to INR 2.7 million ($28,170)/MWh. Tranche II, revised in July 2025 as system costs fell, cut that to around INR 1.8 million/MWh. In May 2026, the Union Cabinet approved a further outlay of roughly INR 54 billion to support close to 30 GWh of additional storage capacity. As of mid-2026, the sector had 28 awarded tenders and more than 90 individual bid positions on record.
Price collapse
The pricing trajectory is the number every developer quotes, and it deserves to be. India’s first pilot tender in 2022 cleared at INR 1.08 million/MW/month. By December 2025, Andhra Pradesh utility Aptransco’s tender discovered a record low of INR 148,000/MW/month. Two-hour systems now typically clear between INR 148,000 and INR 255,000/MW/month. Four-hour systems, which carry a heavier duty cycle, sit between INR 285,000/MW/month and INR 457,000/MW/month.
Two forces are driving these plummeting prices. Cell and pack costs have fallen sharply, and the bidder pool has widened well beyond the original storage specialists. Public sector undertakings like NTPC Green Energy, Tata Power, Powergrid and others are now bidding alongside dedicated renewable energy project developers such as Pace Digitek, Oriana Power, Bondada Engineering and Stockwell Solar, and balance-sheet strength is compressing margins across the board. That is both healthy competition and a warning sign. Tariffs this low leave almost no room to absorb the execution risk sitting on the other side of the ledger.
Hidden figure
Here is what the tariff story tends to leave out: in 2024, roughly 8.5 GW of utility-scale renewable tenders in India went undersubscribed, nearly five times the undersubscription rate seen in 2023. Storage-linked capacity – overwhelmingly the more complex Firm and Dispatchable Renewable Energy (FDRE) and round-the-clock (RTC) tender formats – accounted for close to 44% of that shortfall. Between 2020 and 2024, close to 38 GW of tendered renewable capacity was canceled outright, and cancellation rates for some FDRE structures ran past 65%.
Developers are still interested in energy storage projects, but India’s distribution companies are losing the ability to commit to them. State distribution utilities were carrying accumulated losses of close to INR 6.92 trillion as of March 2024, with collective outstanding debts above INR 7.5 trillion and growing at roughly 12% a year. Utilities in that financial position are understandably wary of long-term contracts with rigid, high-cost obligations. SECI’s RTC-IV tender discovered a tariff of INR 5.06/kWh to INR 5.07/kWh, meaningfully above standalone battery energy storage system (BESS) economics, and these have struggled to attract the same appetite as simpler formats. Add to this a transmission buildout that hasn’t kept pace with renewable capacity additions, with industry estimates putting 40 GW to 55 GW of renewable capacity stuck waiting on power purchase agreements or grid connection, and you get the outcome we saw in January 2025: the Central Electricity Regulatory Commission canceled a 500 MW/1,000 MWh SECI standalone BESS tender simply because project agreements couldn’t be signed in time.
Practical solutions
The market correction is instructive. Developers and procurers are moving from FDRE and RTC’s complex, demand-following obligations to the simplest bankable product available: standalone two-hour BESS, VGF-supported, with a simple capacity charge. It closes faster, prices more predictably, and doesn’t ask distribution companies (discoms) to underwrite risk they can’t carry.
Projects developing outside the tender process are also significant. Merchant BESS capacity built to trade on the exchange rather than under a PPA accounted for 70% of India’s capacity additions in the first half of 2026. SECI’s FDRE-IX now permits developers to sell surplus storage capacity on the spot market outside the guaranteed peak window, effectively blending a fixed PPA with market arbitrage. As PV penetration widens the day-ahead price spread, this hybrid model is doing more to derisk project economics than any tariff discovery mechanism has managed on its own.
Leadership call
Long-term demand for storage in India is not in doubt. The Central Electricity Authority has estimated a requirement of over 400 GWh by 2032; more recent industry projections put the figure closer to 888 GWh by 2036, against roughly 9 GWh installed today. Even the more conservative estimates from a few years ago now look understated. What the sector needs next is tender volume that discoms can actually sign, and projects that can be financed. That means standardizing on the simplest bankable structure instead of continuing to push FDRE complexity onto utilities that can’t absorb it. Payment security should be fixed through stronger letter-of-credit and escrow mechanisms before scaling further. Transmission planning should be sequenced ahead of tender issuance rather than after. Well-run projects should be allowed to capture merchant upside so tariffs aren’t forced to carry the entire burden of project economics.
Capacity tendered is a headline. Capacity commissioned, paid for on time, and actually dispatched is the only number that should lead the story, and it’s the one our industry needs to start reporting first, not last.
The post Pricing India’s storage demand gap appeared first on pv magazine Global.