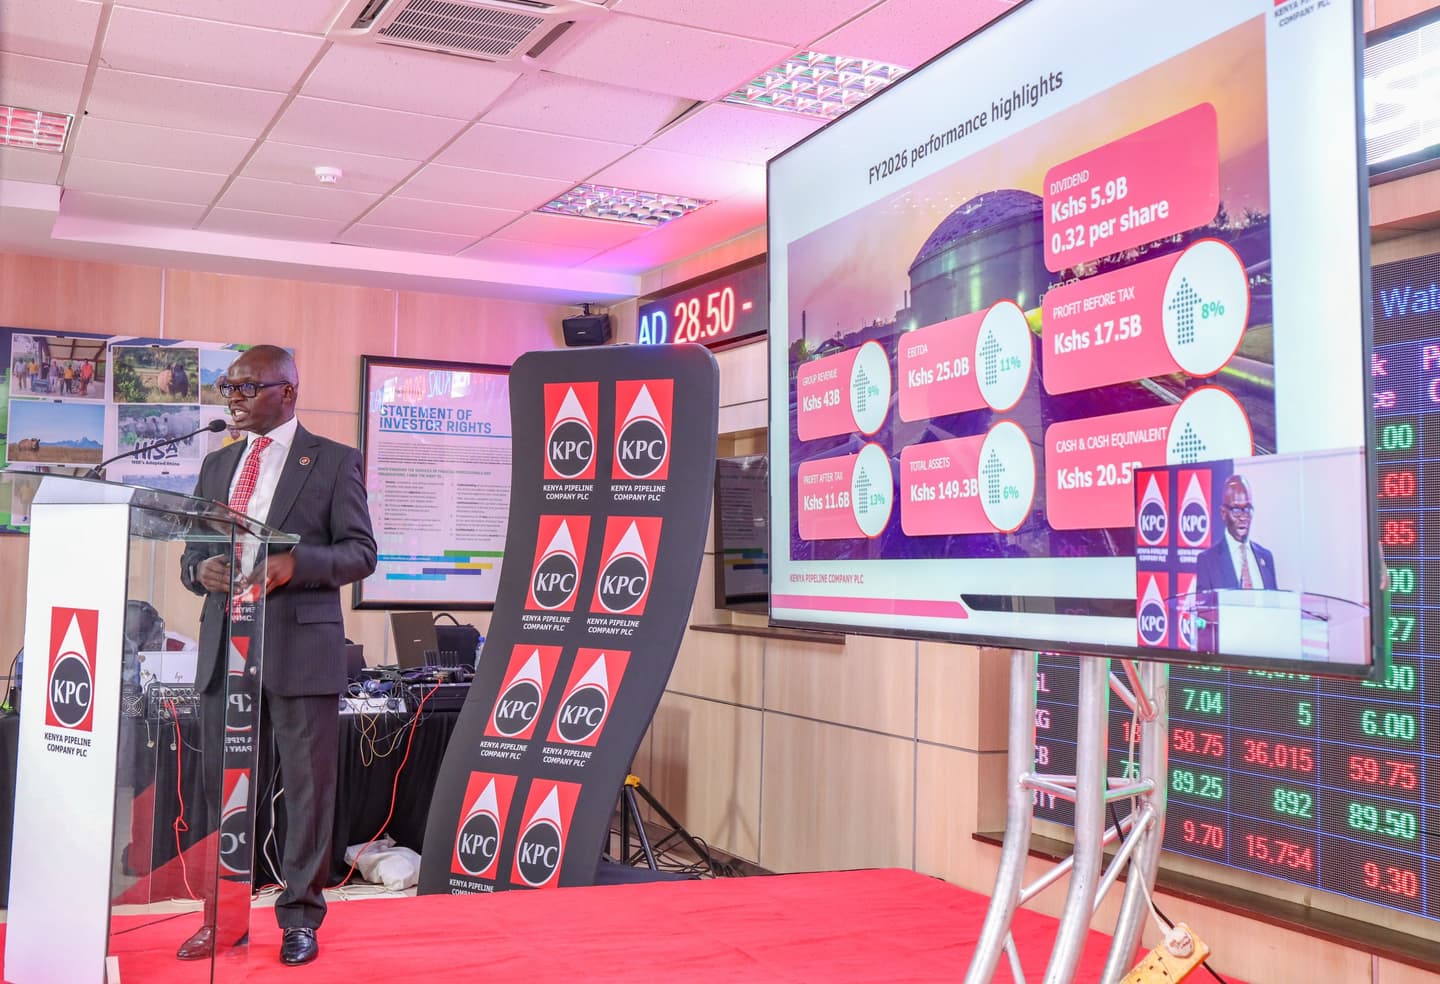
Kenya Pipeline Company PLC (KPC) reported a 13% increase in profit after tax to KSh11.6 billion for the 2025/26 financial year, as revenue grew 9% to KSh42.98 billion on stronger transport and storage business. The results give the state-owned petroleum infrastructure operator a stronger earnings base as it considers new commercial ventures and prepares a capital structure covering the period to 2030.
The company also reported an 11% increase in earnings before interest, tax, depreciation and amortisation (EBITDA) to KSh25 billion, while profit before tax rose 8% to KSh17.5 billion. Total assets increased 5.9% to KSh149.3 billion, according to the financial presentation delivered at the Nairobi Securities Exchange on Wednesday, October 14.
The briefing was one of KPC’s early major investor engagements since its listing on the NSE in March 2026. Acting Chief Executive Officer and Managing Director Pius Mwendwa said the company was pursuing regional commercial opportunities alongside its established petroleum transportation and storage operations.
KPC earnings growth driven by transport and storage
Transport revenue rose 8% to KSh41.82 billion from KSh38.59 billion in the previous financial year. Total revenue reached KSh42.98 billion, compared with KSh39.50 billion a year earlier, reflecting the importance of KPC’s core infrastructure business to its financial performance.
The company handled approximately 10.6 billion litres of petroleum products during the year. Its pipeline network spans 1,342 kilometres, while active storage capacity stands at approximately 1.14 billion litres. These assets support the movement and storage of petroleum products for the Kenyan market and neighbouring countries.
KPC reported that direct expenses increased 8% to KSh9.1 billion, with higher electricity and maintenance costs associated with throughput and infrastructure upkeep contributing to the increase. Operating costs rose 4% to KSh8.8 billion. Despite these pressures, EBITDA grew faster than revenue, indicating that the company generated stronger operating earnings during the year.
The results also reflect KPC’s position in regional petroleum logistics. Its reported throughput includes volumes destined for markets beyond Kenya, including Uganda, the Democratic Republic of the Congo and South Sudan. Maintaining reliable infrastructure and serving these corridors will remain central to its established business as management pursues additional revenue opportunities.
Cash generation strengthens as borrowings fall
KPC’s operating cash flow increased 34.3% to KSh17.39 billion from KSh12.94 billion in FY2024/25. Its closing cash and cash equivalents rose 84.4% to KSh20.54 billion, compared with KSh11.14 billion in the preceding financial year.
The balance sheet also showed lower borrowing. Outstanding borrowings fell 83.4% to KSh400 million, while current liabilities declined 47% to KSh6.5 billion. Shareholders’ equity increased 10.6% to KSh119.3 billion, and the current ratio stood at 4.65 times.
The figures give KPC a stronger financial position as it evaluates new infrastructure and commercial projects. However, cash balances and operating cash flow serve different purposes: cash must also support the company’s working capital, maintenance obligations and other operating requirements, while large expansion projects may require separate financing arrangements.
Capital expenditure increased to KSh4.48 billion from KSh2.52 billion in the previous year, according to the cash flow presentation. This provides context for management’s plans to expand beyond existing transport and storage services, where new investments will need to be assessed against the company’s operating needs and expected returns.
KPC weighs regional trading hub and new commercial ventures
KPC is considering a petroleum trading hub that could add activities such as bunkering, transshipment, storage-for-hire and related maritime services to its established infrastructure business. Management has described the proposed hub as complementary to existing operations, with the potential to use KPC’s storage and logistics capabilities to serve a broader regional petroleum market.
The activities would offer different routes to commercial growth. Bunkering involves supplying marine fuel to vessels, while transshipment allows cargo to be transferred between vessels for onward delivery. A broader trading hub could combine storage and handling with blending, re-export and other services linked to petroleum trading.
During the question-and-answer session, Mwendwa said the hub’s earnings potential and capital requirements were still being evaluated. Management expects the venture to benefit from KPC’s existing infrastructure and cost base, with returns comparable to those from its storage operations. That expectation will be central to assessing the commercial case for the project as its plans develop.
The company is also looking at potential roles connected to the Dangote refinery, including petroleum storage, transportation and pipeline services. Mwendwa framed the opportunity around KPC’s ability to support regional petroleum logistics. These are prospective commercial opportunities rather than confirmed contracts.
KPC’s fibre-optic cable business offers another route to diversification. The company has used its pipeline right-of-way to support fibre infrastructure and has previously worked with Syokinet Solutions to activate capacity on the Mombasa-Nairobi route. The business draws on an existing infrastructure corridor to serve telecommunications operators, giving KPC a commercial activity outside petroleum handling.
The financial results presentation identifies fibre optics and the proposed trading hub among the company’s diversification priorities. Their contribution to future growth will depend on customer demand, investment requirements and the ability to turn infrastructure access into sustained commercial returns.
Capital plan through 2030 puts funding in focus
KPC’s management said a capital structure covering the period to 2030 would be presented to shareholders at the annual general meeting for validation. Potential funding routes include debt and project financing, with management positioning regional expansion as part of its longer-term growth strategy.
The financing framework will be important as KPC considers investments in its petroleum trading hub, pipeline capacity and regional infrastructure. These projects can require substantial upfront capital, while their returns depend on utilisation, customer commitments and the ability to compete in regional markets.
The company’s five-year strategic plan for 2025/26 to 2029/30 places diversification and growth alongside operational excellence, environmental, social and governance priorities, and workforce development. Regional opportunities include strengthening petroleum infrastructure serving Uganda and other neighbouring markets, as well as developing additional storage and logistics services.
KPC’s proposed capital plan also comes after its transition to public listing. The company now has an expanded investor audience interested in how management balances infrastructure investment, financial resilience and shareholder returns. A capital framework extending to 2030 will help define how those priorities fit together.
Proposed KSh5.9 billion dividend comes under scrutiny
KPC proposed a dividend payout of KSh5.9 billion, equivalent to KSh0.32 per share. During the results briefing, an investor asked why the per-share dividend had declined from KSh0.347 despite the total payout remaining at approximately KSh5.9 billion.
Management referred to the company’s policy of distributing 50% of earnings and said the proposed dividend would go through the shareholder approval process. Mwendwa also said KPC had paid approximately KSh24 billion in dividends to the government over the preceding five years, highlighting the company’s long-standing role as a source of public revenue.
The proposed payout is close to half of the KSh11.6 billion profit after tax reported for FY2025/26. For shareholders, the dividend sits alongside the company’s plans to fund new ventures and maintain its existing infrastructure. How KPC allocates cash between distributions and investment will remain a key consideration as the capital plan proceeds to the AGM.
KPC’s latest results show stronger earnings, increased operating cash flow and a balance sheet with substantially lower borrowings. Its next set of commercial decisions will determine how it uses that financial position to build additional revenue streams while continuing to operate the petroleum infrastructure on which its core business depends.
Real ESG impact doesn’t happen in panels alone, it happens in the rooms where financiers, operators, and policymakers actually align. Our GreenShift Forum 2026 cuts the noise, bringing together the people rewiring Africa’s sustainability and energy frameworks for one focused day in Nairobi. Secure your seat.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to info@techtrendsmedia.co.ke