Many bank-fintech acquisitions raise one question: can a bank buy what a fintech built without changing what made it work? Tearsheet’s feature explored that question through Valley National Bank’s $340 million acquisition of Bluevine, expected to close in early 2027.
The deal brings together two sets of strengths. Valley gains Bluevine’s digital banking platform for small businesses, its customer-acquisition capabilities, and a research and development team of about 180 people. Building these capabilities in-house would have taken significant time for Valley. Bluevine, in turn, can draw on Valley’s balance sheet, banking capabilities, and physical branch network of more than 220 locations, extending the resources and reach available to its customers.
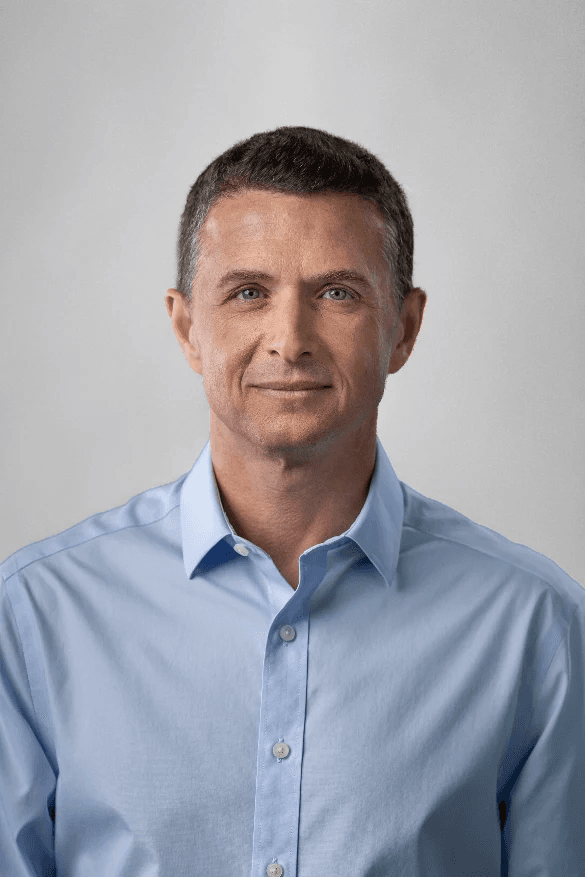
Tearsheet Managing Editor Sara Khairi spoke with Eyal Lifshitz, CEO of Bluevine, about what needs to remain intact for both sides to realize the deal’s potential. Lifshitz, who is expected to lead Small Business Banking at Valley following the planned close, discussed the culture Bluevine wants to preserve and the potential for its technology to be used more broadly across the bank.
Q: What did Bluevine build that Valley concluded would be materially harder or slower to build itself?
Eyal Lifshitz, CEO of Bluevine: What Bluevine brings is less about any single product or capability and more about the combination it has built at scale: a nationwide digital small business banking platform, a proven customer-acquisition engine, a full-stack banking and lending platform including sophisticated core elements, risk systems, and small business expertise.
…
The post How Bluevine will change under Valley Bank without losing its core appeared first on Tearsheet.