Insurance is no longer just about writing a cheque after something goes wrong. As cyberattacks, AI-driven fraud, operational disruptions, and emerging digital risks become increasingly unpredictable, businesses are turning to technology to identify and mitigate risks before they translate into losses. AI, in particular, is reshaping how risks are assessed, policies are structured, and businesses prepare for threats that are evolving faster than traditional insurance models.
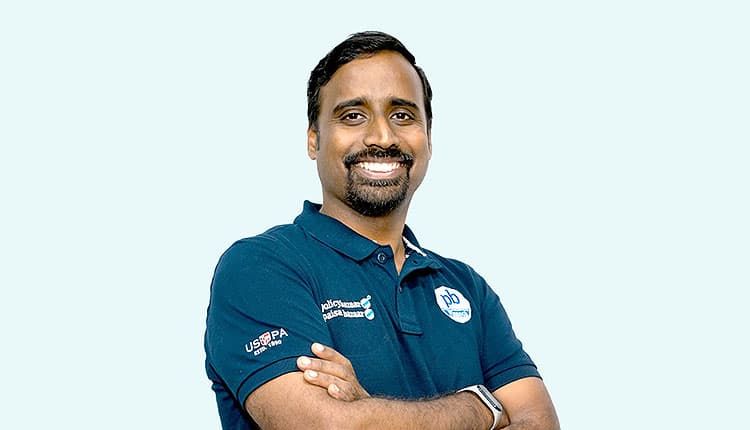
In an exclusive interaction with Express Computer, Sajja Praveen Chowdary, Director, Policybazaar for Business, discusses how technology is pushing insurance from a reactive safety net to a proactive risk-management tool. He also highlights the growing cyber insurance protection gap, the potential for dynamic risk assessment and pricing, and why Indian businesses need to move beyond treating insurance as an annual procurement exercise.
Insurance is often seen as a reactive product, something companies buy after identifying a risk. Is technology changing insurance into a more proactive risk-management tool? What role is AI playing in that shift?
Yes, I strongly believe that technology is changing the perception of insurance into a more proactive risk-management tool. Insurance is increasingly moving from being something businesses turn to after a risk has materialised to becoming part of how they anticipate and manage risks.
With better data, analytics and real-time monitoring, businesses can identify vulnerabilities beforehand and take preventive action rather than simply responding to losses.
AI is accelerating this shift. It can bring together large amounts of data, identify patterns and flag potential risks much faster than traditional approaches. For businesses, this could mean earlier warnings around cyber threats, fraud, operational disruptions and other emerging risks.
The role of insurance is therefore gradually expanding from simply transferring risk after an incident to helping businesses understand, manage and potentially reduce that risk in the first place.
Cyberattacks, AI-generated fraud and data breaches are evolving faster than traditional insurance models. Are Indian businesses adequately insured against these new-age risks, or is there still a major protection gap?
I believe there is still a significant protection gap, particularly among smaller businesses. The nature of cyber risk is changing very quickly, while many organisations continue to approach cyber insurance as a compliance requirement or a last line of defence rather than as part of their broader risk-management strategy.
AI is also making the threat landscape more complex. Businesses now have to think beyond traditional data breaches and consider risks such as deepfakes, AI-enabled fraud, social engineering, ransomware and attacks on increasingly interconnected systems.
At the same time, having an insurance policy does not automatically mean being fully protected. Businesses need to understand what is covered under their cyber insurance policy, the exclusions and policy limits, as well as the security controls insurers expect them to have in place.
The larger shift we are seeing is that cyber insurance is becoming less about simply paying for losses after an attack and more about helping businesses build resilience before an incident happens. Stronger risk assessment, incident-response capabilities, and the use of technology can make a real difference here.
Policybazaar for Business works with enterprises across different sectors. What is the biggest misconception you see companies making when it comes to managing their insurance and risk?
One of the biggest misconceptions enterprises have is that having an insurance policy means the risk is fully taken care of. In reality, insurance is only one part of a broader risk-management strategy.
We often see businesses focus on the premium or the sum insured but not spend enough time understanding what the policy actually covers, where the exclusions are, or whether the coverage keeps pace with how their business is evolving.
Another misconception is that insurance is something to look at once a year, usually around renewal time. However, business risks can change much faster than that. A company may enter new markets, adopt new technology, take on larger contracts, or become exposed to risks it did not face a year earlier.
The bigger takeaway for businesses is that insurance should be treated as a strategic risk-management decision, not just an annual procurement exercise. Companies that regularly review their risk exposures and align their insurance programmes accordingly are better placed to protect cash flows, minimise business disruption and respond effectively when something goes wrong.
With AI transforming everything from underwriting to claims, could we reach a point where an insurance policy is dynamically priced based on a company’s real-time risk profile? How close are we to that reality?
Yes, the insurance industry is headed in that direction, but we are still some distance away from truly real-time pricing.
Technology is already making it possible to continuously assess a company’s risk, but the insurance model has to catch up in areas such as data quality, underwriting frameworks, regulation, and how frequently premiums can realistically be adjusted.
What is more likely in the near term is dynamic risk assessment, where insurers use real-time or near-real-time data to identify changes in a company’s cyber posture, claims history, operational risks, or other exposures and factor those insights into underwriting and renewals.
The interesting shift is that risk management could become much more measurable. If a company strengthens its cybersecurity, improves safety systems, or reduces its exposure, it could potentially demonstrate that improvement through data rather than waiting until the next annual renewal.
I would say that the technology is moving faster than the insurance model. The next step is building a framework where insurers can use that data to make coverage and pricing more responsive, while keeping the process transparent and commercially practical for businesses.
Looking ahead to the next 3–5 years, what will fundamentally change in the way Indian businesses buy, manage, and think about insurance? And where do you see Policybazaar for Business playing the biggest role in that transformation?
Over the next three to five years, we are likely to see much greater use of data and technology in how risks are assessed, policies are structured, coverage is reviewed, and claims are managed.
I think the biggest change will be that businesses will stop looking at insurance as a yearly purchase and start treating it as an ongoing risk-management function.
Businesses will also become more sophisticated about the risks they are trying to protect against. Cyber, climate-related risks, supply-chain disruptions, liability, and newer technology-led risks will increasingly sit alongside traditional covers.
The conversation will move from simply asking, “How much coverage do we need?” to asking, “What are the risks that could materially impact our business, and how do we manage them?”
For Policybazaar for Business, I see the biggest opportunity in making this entire process simpler, more transparent, and more data-driven for businesses. Our role is not just to help a company buy a policy, but to help it understand its risk, identify gaps in its existing coverage, and make better-informed insurance decisions. Ultimately, the transformation will shift insurance from a transaction to a strategic business tool.