Sustaining Sri Lanka’s hard-won macroeconomic stability in the wake of its worst financial crisis requires an immediate transition from emergency recovery measures to structural, productivity-enhancing reforms. This strategic pivot was the central thesis of a high-level roundtable discussion convened by the Institute of Policy Studies of Sri Lanka (IPS) on 14 October 2026, examining the findings of its flagship publication, Sri Lanka State of the Economy 2026.
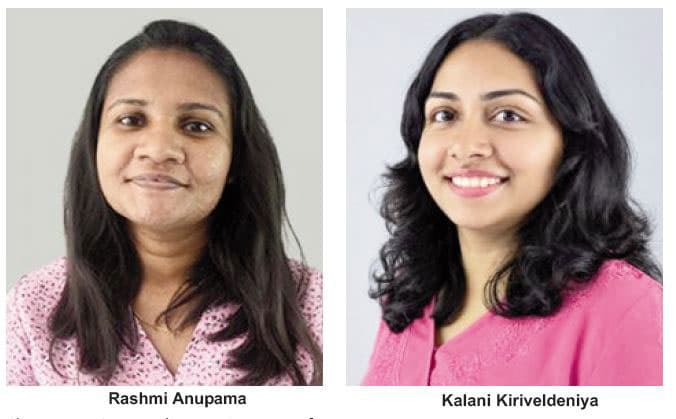
Synthesising insights from IPS Research Assistants Rashmi Anupama and Kalani Kiriveldeniya, the report presents a sobering yet actionable roadmap. It highlights that while initial stabilization under fiscal consolidation and external debt management has provided vital breathing space, long-term economic survival hinges on building durable resilience against persistent domestic and global vulnerabilities.
While Sri Lanka registered a Gross Domestic Product (GDP) growth rate of 4.2% in the second quarter of 2026—backed by an encouraging rebound in investment—economic research indicates that a far steeper trajectory is required to restore long-term output. IPS Research Fellow Dr. Asanka Wijesinghe observed that the country must achieve a sustained annual growth rate of approximately 8.3% between 2026 and 2030 to regain its pre-crisis growth baseline. Accelerating policy interventions to meet or exceed the official medium-term target of 7% remains an imperative.
However, near-term growth encounters immediate headwinds. Global energy price volatility has elevated import bills, widening the merchandise trade deficit significantly over the January–August 2026 period relative to 2025. Because domestic demand-led growth carries inherent balance-of-payments limitations, export expansion must serve as the primary engine of long-term economic expansion.
Sri Lanka’s merchandise export sector faces serious structural challenges in key Western markets. Traditional reliance on non-reciprocal market preferences, such as the European Union’s GSP+ scheme, is becoming increasingly precarious. Competing regional economies are actively securing reciprocal trade agreements—such as Indonesia’s preferential trade arrangements with the EU and India’s bilateral trade pact with the UK—threatening to erode Sri Lanka’s market share.
To address these disadvantages, the report advocates for predictable tariff regimes and systematic domestic trade policy adjustments. However, experts caution against abrupt tariff cuts that could disrupt domestic industries, particularly Micro, Small, and Medium Enterprises (SMEs). The recommendation calls for carefully sequenced tariff reductions alongside a dedicated trade adjustment fund to buffer domestic producers during the transition.
Examining the post-IMF adjustment period, IPS Research Fellow Dr. Lakmini Fernando emphasized reorienting fiscal policy from pure compression toward growth-oriented capital deployment. Government capital expenditure plummeted to historic lows during recent fiscal adjustments, undermining public infrastructure and long-term economic capacity.
To sustain an annual growth target of 7%, gross fixed capital formation must reach an estimated 30–42% of GDP, depending on overall investment efficiency. Reaching these levels demands a dual approach: crowdsourcing private capital within a predictable regulatory environment, while systematically prioritizing public investments in human capital, healthcare, technical skill acquisition, social safety nets, and climate-resilient green infrastructure.
On public finance management, the analysis stresses strict adherence to a medium-term debt management framework, transparent procurement, institutional capacity-building, and continuous engagement with multilateral development banks to manage sovereign debt risks.
Panellists at the IPS event underscored the necessity of synchronized policy action across monetary policy, climate mitigation, and institutional governance:
Monetary Policy Precision: Dr. Yashodha Senadheera, Deputy Director of Economic Research at the Central Bank of Sri Lanka (CBSL), noted that while monetary policy has limited direct leverage over supply-side external shocks, central bank interventions remain essential if imported energy and commodity spikes threaten broader inflation expectations.
Diversification and Technology: Dr. Liliya Aleksanyan, Senior Country Economist at the Asian Development Bank (ADB), urged Sri Lankan exporters to look beyond traditional Western destinations toward expanding Asian markets—such as India—while building national readiness for emerging digital technologies, including artificial intelligence.
Tax Administration and Climate Risk: Sanjaya Ariyawansa, Senior Economist at Sampath Bank, called for expanding the tax base through improved compliance, integrating SMEs into the formal tax system, and establishing independent fiscal oversight. He also emphasized integrating climate-risk assessments into bank risk models, public financial planning, and agricultural support schemes to insulate the financial sector from weather-induced disruptions.
The research report concludes that identifying policy priorities is only half the battle; the true test lies in consistent, forward-looking execution. Closing the gap between annual budget allocations and actual public spending requires improved technical capacity across all stages of project evaluation.
Ultimately, converting Sri Lanka’s fragile recovery into a durable economic expansion demands institutional integrity, structural reform, and an unwavering commitment to insulating the national economy against future global shocks.