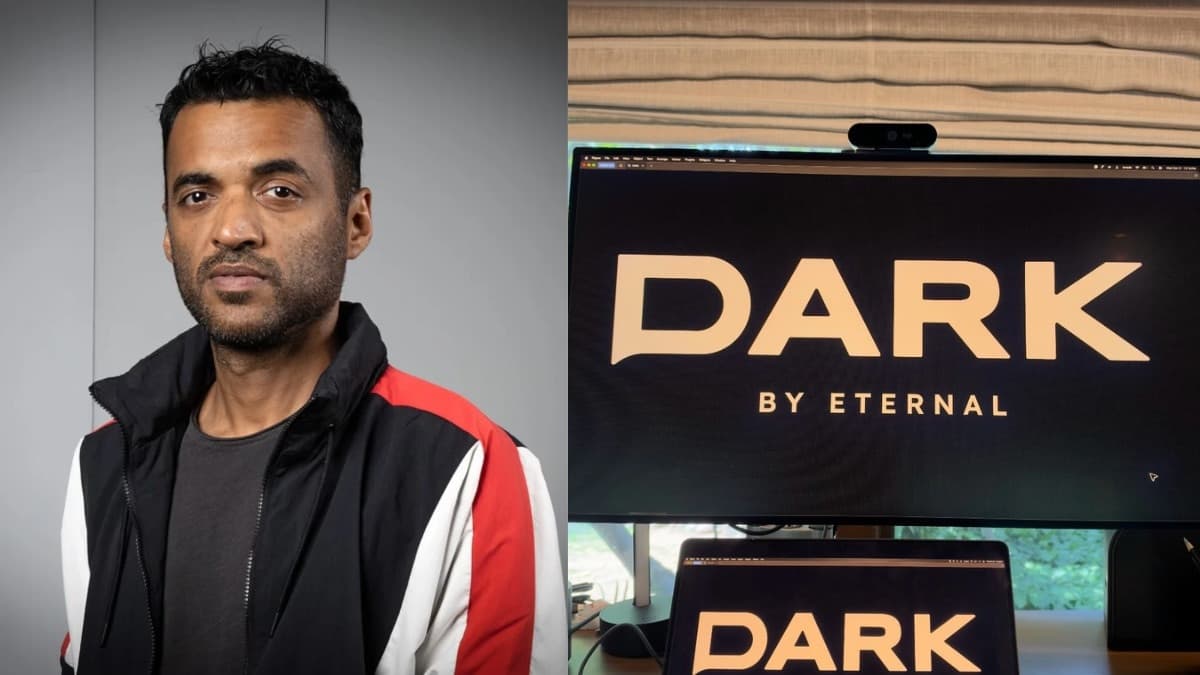
In January, when co-founder Deepinder Goyal stepped away from day-to-day management, he said high-risk ideas belonged outside Eternal. On the Q2 FY27 earnings call, chief financial officer Akshant Goyal said dark.ai had been in the works for about a year.
MUST READ | After Temple, Deepinder Goyal teases Dark.ai: A bet beyond food delivery services
With dark.ai, Eternal is entering an increasingly crowded field of privacy-first AI assistants. Globally, these include Confer from Signal founder Moxie Marlinspike and Lumo from Proton. Closer home, Aprameya Radhakrishna, founder of TaxiForSure and Koo, is building Littl.
Eternal says dark.ai is built for “power users”—founders, researchers, scientists, enterprises and governments that want to keep their thoughts private. It may be priced for them at first, but management has suggested it could eventually become “a product open for all”.
Management calls dark.ai a “zero one bet”—it either becomes a global business or gets shut down—and says spending is “not very meaningful at this stage” and booked in the “Others” segment. But Eternal has disclosed no budget, capex plan or dedicated leadership for the product. Shareholders cannot yet judge how big the bet is, or what guardrails have been built alongside it.
On the analyst call, management said Eternal has “the balance sheet to invest” in such businesses if required, as long as they show returns over the long term. With Rs 16,475 crore in cash reserves, that is a company telling investors it can afford to bet big. It also said that the company was leaning towards technology over services.
The dark.ai launch also pulled attention from the quarter’s numbers. Eternal's net profit rose 92% to Rs 125 crore, from Rs 65 crore a year earlier, but missed brokerage estimates of Rs 170–270 crore. Sequentially, net profit rose 36%. Revenue from operations grew 78% y-o-y, and 19% sequentially, to Rs 24,138 crore, ahead of estimates, and adjusted EBITDA nearly tripled to Rs 666 crore. Other income was Rs 351 crore, more than pre-tax profit of Rs 323 crore.
Profit lagged operating growth largely because of tax: the tax charge rose to Rs 198 crore from Rs 64 crore a year earlier, as the parent company’s carried-forward losses ran out. The stock fell more than 2% after the earnings call.
The biggest contributor, as expected, was quick commerce. Blinkit’s revenue nearly doubled year on year to Rs 19,152 crore, partly because it has moved to an inventory-led model. At Rs 19,152 crore, it is also nearly five times the food delivery business and accounts for more than 77% of the company’s adjusted revenue.
A better measure is net order value. Blinkit’s Net Order Value (NOV) grew 79% year on year to Rs 20,940 crore. That is still fast, but it is slowing: NOV growth has fallen every quarter for a year, from 137% in the September 2025 quarter to 121%, 95%, 86% and now 79%. The company says the base is simply bigger now, and expects growth to pick up from the December quarter as new stores open.
Blinkit added 308 new stores in the quarter, taking its network to 2,751. It now expects to cross 3,500 stores by March 2027 and reach about 5,000 by March 2028. Most of the new stores will come up in smaller cities. That is a change from January, when Eternal said it would go beyond 3,000 stores only if competition eased. It made sense.
Eternal’s own argument was that adding stores during a price war is counter-productive, because new stores fill up with cheap, discount-driven orders and take longer to become profitable. The thinking seems to have changed since. The company now says competition has become more predictable. Smaller cities, it says, are less competitive, order values there are only 10–15% lower than in metros, and customers stay.
Margins, however, remain thin. Blinkit made Rs 184 crore in adjusted EBITDA in the quarter, or 0.9% of NOV, against the 6% the company now assumes at steady state. Cities operating for two to three years already make over 5%. But cities accounting for about 30% of NOV are not yet EBITDA-positive.
Then there is store productivity. Each Blinkit store now does about Rs 9 lakh of NOV a day, up for two quarters running, against a target of Rs 11 lakh. More sales per store should spread fixed costs and lift contribution margin, but it has been weighed down by spending on new stores. Quick commerce, in other words, is still not a settled game. Not even for Blinkit, which has around half the market.
Blinkit also says it has decided against a private-label push, at least for now, which sets it apart from its rivals. Swiggy Instamart sells its own Super Harvest and Noice ranges, Zepto has Relish and Daily Good, and Tata-owned BigBasket has BB Royal. Blinkit’s argument is that own brands neither bring in new customers nor improve margins once the cost of building and marketing them is counted, and that it would rather earn advertising money from the brands on its shelf than compete with them.
After the Q1 FY27 earnings, it was clear that Blinkit’s business was inching closer to the larger e-commerce business. These two segments would eventually converge. This quarter, the company has said as much. CEO Albinder Dhindsa said he doesn’t think the line between quick commerce and e-commerce “will mean much over time”.
“For most purchases, if price and choice are similar, customers prefer to get things sooner. Demand is not the question. The question is whether you can build a supply chain that serves that demand reliably and profitably. That is the problem we have been solving. We want to bring most of what a household buys within 10 minutes,” Dhindsa said in the letter to shareholders.
Quick commerce and e-commerce converging is Eternal’s bet on owning more of the household’s basket. dark.ai is its bet on owning more of the household’s attention. The first bet comes with store counts and margins. The second, so far, comes with a promise.