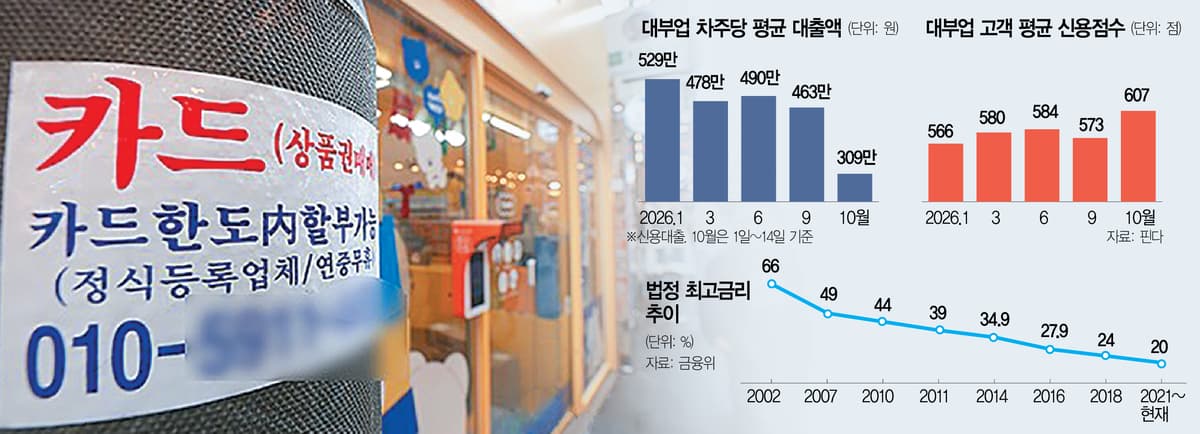
Borrowers at South Korea's cash loan companies — non-bank lenders licensed under the Lending Business Act, the last legal option before illegal private lending — have seen their average credit scores climb 40 points this year, yet the amount they borrow has fallen more than 40%. As funding costs rise, these lenders are screening for borrowers with lower default risk. Critics say the statutory interest rate cap, introduced to ease excessive debt burdens, is now blocking vulnerable borrowers from access to regulated finance during a period of rising rates.
Loans arranged between the 1st and the 14th of this month through Finda, an online loan brokerage platform, averaged 3.09 million won per borrower at cash loan companies, the platform said on the 20th. Their average credit score was 607. Finda currently partners with 17 lenders designated as top-tier operators.
The supply of funds from the sector has contracted through the year. In January, borrowers who took out unsecured loans from these lenders through Finda received an average of 5.29 million won. The per-borrower figure then slipped to 4.78 million won in March, 4.9 million won in June and 4.63 million won in September before dropping to 3.09 million won this month.
Borrower credit quality has moved in the opposite direction. Average credit scores stood at 566 in January, 580 in March, 584 in June and 573 in September before passing 600 this month. Rising market interest rates have pushed up funding costs, while regulators' curbs on household lending have driven customers from second-tier financial institutions toward cash loan companies.
Lenders say they have turned conservative as concerns over negative margins grew following the Bank of Korea's policy rate increase. The cost structure of an unsecured loan at these firms consists of funding costs of 7% to 9% — 5% to 7% for top-tier operators — credit losses of about 10% and brokerage fees of about 2%. With the statutory cap set at 20% and funding costs expanding, they say they have no choice but to concentrate on borrowers who pose little default risk.
"Margins are falling sharply," an official at a large cash loan company said. "We normally supplied more than 20 billion won in loans each month, but we have recently cut monthly supply to the 10 billion won range and are screening for safe borrowers."
Major firms are also holding back on attracting new customers where possible and raising the share of repeat customers with repayment records, according to industry accounts. That has prompted some to warn that the cap could deepen financial exclusion for vulnerable borrowers as rates rise.
The argument is that while the cap has served to ease excessive interest burdens, in a rising-rate environment it can instead become a reason to cut lending to people with low credit scores. The cap began at 66% in 2002, fell to 39% in 2011 and 24% in 2018, and has stood at 20% since 2021.
Market participants worry that if credit scores among these lenders' customers settle in the 600s, vulnerable borrowers scoring below 500 could be pushed into illegal lending. According to NICE Information Service, 63% of borrowers in the sector had credit scores in the 600s or below as of the end of March.
Experts say it is time to consider a cap linked to the policy rate, along with differentiated caps by financial sector. The idea is to build flexibility into the statutory ceiling so that people with low credit scores are not driven off a funding cliff. "The structure already makes it hard for these lenders to profit from unsecured lending," said Kim Sang-bong, a professor of economics at Hansung University. "For a sustainable ecosystem, we need to introduce a plan that differentiates the statutory cap between second-tier financial institutions and cash loan companies."
There are also calls for measures to ease the burden of funding costs. Rep. Kang Jun-hyun of the ruling Democratic Party of Korea said at a parliamentary audit of the Financial Supervisory Service a day earlier that "funding costs at top-tier lenders are not much different" from those at ordinary lenders, adding that "support to reduce funding interest is needed."