
By PYMNTS | October 16, 2026
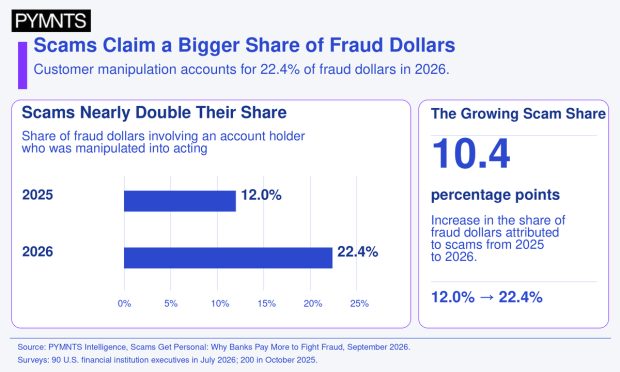
Banks have an opportunity to strengthen fraud prevention by looking more closely at payments that arrive with a valid login or a customer’s approval.
That’s the central implication of the third key finding in “Scams Get Personal: Why Banks Pay More to Fight Fraud,” a PYMNTS Intelligence report in The Fraud Economy series. Based on a July 2026 survey of 90 executives at U.S. banks, credit unions and FinTechs, the report finds that institutions have widely adopted fraud detection tools while criminals increasingly exploit customer trust and stolen credentials.

We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
Scams and compromised credentials together account for 50.6% of fraud dollars, up from 27.6% two years earlier. It’s like installing stronger locks while thieves persuade someone to hand over the keys. The findings point to an opportunity to extend protection beyond verifying access to understanding the circumstances behind a payment.
Three findings show where institutions can focus:
- Scams account for 22.4% of fraud dollars, up from 12% in 2025. That’s a 10.4 percentage point increase in the share involving account holders who were manipulated into acting. Relationship or trust fraud, in which criminals first build personal rapport with victims, more than doubled its share to 12.6% from 6%. These findings highlight the limits of treating customer approval as evidence that a payment is safe. A customer can authorize a transaction without understanding who will receive the money.
- Account takeover through stolen credentials represents 28.2% of fraud dollars. Its share grew 82%, underscoring the challenge of identifying criminals using legitimate account information. Meanwhile, physical forgery and counterfeit fraud fell to 6.1% of fraud dollars. Banks therefore face a changing mix of threats. Recognizing a familiar login is useful, but institutions also need to assess whether the activity fits the customer’s behavior.
- Fraud detection technology has become widespread, creating a foundation for further improvements. All surveyed institutions use tools that analyze behavior, identify devices and verify identity through personal information. Another 96% use machine learning and artificial intelligence. Integrating those systems remains difficult: 78% cite the complexity of new technology systems as their top barrier to innovation, up from 48% a year earlier. Making existing tools work together offers a practical focus for institutions that already have extensive capabilities.
Other findings suggest banks are responding to the human side of fraud. Improved customer communication leads planned investments for the coming year, cited by 78% of institutions, up from 41%. Among institutions using machine learning, 86% say it helps them catch problems proactively, compared with 25% in 2025. Those results suggest banks have useful capabilities to build on as they work to protect customers before money leaves their accounts.
At PYMNTS Intelligence, we work with businesses to uncover insights that fuel intelligent, data-driven discussions on changing customer expectations, a more connected economy and the strategic shifts necessary to achieve outcomes. With rigorous research methodologies and unwavering commitment to objective quality, we offer trusted data to grow your business. As our partner, you’ll have access to our diverse team of PhDs, researchers, data analysts, number crunchers, subject matter veterans and editorial experts.