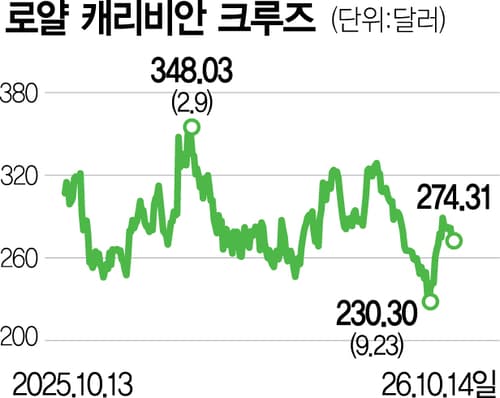
Royal Caribbean Cruises is broadening its growth engines with new ships and land-based resorts. Profitability stalled in the second quarter on higher fuel and labor costs, but the company has guided for third-quarter capacity to rise 8.5% from a year earlier and for net cruise costs excluding fuel per available passenger cruise day to fall 1.2% to 1.7%, pointing to top-line growth and cost improvement working together in the second half.
The New York-listed company operates the casual Royal Caribbean brand, premium Celebrity Cruises and luxury Silversea. It also holds a 50% stake in Germany's TUI Cruises. About 70% of revenue comes from passenger tickets and 30% from onboard spending. Because lodging, food and beverage, shows and shore excursions are sold together, adding ships feeds through to both ticket sales and onboard spending.
New ships are the key variable for the second half. Legend of the Seas, the third vessel in the Icon class, was delivered in June and began sailing Mediterranean and Caribbean itineraries in July. The company plans to deploy Quantum of the Seas in Singapore from October 2027 through March 2028 to target the Asian market. Celebrity Cruises will enter the European river cruise business starting in 2027.
The expansion extends onto land. In September, the company agreed to acquire a 50% stake in Sandals and Beach Resorts for about $3 billion. The debt-funded deal increases its leverage, but once it starts contributing to earnings next year, the company will be able to sell packages that combine cruises with land-based resorts. The strategy expands the business model beyond ship operations into a comprehensive vacation platform.
Booking demand is also solid. In its second-quarter earnings release, the company said bookings for 2027 are running above historical averages. Boosting onboard and shore-excursion spending through advance sales could turn added capacity into higher revenue per guest. The point to watch in the third quarter is whether expanded capacity and lower unit costs translate into actual earnings improvement.
Still, the burden of heavier investment remains. In July, Royal Caribbean lowered its full-year guidance from the start of the year to reflect geopolitical risks on some routes. It kept its growth outlook at around the low double digits but must manage the cost and financial burden tied to new ships and resort investments. The question ahead is whether the added supply can be absorbed by solid booking demand and pricing. If unit cost improvement is also confirmed, expectations for earnings growth next year are likely to rise.
