AFRICA · CRITICAL MINERALS
Key Facts
- —The basics The Democratic Republic of Congo mined about 73% of the world’s cobalt in 2025, and Africa also leads world output of platinum, manganese, chrome, bauxite and tantalum.
- —Why it matters The United States imports all its manganese and graphite and 79% of its cobalt, so export bans and ownership rules set in Kinshasa, Harare and Conakry shape US supply.
- —The numbers Congo caps cobalt exports at 96,600 tonnes a year in 2026 and 2027, against 2025 output of about 230,000 tonnes, and a US-backed group proposed buying 40% of Glencore’s interests in two Congolese mines with a combined value of about US$9 billion.
- —Who is who Félix Tshisekedi is Congo’s president and ARECOMS, the regulator chaired by Patrick Luabeya, sets cobalt quotas; Glencore, China’s CMOC and Rio Tinto are among the biggest foreign miners.
- —What to watch Whether ARECOMS cuts cobalt quotas, whether Glencore signs a binding sale to the US-backed Orion consortium, and what Zimbabwe allows for lithium concentrate after 1 January 2027.
- —Prediction markets Polymarket gives a 5.1% chance that Félix Tshisekedi is out as Congo’s president by 31 December 2026 (16 October, 7:42 a.m. ET).
- —What it means for you Shareholders of Rio Tinto, Sibanye-Stillwater and Ivanhoe Mines carry African policy risk, and US makers of batteries, steel and electronics rely on supplies whose terms African governments now set.
Cobalt, platinum, manganese and bauxite come mostly from African mines. This guide maps Africa’s critical minerals reserves and output, who digs them and who writes the rules.
The Democratic Republic of Congo mined about 73% of the world’s cobalt in 2025, the US Geological Survey (USGS) estimates. Africa also mined about 75% of manganese and 80% of platinum, and Guinea alone dug 34% of bauxite.
African mines produced about 12% of the world’s graphite in 2025, and Namibia and Niger mined about 14% of uranium in 2024. Washington, Beijing, the Gulf states and Europe now compete for these supplies.
African governments, in turn, use export bans, royalties and ownership rules to keep more value at home. This guide anchors The Rio Times dossier on Critical Minerals in Africa.
What Africa Holds
The cards use USGS Mineral Commodity Summaries 2026 estimates for 2025, and World Nuclear Association data for uranium in 2024. Shares are of world mine output unless reserves are named.
Cobalt
Share: Congo 73% of output, 50% of reserves
Use: battery cathodes, jet-engine alloys
Copper
Share: Congo 14%, second after Chile; Zambia 4%
Use: power grids, wiring, motors
Manganese
Share: South Africa 38%, Gabon 25%, Ghana 10%
Use: steel, battery cathodes
Platinum-group metals
Share: South Africa 71% of platinum, 37% of palladium, most reserves
Use: catalytic converters
Chrome
Share: South Africa 45% of chromite
Use: stainless steel
Bauxite
Share: Guinea 34% of output, about 26% of reserves
Use: alumina and aluminium
Iron ore
Share: South Africa and Mauritania about 3%; Guinea’s Simandou ramping up
Use: steel
Lithium
Share: Zimbabwe about 10%, Mali about 3%
Use: batteries
Graphite
Share: Madagascar, Tanzania, Mozambique 12% combined
Use: battery anodes
Rare earths
Share: about 1% (Madagascar, Nigeria); reserves in Tanzania, South Africa
Use: magnets for motors and turbines
Uranium
Share: Namibia 12%, Niger 1.6% (2024)
Use: nuclear fuel
Tantalum
Share: Congo 52%, Africa about 85%
Use: capacitors in phones and defence electronics
China, not Africa, is the world’s leading cobalt refiner, the USGS notes, even though Congo mines most of the ore. The International Energy Agency (IEA) puts the top refining country’s average share across key minerals, excluding rare earths, at 72% in 2025.

DR Congo: Cobalt and Copper
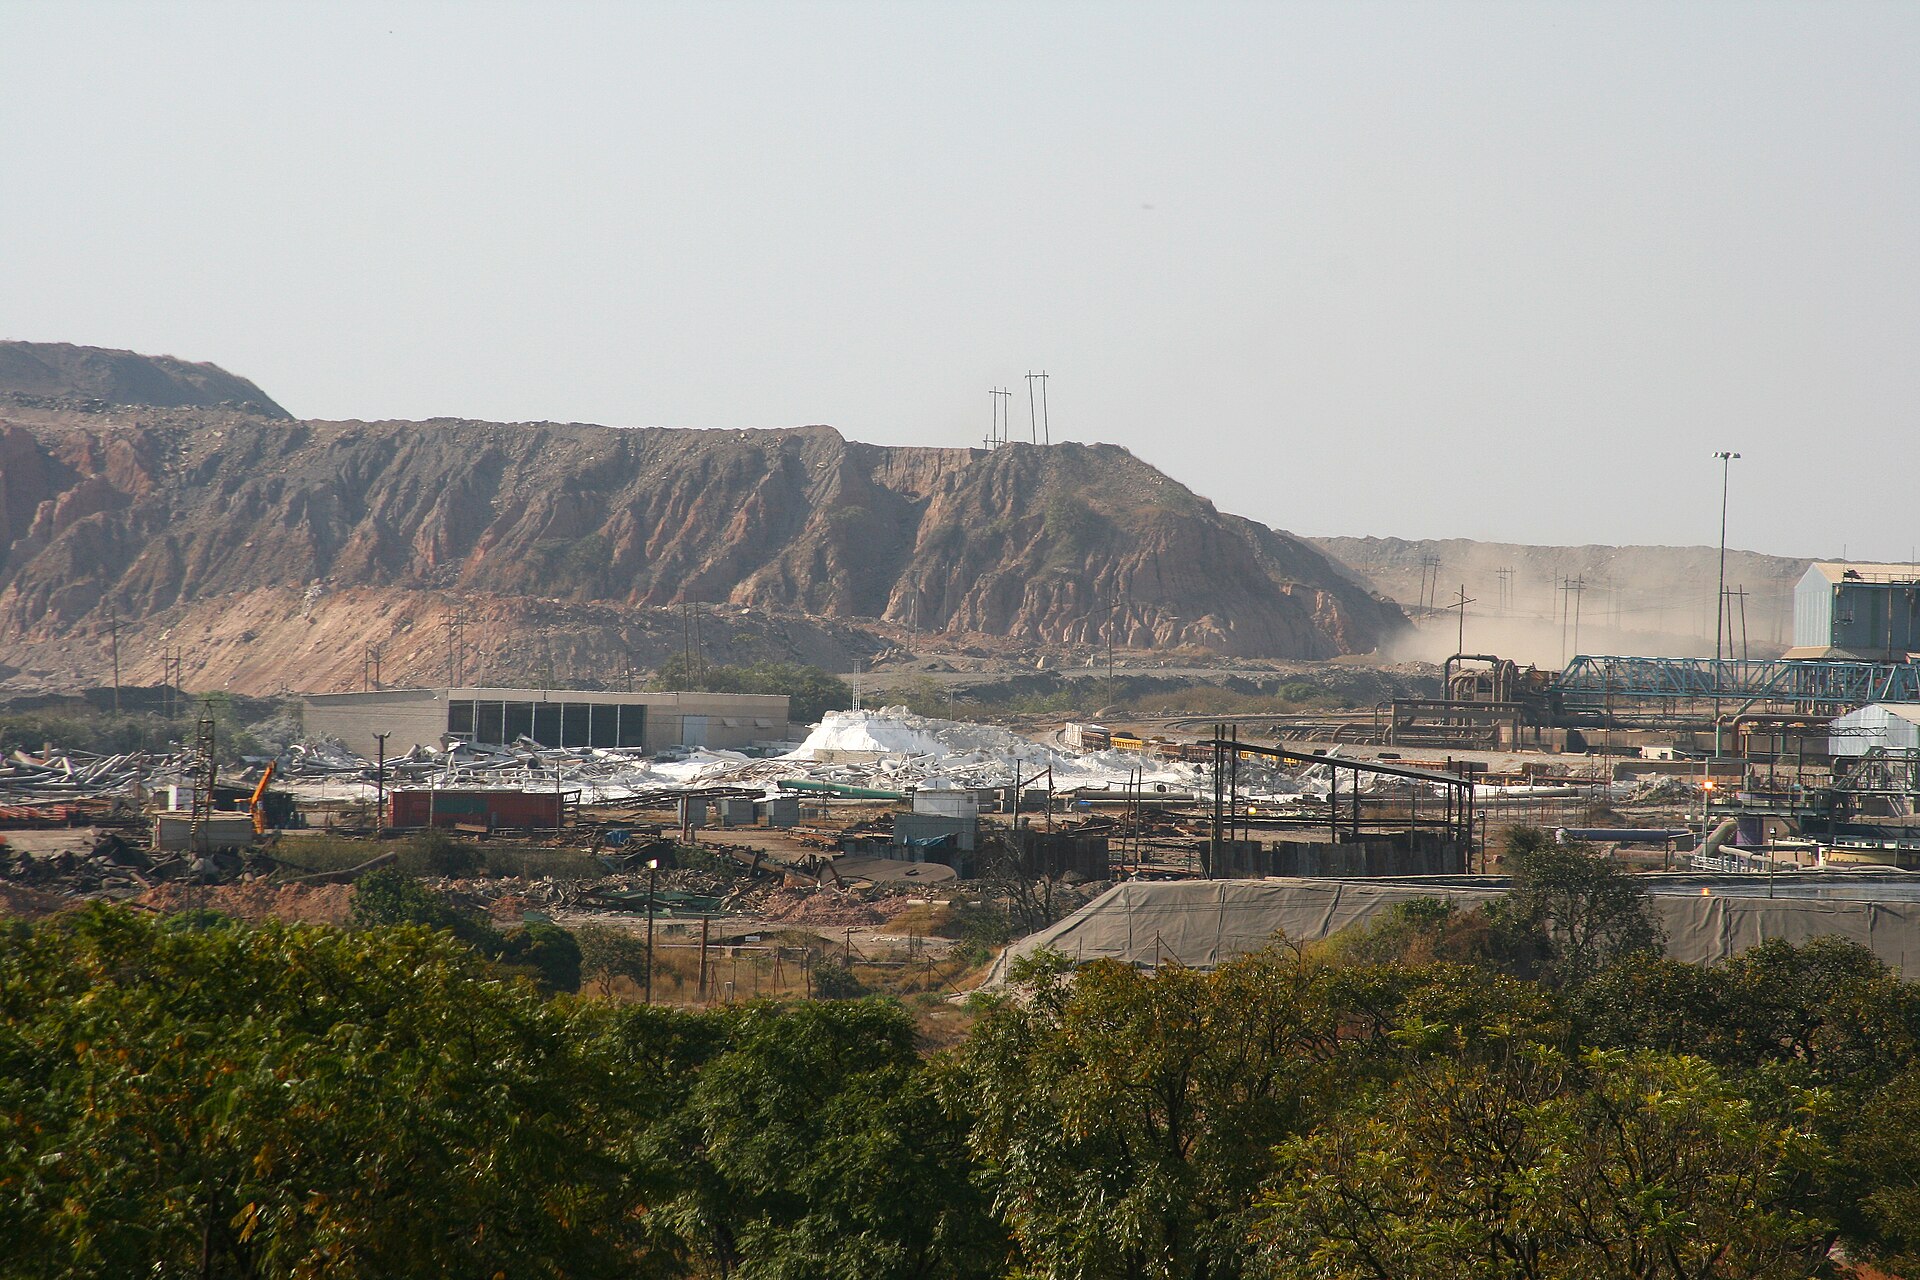
Congo’s copper and cobalt come from the Katanga belt around Kolwezi and Lubumbashi, in the far southeast. The country mined about 3.2 million tonnes of copper in 2025, second only to Chile.
Two groups dominate cobalt: Glencore, the Swiss-based commodities giant, and China’s CMOC, which reported 117,549 tonnes of cobalt output in 2025. Gécamines, the state miner, holds minority stakes, including 25% of Glencore’s Kamoto Copper Company.
Kinshasa banned cobalt exports in February 2025 to address oversupply and low prices, the USGS says. In October 2025, ARECOMS, the strategic-minerals market regulator, replaced the ban with quotas.
The cap is 96,600 tonnes of contained cobalt a year in 2026 and 2027, including 9,600 tonnes for a state reserve. In August its chairman, Patrick Luabeya, told Fastmarkets that a cut “may be considered” if the market imbalance persists.
An interministerial order of Monday, 29 June 2026, made public in August, banned exports of copper and cobalt concentrates. Mines Minister Louis Watum Kabamba may grant one-year derogations, Congolese outlet DosEco reported.
The 2018 mining code also requires Congolese nationals to hold at least 10% of every mining company with an exploitation permit. How that Congolese ownership rule will be enforced is not yet settled.
ARSP, which polices a 2017 law reserving subcontracts for majority-Congolese firms, has ordered several big miners to drop ineligible suppliers. In the east, the M23 rebels, whom UN experts say Rwanda backs, seized Goma and Bukavu in early 2025.
On Thursday, 4 December 2025, Washington and Kinshasa signed a Strategic Partnership Agreement giving US persons first offer on reserved mineral projects. On 3 February 2026, Glencore agreed non-binding terms to sell 40% of its Kamoto and Mutanda interests to the US-backed Orion consortium.
That memorandum implies an enterprise value of about US$9 billion but needs due diligence and binding documents. The DR Congo explainer covers the war and President Félix Tshisekedi’s politics.
Zambia and the Lobito Corridor
Zambia mined 890,346 tonnes of copper in 2025, mines ministry figures show, and targets 3 million tonnes by 2031. President Hakainde Hichilema won a second term in August 2026, as the Zambia explainer details.
The state invests through ZCCM-IH, which sold 51% of Mopani Copper Mines to Abu Dhabi’s International Resources Holding in 2024. Vedanta’s Konkola Copper Mines restarted its Nchanga smelter on 21 September 2026 after a 106-day shutdown.
While smelters were offline, Zambia waived its 10% export duty on copper concentrate, a waiver that ended on 30 September 2026. The Lobito Corridor, backed by Washington and Brussels, links the copper belts by rail to Angola’s Atlantic coast.
The older TAZARA line runs east to Dar es Salaam in Tanzania. On 29 September 2025, China’s state-owned CCECC signed a 30-year, US$1.4 billion concession to rebuild and run it.
Guinea, Niger and West Africa
Guinea dug 34% of the world’s bauxite in 2025 and revoked a UAE-owned producer’s licences that August over a refinery dispute. President Mamadi Doumbouya, who led the 2021 coup, won the December 2025 election, as the Guinea explainer details.
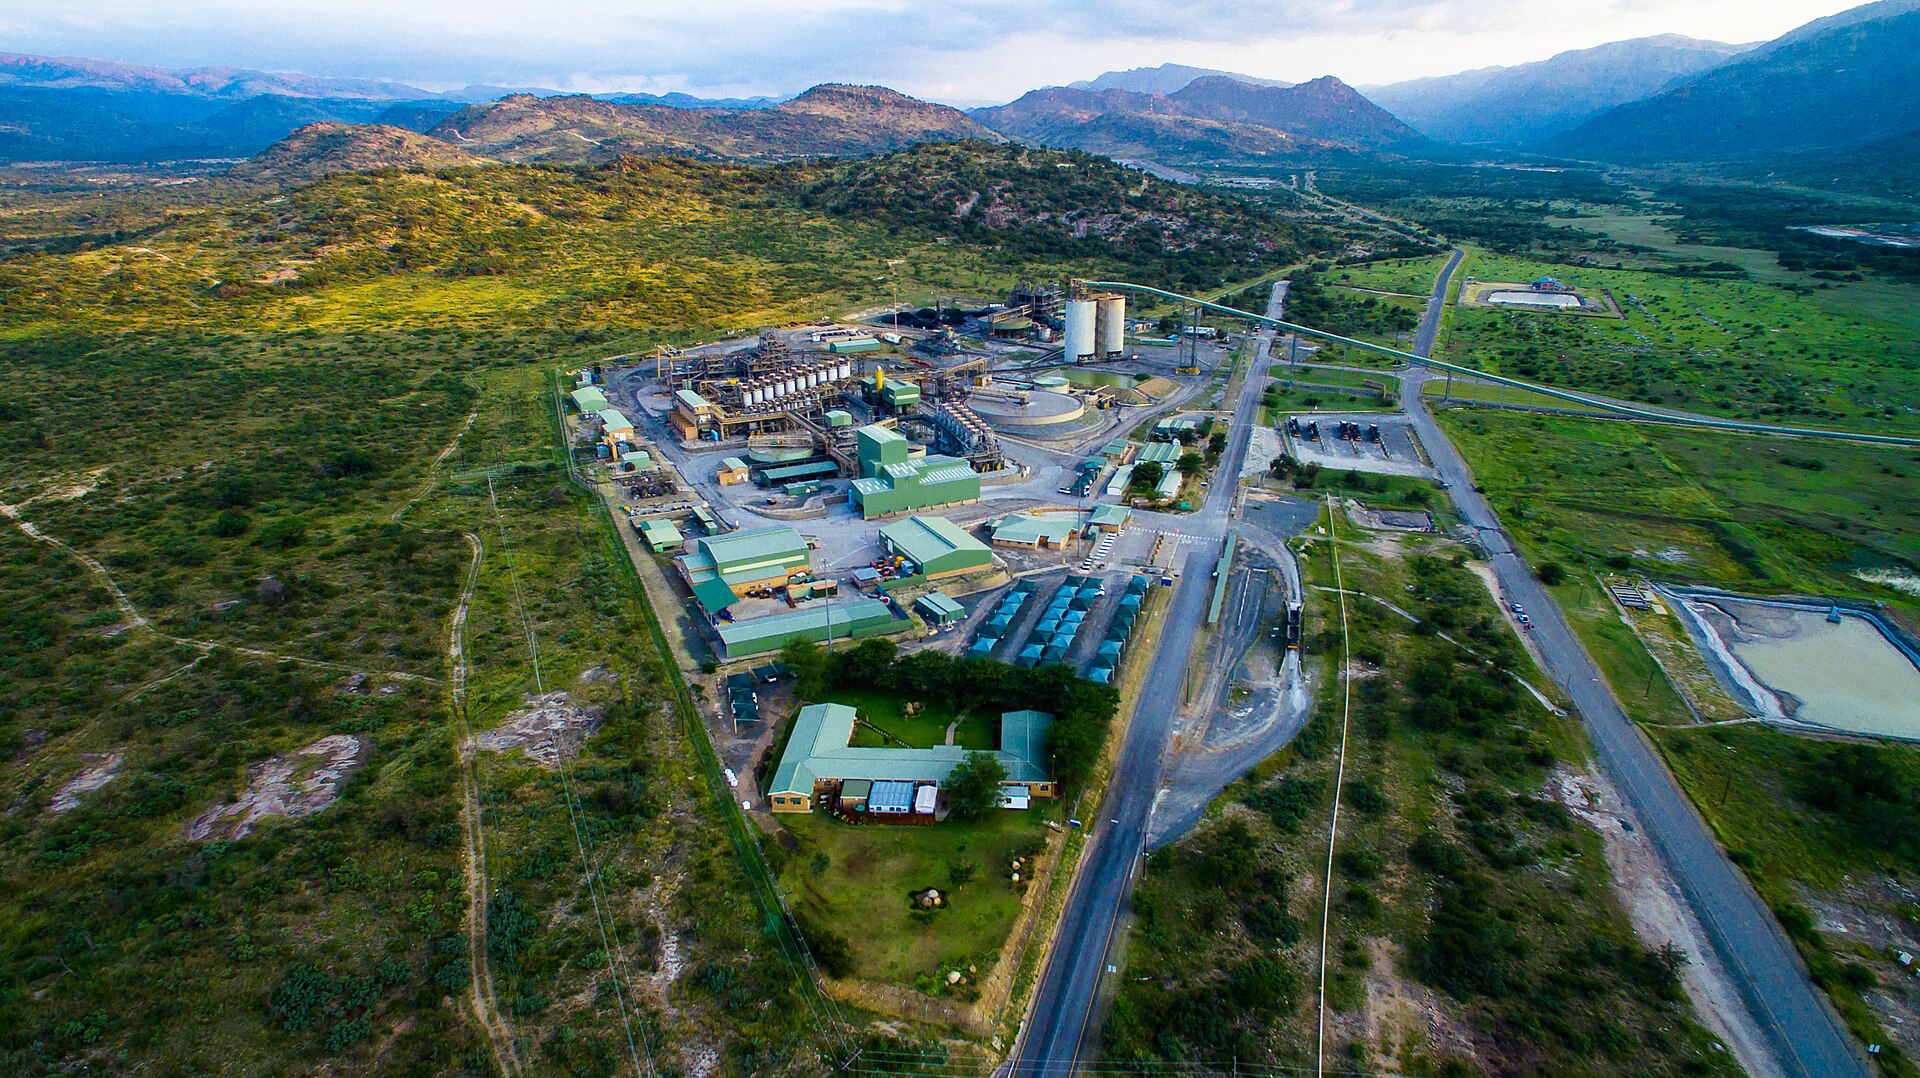
Simandou, a high-grade iron ore project in Guinea’s southeast, started production in late 2025. Rio Tinto said its SimFer venture hit an annualised rate of about 10 million tonnes in the third quarter of 2026.
Rio Tinto targets a 60-million-tonne annual run-rate for SimFer in the second half of 2028. SimFer’s port at Morebaya and its mine were both more than three-quarters built by July 2026.
Niger nationalised the Somaïr uranium mine in June 2025, stripping France’s Orano of its 63.4% stake. A tribunal at ICSID, the World Bank’s arbitration body, ordered Niger in September 2025 not to sell Somaïr uranium.
General Abdourahamane Tiani’s junta now signs deals with bigger state stakes, as the Niger explainer shows. On 16 September 2026, Global Atomic said the US International Development Finance Corporation (DFC) conditionally approved up to US$414.2 million for Dasa.
Mali, ruled by General Assimi Goïta, lifted lithium output to 9,400 tonnes in 2025 from two mines opened in 2024. Its 2023 mining code gives the state larger stakes, which led to a long dispute with Barrick, the Canadian gold miner.
Lithium, Graphite and Rare Earths
Zimbabwe, Africa’s largest lithium producer, has banned raw lithium ore exports since December 2022. In late February 2026 it also suspended lithium concentrate exports, then moved to quotas in April.
Mines Minister Polite Kambamura said only large-scale producers received quotas, Mining Zimbabwe reported, and five of the six are Chinese-owned. Conditions include plans for lithium sulphate plants before 1 January 2027, as the Zimbabwe export halt report explains.
Tanzania more than doubled graphite output to 75,000 tonnes in 2025, the USGS estimates. Mozambique’s Balama mine, owned by Australia’s Syrah Resources, supplies Syrah’s anode plant in Vidalia, Louisiana.
Kenya opened a tender for the Mrima Hill rare earth and niobium deposit by gazette notice on 27 March 2026. Nasdaq-listed Critical Metals Corp said on 21 July that its consortium was one of three finalists.
The Mrima Hill tender has no announced award date. In South Africa, London-listed Rainbow Rare Earths is developing Phalaborwa, which recovers rare earths from old phosphogypsum stacks.
South Africa and Southern Africa
South Africa supplied 49% of US platinum imports from 2021 to 2024, the USGS says. Its Department of Mineral and Petroleum Resources (DMPR) issues mining rights and enforces the Mining Charter.
The 2018 charter requires new rights holders to have at least 30% Black ownership. Royalties under the 2008 royalty act are capped at 5% of gross sales for refined minerals and 7% for unrefined ones.
Zimbabwe mines about 11% of world platinum, mostly through Impala Platinum’s Zimplats and Valterra Platinum’s Unki. Namibia banned exports of unprocessed lithium and other critical-mineral ores in June 2023.
The Companies
Listings and stakes come from the latest annual reports and filings. Stakes are each company’s share of the named asset.
Glencore
Ticker: LSE: GLEN
Assets: Kamoto Copper Company (70%), Mutanda, Congo
CMOC
Ticker: 603993 (Shanghai), 3993 (Hong Kong)
Assets: Tenke Fungurume (80%), Kisanfu (71.25%), Congo
Gécamines
Owner: Congolese state
Assets: minority stakes, including 25% of Kamoto Copper Company
ZCCM-IH
Owner: Zambian government (controlling stake)
Assets: 49% of Mopani, 20.6% of Konkola, 20% of Kansanshi
Ivanhoe Mines
Ticker: TSX: IVN
Assets: Kamoa-Kakula (39.6%), Kipushi, Congo; Platreef, South Africa
First Quantum Minerals
Ticker: TSX: FM
Assets: Kansanshi (80%), Sentinel, Zambia
Sibanye-Stillwater
Ticker: JSE: SSW, NYSE: SBSW
Assets: platinum mines at Rustenburg and Marikana, South Africa
Impala Platinum
Ticker: JSE: IMP
Assets: Impala Rustenburg, South Africa; Zimplats (87%), Zimbabwe
Valterra Platinum
Ticker: JSE: VAL, LSE: VALT
Assets: Mogalakwena, Amandelbult, South Africa; Unki, Zimbabwe
Rio Tinto
Ticker: NYSE: RIO
Assets: 45.05% effective interest in SimFer (Simandou), Guinea
Orano
Owner: majority-owned by the French state
Assets: lost 63.4% of Somaïr, Niger, to nationalisation in 2025
KoBold Metals
Owner: private, backed by Breakthrough Energy Ventures
Assets: Mingomba copper, Zambia; lithium permits near Manono, Congo
Rainbow Rare Earths
Ticker: LSE: RBW
Assets: Phalaborwa rare earths project, South Africa
China, the United States, the EU and the Gulf
Chinese firms own much of Congo’s output, from CMOC’s two mines to Zijin Mining’s 39.6% of Kamoa-Kakula. In December 2025 the DFC signed a US$553 million loan for the Lobito Atlantic Railway in Angola, Mining Weekly reported.
The EU backs the corridor through Global Gateway, with nine member states involved. The Lobito and TAZARA rivalry now shapes where Zambian and Congolese copper goes.
Abu Dhabi’s International Resources Holding has controlled Mopani since 2024, and Russia’s Rosatom signed a nuclear memorandum with Niger in July 2025. For the full map of outside powers, see the Great Powers in Africa dossier.
Policy Fights
Congo uses quotas and a concentrate ban, Zimbabwe uses quotas and a processing deadline, and Namibia bans raw lithium ore exports. Ownership rules add a second layer, from Congo’s 10% local stake to South Africa’s 30% Black ownership rule.
ARECOMS can withdraw quotas from firms processing unauthorised artisanal ore, and UN experts tie eastern smuggling to the M23 war. Most measures rest on decrees and ministerial orders, so they can change quickly.
Prices and Outlook
Cobalt prices rose by around 130%, largely because of Congo’s restrictions, the IEA’s Global Critical Minerals Outlook 2026 says. The USGS put the US spot cathode price at about US$21 a pound in 2025, up from US$16.77.
The COMEX copper price was expected to average a record US$4.80 a pound in 2025, the USGS said. The IEA projects a 25% copper supply gap by 2035, down from the 30% it forecast a year earlier.
US contract lithium carbonate prices fell 31% to US$9,000 a tonne in 2025, and lithium companies cut investment by around 40%. Buyers can also turn to South America, as the dossier on Lithium in Latin America explains.
What the Markets Say
Polymarket gave a 5.1% chance that Félix Tshisekedi is out as Congo’s president by 31 December 2026. The price was read on 16 October 2026 at 7:42 a.m. ET, with about US$21,400 traded.
No Polymarket market on cobalt, lithium or other African minerals was trading when checked. The low price suggests traders expect Kinshasa’s leadership, and so its minerals policy, to stay in place this year.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
What It Means for US Readers
The United States relied on imports for 79% of its cobalt and all its manganese and graphite in 2025. Gabon and South Africa supplied 88% of US manganese ore imports from 2021 to 2024, USGS data show.
Washington’s tools are DFC loans, Export-Import Bank (EXIM) credit and the Congo partnership, with Lobito and Dasa as DFC cases. US-listed exposure runs through Rio Tinto, Sibanye-Stillwater and Nasdaq-listed Critical Metals.
A 50% Section 232 tariff on semi-finished copper products took effect on 1 August 2025, but refined copper was left out. The US Treasury has also sanctioned figures tied to the M23 conflict in eastern Congo.
This guide anchors the Critical Minerals in Africa hub, one of the Rio Times dossiers. For the wider contest, see Africa: The New Scramble.
Companion guides cover lithium in Latin America and copper in Latin America, the two markets that compete with Africa. A fourth, who backs whom in Africa, maps the outside powers behind each government.
What Is Not Known
It is not known whether ARECOMS will cut cobalt quotas or whether Glencore and Orion will sign binding documents. Zimbabwe has not said whether lithium concentrate exports will be banned outright after 1 January 2027.
No final ICSID award in Orano’s case against Niger has been published. Current DMPR figures on South Africa’s mining-tax take could not be verified for this guide.
Frequently Asked Questions
Which African country has the most cobalt?
The Democratic Republic of Congo holds about 6 million tonnes, half of world cobalt reserves, USGS estimates show. It mined about 230,000 tonnes in 2025, roughly 73% of global output.
Why does Congo restrict cobalt exports?
Kinshasa wants to lift prices hit by oversupply and to push more processing inside the country. It banned exports in February 2025 and has capped them with ARECOMS quotas since October 2025.
Which critical minerals come from Africa?
Africa leads world output of cobalt, platinum, manganese, chrome and tantalum, and Guinea is the top bauxite producer. It also mines significant copper, graphite, lithium and uranium.
Who controls Congo’s cobalt mines?
China’s CMOC and Glencore run the largest mines, with state miner Gécamines as a minority partner. A US-backed consortium, Orion CMC, agreed in principle in February 2026 to buy 40% of Glencore’s interests in its two Congolese mines.
Sources: USGS Mineral Commodity Summaries 2026: cobalt; copper; manganese; platinum-group metals; chromium; bauxite; iron ore; lithium; graphite; rare earths; tantalum; IEA Global Critical Minerals Outlook 2026, executive summary; World Nuclear Association, uranium production 2024; US State Department, US-DRC Strategic Partnership Agreement; Orion CMC and Glencore release, 3 February 2026; Kamoto Copper Company, ownership; Miningmx, Gécamines and state stakes in KCC; CMOC 2025 annual report; Fastmarkets, ARECOMS interview; DosEco, concentrate export ban; Leganews, interministerial order of 29 June 2026; Benin Web TV, ARSP order; ACP, ARSP order to SICOMINES; Ecomatin, concentrate export ban; Fastmarkets, Zambia duty waiver and Nchanga; Fastmarkets, end of the duty waiver; Benin Web TV, Nchanga restart; Ecofin Agency, Zambia 2025 copper output; ZCCM-IH, Mopani completion; First Quantum 2025 annual report; AllAfrica, Hichilema sworn in; China Global South Project, TAZARA concession; The Citizen (Tanzania), TAZARA concession; EWN, Guinea election result; Rio Tinto third-quarter 2026 production results (SEC 6-K); Rio Tinto second-quarter 2026 production results (SEC 6-K); Rio Tinto 2025 Form 20-F; Ecofin Agency, Niger and Orano; Global Atomic, DFC approval; Mining Zimbabwe, lithium export quotas; New Zimbabwe via AllAfrica, lithium quota review; Critical Metals Corp, Mrima Hill release; The Brief (Namibia), export ban; Anglo American, Valterra demerger; Mining Weekly, Lobito loan; European Commission, Lobito Corridor; White House, Section 232 copper proclamation; Federal Register, OFAC designations; Congo Mining Network, ARECOMS quota powers; UN Group of Experts on the DRC, final report, July 2025; World Nuclear News, ICSID order on Somair; Orano, ICSID decision; IEA policy database, Zimbabwe lithium ore export control; Kenyans.co.ke, Mrima Hill tender; Bankable, KoBold permits; Ecofin, KoBold permits; Rainbow Rare Earths, Phalaborwa; Syrah Resources; Ivanhoe Mines; Implats fact sheet; Mineral and Petroleum Resources Royalty Act, section 4; SAnews, Mining Charter 2018 (all accessed 15 October 2026).