India’s payments ecosystem has shown that financial infrastructure can operate at enormous scale. But as fintech companies expand into cross-border business payments and adopt AI, they face a different set of challenges.
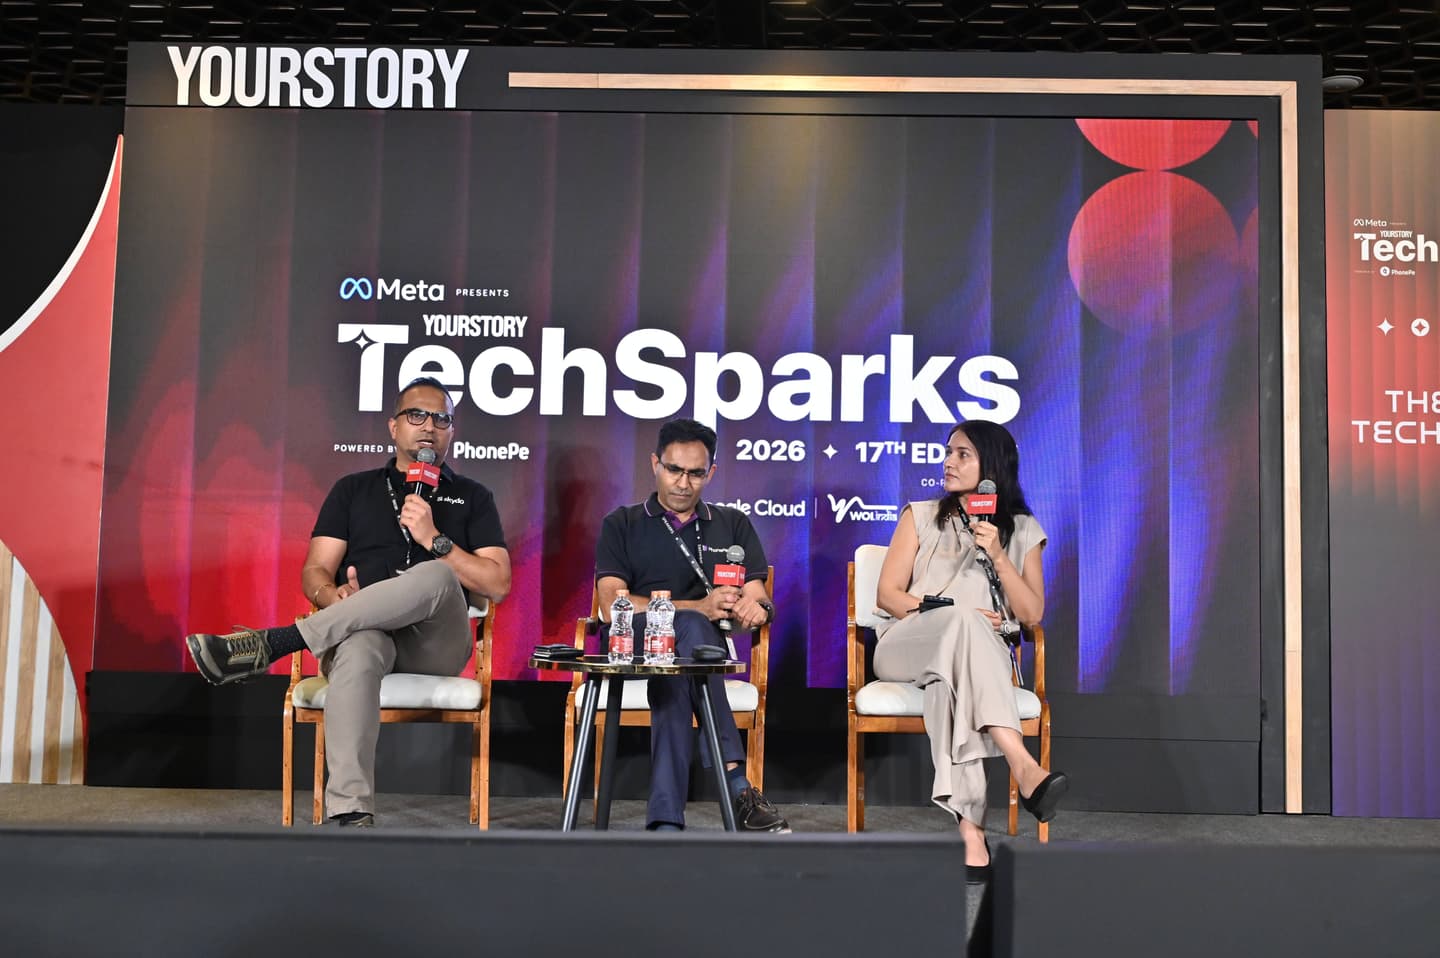
At TechSparks 2026, Movin Jain, Founder of Skydo, and Srijon Biswas, Chief Technology Officer at PhonePe, discussed the technology behind large-scale payments, the need for transparency in cross-border transactions, and the opportunities emerging from AI.
The panel, titled ‘From domestic scale to global rails: The evolution of India's fintech infrastructure’, was moderated by Priya Patankar, Head of Corporate Communications at PhonePe.
Cross-border payments: A market still in its early stages
Jain believes cross-border payments offer considerable opportunities because fintech adoption remains relatively low.
India exports goods and services worth approximately $850 billion annually and imports around $1 trillion worth, with both figures growing. However, less than 10% of these transactions are handled by fintech companies, according to Jain. Banks continue to manage most of these payments.
Skydo focuses on business-to-business (B2B) payments, where fintech adoption is even lower than in consumer payments. Many businesses are still learning that fintech companies can help them manage cross-border transactions.
Jain believes the immediate opportunity lies in building awareness of the category rather than competing on price.
“Spending time worrying about other fintech players and how to compete with them is not a good use of time. That time will come maybe 5–10 years down the line when all of us have a lot more penetration in the market,” he said.
For now, the priority is to show businesses how fintech companies can address payment problems they have traditionally relied on banks to solve.
While venture capital activity and regulatory developments have helped the sector progress, Jain believes there is considerable room for growth.
Building technology that can scale
PhonePe’s experience shows the importance of making the right architectural decisions early.
Biswas said the company planned for scale from the beginning. Its early architects established systems and engineering practices that continued to serve the platform as it grew by nearly 100-1,000X.
“It's the same pattern that we have used, same set of libraries, same set of constructs that we have used. So it’s been ingrained from the very beginning. We haven’t actually done a large refactor of our architecture for the longest that I can remember,” he said.
Rather than undertake a major architectural overhaul, PhonePe has focused on understanding its technology stack and making deliberate choices about the systems it uses.
The company built its own site reliability engineering (SRE) team, adopted a sharded database architecture from the outset, and chose technologies that its engineers understood well.
Biswas also emphasized the importance of engineering hygiene, instrumentation, testing, quality assurance, and scale testing.
At PhonePe’s scale, even unlikely failures can become operational problems. Biswas recalled encountering bugs that had surfaced at another organization years earlier.
Building for scale, he said, requires more than increasing capacity. It also depends on sound architecture, careful technology choices, and the ability to understand and manage systems under demanding conditions.
Managing India's scale and diversity
Biswas said regulation is not necessarily a constraint for fintech companies. It can encourage businesses to establish the right practices from the beginning.
The bigger engineering challenge, he explained, comes from India's combination of scale and diversity.
He compared India's scale with China’s, while pointing out that differences across geographies, use cases, and merchant environments create additional complexity.
PhonePe encountered this during its early expansion into offline payments.
While integrating with merchants, including pharmacy chains such as Apollo Pharmacy, the company found that different systems were already in use across states and cities.
Supporting these merchants meant building integrations for multiple systems rather than relying on a single standardized setup.
These differences create numerous exceptions and edge cases that must be managed alongside high transaction volumes.
Patankar also noted that PhonePe had received its UAE licence, bringing new opportunities and challenges.
Biswas said the company would need to adapt its infrastructure for international markets rather than simply replicate its Indian operations.
Much of PhonePe’s existing payments architecture has been designed specifically for India. The company is now exploring additional layers of abstraction that could make international expansion easier without having to deploy the entire existing stack and build large teams in every new market.
Why transparency matters in cross-border payments
For businesses receiving payments from overseas clients, speed and cost are not the only concerns.
Jain believes transparency is equally important.
Small businesses, freelancers, and service providers may know how many dollars a client has transferred and how many rupees eventually reach their accounts. However, they may not understand the exchange rate used, the foreign exchange charges, or how the final amount was calculated.
Without this information, businesses may find it difficult to question charges or compare payment providers.
Jain said Skydo is working to educate customers about these costs and help them understand where savings are possible.
He gave the example of a business receiving a $5,000 payment from an international client.
In a transparent system, the business would know as soon as the client makes the payment how many rupees it can expect to receive and when the money is likely to arrive.
It would also be able to see the prevailing exchange rate, understand how the final amount was calculated, and know the applicable GST.
How AI could change business operations
The discussion also covered AI’s growing role in fintech and its potential impact on businesses.
Jain said Skydo works with service businesses ranging from legal and consulting firms to IT services companies and freelancers.
He believes AI agents and automation could allow smaller firms to provide services that previously required the resources of much larger organizations.
This could create opportunities for smaller, specialized businesses and freelancers to earn more than was previously possible, particularly in India.
At PhonePe, Biswas described AI adoption across three areas: user-facing experiences, developer productivity, and operational efficiency.
In the PhonePe app, users can search and ask questions about their transactions using a model running at the edge.
AI is also being used in operational workflows to interpret regulatory and compliance documents. It helps teams understand what regulatory changes mean for the business without having to manually process every document.
Developer productivity is another area where PhonePe has seen improvements.
Biswas said AI-assisted coding has reduced some processes that previously took three to five days to around 15 minutes.
Test-case generation has become 5-6X faster in certain cases, while some customer experience and support workflows have also recorded savings of 5-6X.
However, Biswas emphasized that automation does not eliminate the need for human oversight.
In a regulated business, workflows that could affect users, systems, or processes will continue to require a human in the loop.
Taking India’s payments infrastructure global
India already has several foundational elements in place, including payments infrastructure and systems related to identity and consent.
Biswas believes these provide an advantage as the fintech sector evolves.
However, cross-border payments remain structurally complex.
There is no single central counterparty connecting all central banks and currencies through a unified ledgering system. Businesses must therefore navigate a fragmented payments infrastructure, creating problems that fintech companies are trying to solve.
For India’s fintech sector, the next challenge is to build on the strengths of its domestic infrastructure while adapting to international markets.
That will involve making cross-border payments more transparent, managing the complexity of different markets, and using AI to improve business productivity.