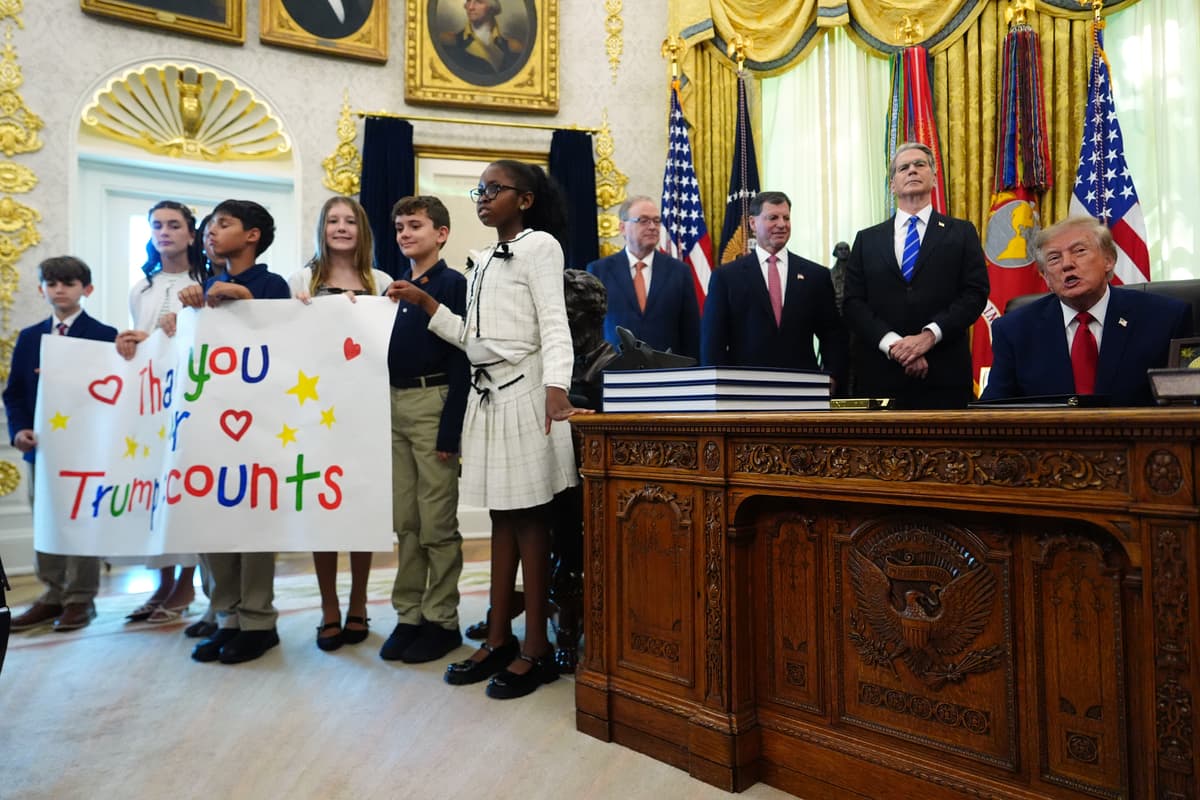
Tesla Chief Executive Elon Musk announced in a surprise move that he will give one SpaceX share each to children in the United States starting next year. The shares are expected to be distributed through the Trump Accounts program championed by U.S. President Donald Trump. Under the program, the federal government provides newborns with $1,000 in seed money to help build long-term assets. In a post on Truth Social, Trump thanked Musk, calling him a "legendary friend."
Launched in July, Trump Accounts have drawn a string of large donations. Susan and Michael Dell pledged $6.25 billion for 25 million children aged 10 and under who were excluded from the initial government funding. The pledge works out to $250 per account and targets children living in areas with median incomes below $150,000. Ray Dalio, founder of Bridgewater Associates, said he would donate $250 each to about 300,000 children in Connecticut.
Parents, however, are not claiming the accounts. Of the 70 million accounts created since the program took effect, 60 million were opened by the U.S. Treasury Department, Bloomberg reported on the 21st. Families and donors opened 10 million accounts, and fewer than 1% of those have actually been claimed by parents.
$1,000 Seed Grows to $87,000 by Age 65, but Skews to the Wealthy and Is Locked Until 18

The basic idea behind Trump Accounts is that parents, relatives and even employers add money to a child's account over time, allowing the child to reap the benefits of compounding over decades. The federal government provides $1,000 in initial funding for children born between Jan. 1, 2025, and Dec. 31, 2028. The account functions essentially as an individual retirement account (IRA) for children. Eligible contributors, including parents and grandparents, can put in a combined maximum of $5,000 per child each year, with the cap expected to be adjusted annually for inflation starting next year. The child must be a U.S. citizen, and only one account is allowed per person.
Withdrawals are permitted starting Jan. 1 of the year the child turns 18. At that point, the account automatically converts to an IRA, and funds can be used penalty-free for certain purposes, including higher education costs or up to $10,000 toward a first home purchase. Income tax is still owed on earnings or pretax contributions when they are withdrawn. Withdrawals for non-qualifying purposes also incur the 10% early withdrawal penalty that applies to IRAs. Under the program's rules, account money must be invested in mutual funds or exchange-traded funds (ETFs) that primarily hold U.S. stocks. Parents serve as custodians, the funds cannot use leverage, and fees cannot exceed 0.1% of the invested balance.
Assuming a 7% annual return, the initial $1,000 grows to about $3,600 by age 18 and about $87,000 by age 65. With an additional $5,000 contributed each year, the balance reaches about $198,000 by age 18 and more than $4.7 million by age 65. Financial experts note that existing options such as 529 plans or custodial brokerage accounts may be better than these accounts. The 529 plans have far higher contribution limits and allow withdrawals before age 18.
As a result, criticism that the program is ineffective is mounting. Critics say the administration is pressuring companies to donate to fund the accounts and call the program populism ahead of the midterm elections. There are also concerns that the tax benefits are concentrated among high earners and that the accounts could end up serving as a vehicle for passing on wealth. Families able to contribute thousands of dollars more each year stand to gain the most, which critics warn would widen the wealth gap. A report by the McKinsey Institute for Economic Mobility said tax-advantaged accounts "may largely benefit wealthier households with money to spare," adding that boosting economic mobility requires broader and more even participation across income levels.

※ Subscribe to [Park Si-jin's Global Pick] for the fastest updates on global trends.