…FG targets 7% growth, sees faster expansion than IMF forecast
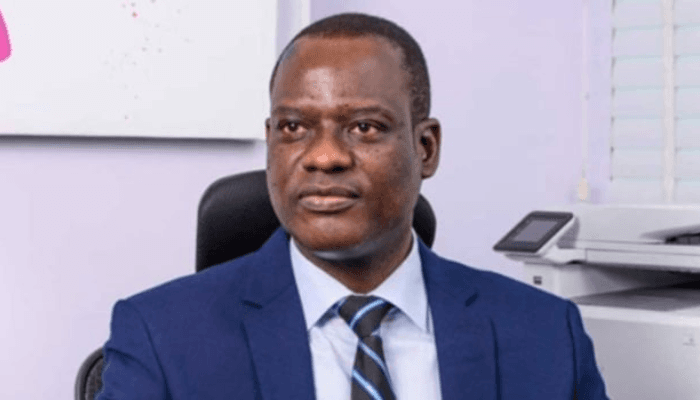
Nigeria has ruled out a return to fuel subsidies and multiple exchange rates, with Finance Minister Taiwo Oyedele insisting that the government will not reverse the policies despite rising petrol prices and mounting pressure on households and businesses.
Oyedele gave the assurance at the Nigerian delegation’s closing press briefing to mark the end of the 2026 Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group in Bangkok, Thailand, on Saturday.
“Let me be clear: there will be no return to fuel subsidies or multiple exchange rates,” the minister said.
He was responding to concerns over the rising cost of living and renewed debate about the possibility of restoring fuel subsidies ahead of Nigeria’s 2027 general elections.
The minister also clarified that the recent petrol discount at Nigerian National Petroleum Company Limited (NNPC) retail outlets does not amount to a return to government-funded subsidies.
According to him, the discount is a time-bound commercial decision by NNPC to reduce its retail profit margin and provide temporary relief to Nigerians, rather than a subsidy financed with public funds.
“The recent retail margin discount on fuel is a time-bound commercial decision by the NNPC to reduce margins and support Nigerians; it is not a subsidy paid from public funds,” he said.
The clarification comes amid persistent concerns over the impact of higher petrol prices on transportation, food prices, business operating costs and household purchasing power following the removal of fuel subsidies in 2023.
The government has maintained that restoring broad-based subsidies would place additional pressure on public finances and risk undermining the gains from its economic reforms.
Earlier in October, Oyedele warned that returning petrol prices to their pre-reform levels could cost Nigeria more than N20 trillion annually, arguing that the financial burden would compete with spending on essential public services and development priorities.
He also acknowledged during the annual meetings that the sequencing of fuel subsidy removal and foreign exchange market liberalisation had been fast, recognising the hardship associated with the reforms.
At the closing briefing in Bangkok, however, the minister reiterated that the government would not return to the previous subsidy regime or multiple exchange rates.
The position leaves the government facing the challenge of sustaining market-based pricing while addressing the burden of high energy costs on households and productive businesses.
The IMF has also advised Nigeria against restoring blanket petrol subsidies, recommending targeted assistance to vulnerable households instead. The Fund has argued that broad-based fuel subsidies are fiscally expensive and often disproportionately benefit higher-income consumers.
For the Nigerian government, the challenge now is to ensure that economic reforms deliver more tangible benefits to citizens without reversing policies it considers necessary for long-term fiscal stability.
FG targets 7% growth as Oyedele challenges IMF projections
Beyond ruling out a return to subsidies, Oyedele said the government was targeting economic growth of 7 percent, arguing that Nigeria could expand faster than the IMF’s projections as fiscal reforms complement monetary policy measures.
The minister said the Fund’s growth projections had historically underestimated Nigeria’s eventual performance, adding that the government was developing plans to accelerate expansion across industries from 2027.
“If you look back, even while we were in the middle of reforms, every year the projections of the IMF have always turned out to be too conservative. So this year will not be different,” he said.
“From next year, what we are trying to do is to accelerate growth. We will see that it is cutting across all our industries. And we are not saying it because it is nice to say it. We are saying it because we have a plan.”
Oyedele said the government would complement the work of the monetary authorities with fiscal measures designed to tackle persistent inflationary pressures and improve conditions for businesses.
“We expect growth to be much higher than what the IMF is projecting for Nigeria. Our target is to get to 7 percent growth rate,” he said.
He identified food, energy and logistics costs as key sources of inflationary pressure, saying the government was working to address the constraints to bring inflation down to low single digits.
According to him, lower inflation would create the conditions for interest rates to decline to single-digit levels, potentially reducing borrowing costs and encouraging investment.
“If we are able to tackle inflation to low single digits, not just single digits, low single digits, it will provide the conditions for a single-digit interest rate environment,” Oyedele said.
He illustrated the potential benefits of lower borrowing costs by noting that businesses currently face high lending rates that constrain their capacity to expand.
“Imagine that prime lending is close to 30 percent. Your top businesses are growing at 30 percent, and you are still growing at 4.5 percent. Just imagine what is possible when the borrower is in single digits,” he said.
The minister added that exchange-rate movements were no longer exerting the same inflationary pressure as before, pointing to the naira’s improved performance as one of the developments supporting the government’s economic outlook.
Cardoso backs policy consistency to sustain investor confidence
Central Bank of Nigeria (CBN) Governor Olayemi Cardoso, speaking at the same briefing, said sustaining investor confidence and attracting long-term capital would depend on the government’s willingness to maintain its economic reform course.
Cardoso said Nigeria had made considerable progress in restoring macroeconomic stability and should avoid reversing the difficult measures already implemented.
“I honestly think that the answer to that is a lot easier than it may sound. And I think the answer, quite frankly, is just stay the course,” he said.
“We have come a very long way. We have shown that it can be done and that stability has finally returned to our economy. And, of course, we have to build on that.”
The CBN governor said the government should not undermine the reforms that had helped restore confidence in the economy.
“The last thing we are going to do is play around with all the difficult reforms that we have done. So we will stay the course,” he said.
Cardoso also linked improved exchange-rate stability to better prospects for long-term naira financing, noting that the gap between the official and parallel market exchange rates had narrowed substantially.
“At one point in time, the premium between the official rate and the black market rate was about 60 percent. And today, it’s down to about 3 or 4 percent,” he said.
He said the reduction in exchange-rate uncertainty had strengthened the prospects for attracting long-term domestic capital and made it easier for development finance institutions to channel resources into productive investment.
“The chances of getting long-term naira capital have increased astronomically as a result of the stability that we are finding in markets,” Cardoso said.
He explained that the CBN’s responsibility was to maintain macroeconomic and price stability, while development finance institutions should take a greater role in mobilising resources for development.
“The Central Bank’s responsibility is to ensure stability and to ensure macroeconomic price stability. And in the long term, not just in the short term, but into the long term, bring down inflation and ensure price stability,” he said.
Cardoso’s comments reinforce the government’s position that maintaining the reform framework is essential to sustaining investor confidence, while Oyedele’s growth target highlights the administration’s expectation that fiscal and monetary measures will eventually translate into faster economic expansion.
Related News

Onyinye Nwachukwu is the Abuja Bureau Chief of BusinessDay, overseeing coverage across Abuja and Northern Nigeria. With more than two…

