
A “Godzilla” El Niño could reshape America’s weather-risk map in the coming months, experts say, increasing perils for some homeowners and lowering risks for others.
Meteorologists warn that El Niño, a naturally recurring climate pattern associated with warmer waters in the Pacific, will become “very strong” this fall and winter, according to the National Oceanic and Atmospheric Administration (NOAA).
While “no two El Niños are exactly the same,” experts expect much of the West Coast, especially California, to have a higher chance of heavy precipitation and flooding, Scott Handel, lead meteorologist at NOAA's Climate Prediction Center, told Newsweek.
“Above-average temperatures are more likely across the Upper Midwest and much of the Northern Tier of the U.S. more generally,” Handel said. “The Southeast is more prone to heavy rain, flooding, and severe weather. And the Northern Rockies and northern Cascades tend to experience a reduced snowpack.”
How Does El Niño Affect Homeowners?
El Niño has traditionally lowered the risk of devastating Atlantic hurricanes by creating atmospheric conditions that make it harder for storms to form. This has historically provided some relief to homeowners on the Southeast coast, especially in a vulnerable state like Florida.
But El Niño, as Handel pointed out, is also associated with above-average rainfall across the Southeast and on the West Coast, undermining any benefit made on the Atlantic hurricane front. According to Handel, flooding is the biggest concern linked to a very strong El Niño this fall and winter for both the West Coast and Southeast.
“Heavy rain and flooding could produce mudslides in vulnerable terrain across much of the West Coast and surrounding areas. Increased storminess may produce episodes of high winds along parts of the West Coast,” he said.
“Severe weather risks may be elevated for parts of the Southeast. The East Coast is more prone to coastal storms,” he added. “None of these potential weather events are guaranteed, but homeowners should be prepared for elevated risks of impacts.”
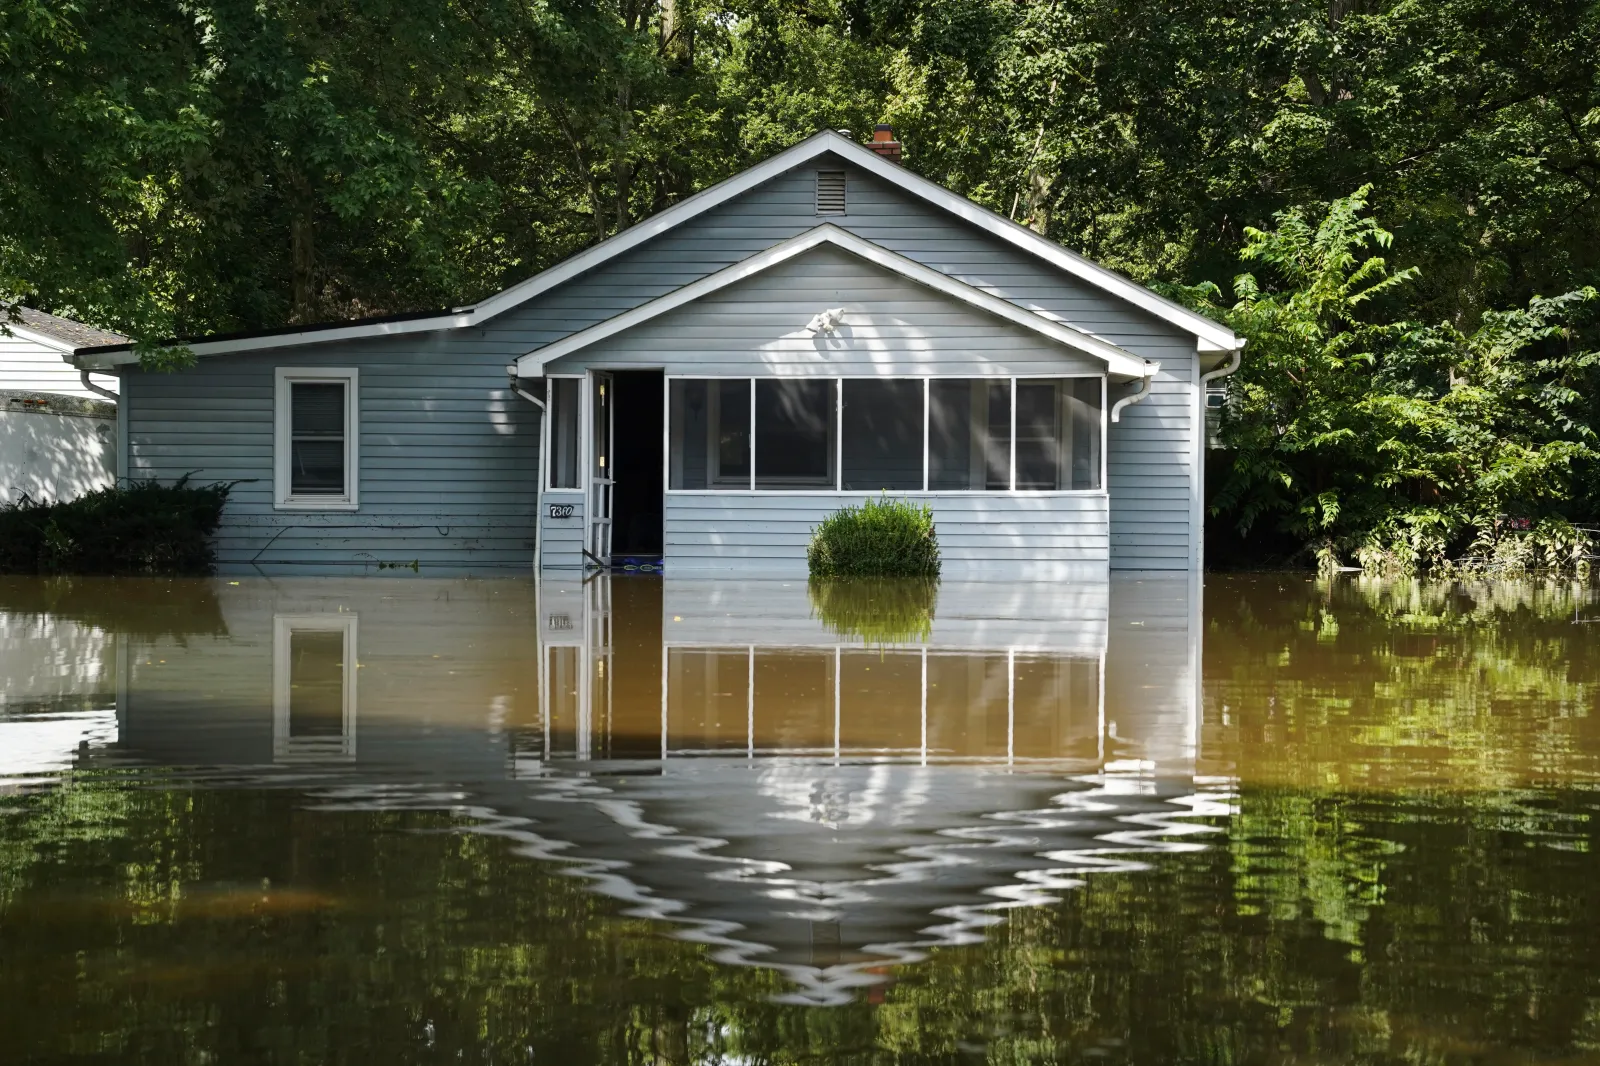
From roof and water damage to burst pipes and debris damage, El Niño can be devastating for homeowners, especially those who are underinsured or lack flood coverage. According to a recent U.S. Government Accountability Office (GAO) report, 86 percent of U.S. properties at high risk of flooding lack flood insurance.
“Most of that flood damage wouldn’t fall on standard homeowners policies. It would fall on the NFIP private flood insurers and homeowners without flood coverage,” Dr. Howard Botts, chief scientist at real estate analytics platform Cotality, told Newsweek.
“Homeowners insurers would still see related claims, such as wind damage and roof leaks from winter storms. Reinsurers have also been paying closer attention to frequent, smaller weather events like floods and severe storms,” he added. “Cotality's 2026 Hurricane Risk Report found that among homes at high risk of hurricane-driven flooding outside mandatory flood insurance areas, rainfall flooding accounts for about 37 percent of expected annual loss.”
...
Experts say some underestimate the risk they face because the Federal Emergency Management Agency’s (FEMA) risk maps do not reflect the current threat accurately; some mistakenly think their standard policy covers flood damage; others simply cannot afford the additional expense.
“FEMA has noted that over the past decade almost one-third of flood insurance claims from the National Flood Insurance Program came from structures outside currently mapped high-risk flood areas. Structures in low-lying areas may be particularly vulnerable,” Denali Pinto, a research data analyst at the Scripps Institution of Oceanography at the University of California, San Diego, told Newsweek.
“To find out your risk, you can search online for ‘what is my flood zone’ and enter your address at FEMA’s Map Service Center," Pinto said.
He added: “It can flood anywhere it rains, not just in high-risk zones. Earth movement and landslide damage, which often accompanies saturated soil in heavy-rain events, is typically covered by a difference-in-conditions policy but may be restricted in high-risk landslide areas like California.
Experts told Newsweek that securing flood insurance through the National Flood Insurance Program (NFIP) or a private carrier was the most important thing homeowners could do ahead of this winter season.
“NFIP coverage normally has a 30-day waiting period, so buying a policy when a major storm appears in the forecast is generally too late,” Tom Corringham, climate economist at Scripps Institution of Oceanography at UC San Diego, told Newsweek.
“For Southern California, where the main flood season is typically in winter—January, February, and March, especially—anyone who thinks they may be exposed should consider the issue well before the peak January to March period.”
NFIP policies are available to renters and homeowners. Renters can buy contents coverage—currently up to $100,000—even though they do not insure the structure itself, Corringham explained.
Homeowners can purchase up to $250,000 in building coverage and $100,000 in contents coverage.
“Importantly, NFIP coverage does not pay for temporary housing or additional living expenses, which is another reason households should understand exactly what their policy does and does not cover,” Corringham said.
Would El Niño Change Homeowners’ Insurance Policies?
This year’s “super” El Niño would not change NFIP policy prices, according to Corringham.
“There is an important distinction here between El Niño changing the probability of a loss this winter and El Niño changing the price of insurance,” he said.
“The effect on potential losses can be strong. The effect on flood insurance premiums is generally much weaker,” he added.
“To my knowledge, NFIP premiums are not repriced each winter according to whether an El Niño or La Niña is occurring,” Corringham said.
Under FEMA’s Risk Rating 2.0 system, rates depend on longer-run characteristics of the property and its flood risk, rebuilding cost, and building characteristics. “Seasonal El Niño conditions are not a household-level rating variable, as far as I know,” Corringham said.
Things may be different in the private sector.
“Private insurers have more flexibility and increasingly use sophisticated catastrophe models and climate information, so seasonal information may matter to pricing, underwriting, and reinsurance decisions,” Corringham said.
“But I would not expect a homeowner’s premium or deductible in Southern California to suddenly rise all that much simply because NOAA predicts an El Niño winter,” he said. “Changes in retail insurance prices generally occur at renewal and reflect a much broader assessment of expected losses.”
In this sense, Corringham said, “a single El Niño is typically a relatively small factor in the long-run price of insurance compared with other major factors. But a single season can still generate very large insured losses, which can subsequently feed into those longer-run market conditions.”
According to a study by Inigo Insurance, many major insurers and reinsurers use forward-looking estimates of weather-related risk that are typically smoothed over at least five years to avoid large year-to-year changes in premiums and modeling. Some, however, adjust those longer-term baselines in response to seasonal hurricane forecasts.
Insurers could pass the cost of catastrophic flooding in part of the country this fall and winter on to policyholders, “though not quickly or all at once,” Botts said.
“Insurers pass higher costs, including reinsurance, through rate filings, and in most states, those increases need regulator review before they take effect. Any increase tied to this winter would mostly show up at 2027 renewals,” he said.
“For flood coverage, the NFIP limits most annual premium increases to 18 percent, so higher flood costs would phase in over time. And after a year of falling reinsurance prices and returning private capacity, the market has some room to absorb a bad winter before homeowners feel it.”
Contact Newsweek editors on this story: Ben Kelly and Sam Wilson.