Published : 15 October 2026
•
Updated : 15 October 2026, 01:38

Md Mehedi Hasan

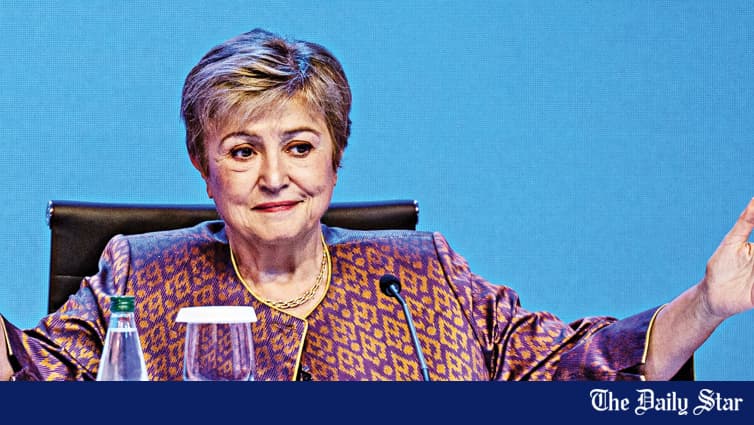
IMF Managing Director Kristalina Georgieva gestures during a briefing at the IMF-World Bank Group annual meetings in Bangkok yesterday. Photo: AFP
The global economy has weathered a series of shocks better than expected, but repeated disruptions are eroding countries’ capacity to respond, IMF Managing Director Kristalina Georgieva said on Wednesday.
Presenting the fund’s Global Policy Agenda at a press conference during the 2026 Annual Meetings of the IMF and the World Bank in Thailand, she said global growth is projected at 3.1 percent in 2026, unchanged from the April forecast but below last year’s 3.4 percent.
The IMF said the stable headline figure masks “divergent outcomes” across economies.
Two opposing forces are at work. Wars in the Middle East and Ukraine are disrupting supply chains and driving up commodity prices, while rapid advances in artificial intelligence (AI) are boosting investment, trade and stock markets.
The energy shock proved less damaging than feared, thanks to flexible supply responses, inventory drawdowns, lower oil dependency and fiscal support.
A downturn has been avoided “for now”, the IMF said, but growth remains modest and inflationary pressures persist.
Energy exporters not directly affected by the conflicts, economies integrated into technology value chains, such as Thailand and Malaysia, and countries with strategic reserves have fared better. Energy importers, countries with limited policy buffers and those less exposed to the technology boom are facing greater strain.
Many low-income and fragile states fall into the latter group, raising the risk of widening income disparities across countries.
ERODING BUFFERS
Policy buffers have weakened, the IMF warned. Global public debt is approaching 100 percent of gross domestic product (GDP), while rising sovereign bond yields in advanced economies are putting additional pressure on emerging and developing economies, particularly low-income countries facing high debt-service costs.
Other risks include trade tensions, El Niño’s potential impact on food markets, a possible market correction linked to AI, vulnerabilities in non-bank financial institutions and cyber threats.
Georgieva said cyber threats were already causing real-world damage, citing an incident in France in which a cyberattack caused refrigerator temperatures to rise, spoiling food. As such attacks become more frequent, they could target financial systems, turning cyber risk into a financial stability concern.
POLICY PRIORITIES
The IMF urged governments to protect people rather than prices, recommending temporary, targeted support for vulnerable households instead of broad price controls.
Credible fiscal consolidation remains a top priority, the fund said. A restrictive monetary stance is generally still warranted but should be calibrated to country-specific conditions. Monetary policy should tighten further if inflation expectations risk becoming unanchored.
Temporary foreign exchange intervention may be justified to curb disorderly currency movements, but it should not replace broader macroeconomic adjustment. Financial supervisors should also contain excessive leverage, particularly in technology-related exposures.
The fund said its “Bangkok Blueprint” aims to strengthen safeguards for digital finance, improve cyber protection and combat digital fraud.
It also cited research suggesting that AI could raise sub-Saharan Africa’s GDP by up to 4 percent cumulatively over a decade.
For low-income countries, the IMF stressed the need to address debt vulnerabilities despite declining official development assistance. It said it was involved in debt restructuring cases under the Common Framework.
The fund is also overhauling its surveillance and programme design to make its support “agile, selective, and realistic”.