…$100 oil price volatility clouds outlook
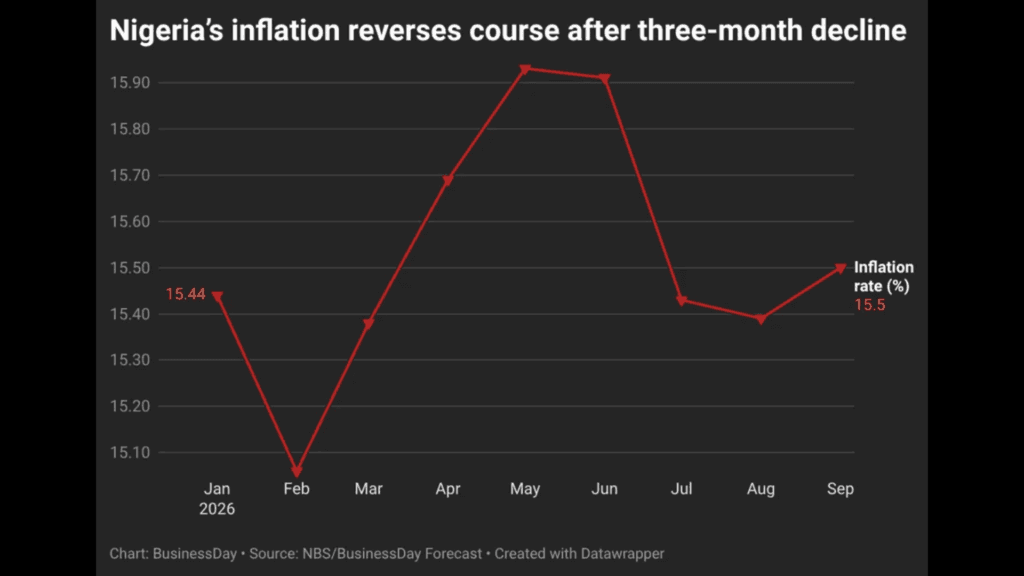
Nigeria’s headline inflation rate is projected to rise to 15.5 percent in September, potentially ending three consecutive months of easing, even as the Central Bank of Nigeria recalibrates its policy framework and international oil prices climb above $100 per barrel.
BusinessDay’s inflation forecast estimates a 0.11 percentage-point increase from August’s 15.39 percent. The forecast draws on an econometric model incorporating monthly inflation, exchange-rate and Purchasing Managers’ Index (PMI) data. It is a model estimate, not an official figure, ahead of the National Bureau of Statistics’ September report.
If the NBS September report, expected on October 15, confirms the projected increase, it would mark the fourth consecutive time the model has correctly anticipated the direction of inflation since the nowcast began. Its forecast errors have also remained below 0.06 percentage points across the previous forecasts, providing an encouraging early indication of its short-term predictive performance. However, the record remains preliminary, and its reliability will ultimately depend on how consistently it tracks actual inflation as economic conditions change.
Read also: Nigeria’s disinflation trend faces fresh test as September Inflation set to rise
The projected increase would be modest, but it could signal a pause in the recent disinflation trend. Meanwhile, the latest surge in crude prices presents a separate risk to the months ahead, particularly if higher international prices feed through to domestic fuel, transport and distribution costs.
Brent crude traded around $106 per barrel on October 13 amid supply concerns linked to tensions in the Middle East, although prices eased during the session. For Nigeria, higher oil prices offer a mixed outlook: stronger export earnings could support foreign-exchange inflows, but increased energy and distribution costs could add to domestic inflationary pressures.
The extent of that trade-off will depend on how international prices affect domestic petroleum costs, the exchange rate and businesses’ operating expenses. Higher crude prices do not automatically translate into higher domestic inflation, just as stronger export earnings do not guarantee immediate relief from imported inflation.
CBN’s rate reset does not mean cheaper money
The inflation outlook also comes after the Central Bank of Nigeria’s 350-basis-point adjustment to its Monetary Policy Rate (MPR), from 26.5 percent to 23 percent. Olayemi Cardoso, CBN governor, has cautioned against interpreting the move as conventional monetary easing.
Speaking after the September 21–22 Monetary Policy Committee meeting, Cardoso described the decision as a strategic reset and recalibration of the monetary policy framework, rather than a shift towards an accommodative stance. The objective was to improve monetary-policy transmission by bringing the official benchmark closer to prevailing money-market conditions.
The CBN recalibrated its Standing Facilities Corridor to 50 basis points above and 300 basis points below the MPR, while retaining existing cash reserve requirements, including the 45 percent ratio for deposit money banks.
Read also: IMF sees Nigeria’s growth rising to 4.3% in 2027 as inflation eases
The distinction matters because a lower policy-rate benchmark does not automatically make borrowing cheaper. Lending rates also depend on banks’ funding costs, liquidity conditions, credit risks, and expectations about inflation.
The CBN has maintained that its monetary stance remains restrictive and that future decisions will depend on incoming economic data.
For households and businesses, therefore, the important question is not simply whether the MPR has fallen, but whether financing costs and operating expenses will ease enough to support investment, production and purchasing power.
A fragile disinflation path
Nigeria’s inflation rate declined from 15.91 percent in June to 15.43 percent in July and 15.39 percent in August. A September estimate of 15.5 percent would reverse part of that improvement, but one monthly increase would not, by itself, establish that the broader disinflation trend had ended.
The forecast uses historical relationships among inflation, exchange rates and business activity to estimate the latest movement in prices. Its reliability depends on how well those relationships continue to hold and whether unexpected developments alter the outcome. The estimate should therefore be treated as an indication of the possible direction of inflation, not a substitute for the official NBS release.
Read also: East African central banks hold rates as inflation risks persist
The immediate challenge for policymakers is to sustain disinflation while improving the transmission of monetary policy to the wider economy. A rate reset that better reflects market conditions may strengthen the policy signal, but it will not resolve inflationary pressures on its own.
Food prices, exchange-rate stability and domestic fuel and distribution costs will remain important to the trajectory of consumer prices. The September data will show whether the recent decline in inflation has paused. Beyond that, the interaction between domestic price pressures, monetary conditions and elevated oil prices will help determine whether disinflation resumes or becomes more difficult to sustain.
Related News

Oluwatobi Ojabello, PhD, is a dynamic and multi-dimensional Assistant Editor for Economy and Markets with over two years of professional journalism experience. He delivers authoritative, data-driven coverage of fiscal policy, financial institutions and capital markets, using clear analysis to explain Nigeria’s most complex economic developments. His work focuses on macroeconomic policy, financial stability and corporate performance, turning technical issues into accessible narratives that inform both experts and everyday readers.

