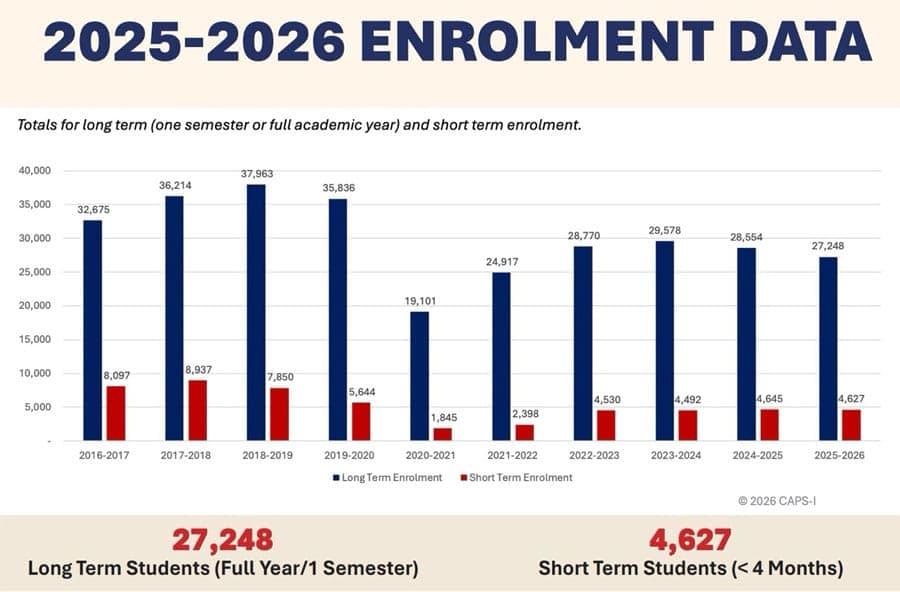
According to CAPS-I (Canadian Association of Public Schools–International) , 31,875 international K–12 students attended 125 Canadian public schools (that are members of CAPS-I) in the 2025/26 academic year. This is a -4% decline from the previous year, and the decrease can mostly be attributed to fewer Chinese students enrolling in Canadian public schools.
Note: International students also enrol in private schools in Canada, and the CAPS-I data does not count this set of students.
Most students are in long-term programmes
The vast majority of students enrolled in long-term programmes of one semester or a full academic year (27,250), with the remaining 4,630 in short-term programmes of up to four months. Enrolments in long-term programmes have fallen since 2023/24, while short-term programmes are stable.
Europe up, China down
Strong growth from Europe wasn’t enough to offset a -21% decrease from China, by far the largest market, but there are signs that Canadian schools are working to diversify their international student nationalities.
Of the Top 10 origin countries for K–12 students, Germany grew by +27% and remains the number two market. South Korea grew by +10%, moving it into third spot in front of Japan, which declined modestly by -2.5%. Italy and Spain sent +7.5% and +9.5% more students, respectively, and Brazil increased by -2%. But Mexico was down -14.5%, and Hong Kong was down even more significantly (-21.5%).

The next tier of sending markets – 11 to 20 – all grew, with the exception of Thailand. The most notable increase was a +50% rise in Swiss students. Czechia and Austria made the Top 20 list of source countries for the first time.
While Europe is showing strong potential, many families of K-12 students from the region choose short-term programmes, making it difficult for Canadian schools to mitigate the decline from Asia. However, CAPS-I executive director, Bonnie McKie, told ICEF Monitor she is optimistic that many of markets that grew in 2025/26 will continue to do so “whether during the typical academic year or summer camps.”
Challenges for the sector
Canada’s international student cap is having an overall effect of depressing volumes of new foreign students at all levels despite being targeted at the post-secondary level. K–12 international students are actually exempted entirely from the cap, but in overseas markets, a nuanced differentiation between which students are affected by which policy is sometimes lost. The CAPS-I report elaborates:
“While no measures specifically targeted the K–12 sector, the various immigration policy changes imposed by the Canadian government over the last 2 1/2 years have continued to have an impact across all sectors. These measures have caused confusion, disappointment and have changed pathway/future post-secondary and employment opportunities for international students, weakening the Canadian ‘brand.’”
Another challenge is the growing number – and popularity – of international schools in some of the key source countries for K–12 educators across leading destinations. International schools are privately owned schools delivering alternative curricula than that of the host country at least partly in English.
More than half (58%) of all international schools are in Asia. China and India are the top hosts at the country level. ISC research finds that local families are the main drivers of demand, which is different than in the past, when international schools’ main market was the children of expatriates. Local demand is also picking up because of the increasing number of schools delivering bilingual instruction. More than a third of all international schools now use a bilingual model.
As it stands, Canada lags the UK, Australia, and the US in the number of international schools it has around the world. It accounts for only 1% of the total supply. The UK, in particular, is mitigating lower foreign demand for onshore K–12 education by enrolling thousands of students in its many international schools abroad.
The matter of supply
A separate BONARD analysis suggests that the two-year decline in CAPS-I member schools’ international enrolments may stabilise in the coming year. The research firm looked at visa grant rates for study in public and private primary and secondary schools in 2025 and 2026 and found that: “10,000 new K-12 study permits were issued in Q2 2026, 19% more than in Q2 2025, with a 74% grant rate.”
Demand is clearly still there for K-12 education in Canada, and CAPS-I notes that part of the reason for the -4% fall in international enrolments in 2025/26 is actually a matter of supply:
“Approximately half of CAPS-I member programs that experienced a decline or no growth in enrolment also cited internal constraints, including limitations in terms of school capacity and host family availability. On a positive note, 40% expected school capacity to improve in the next 1–3 years and host family capacity is always a priority.”
For additional background, please see:
- “Foreign enrolment in Canadian K-12 held steady in 2024/25”
- “Continuing expansion of K–12 international school sector driven more by growing local demand”
The post Canada: Chinese enrolments in public K-12 schools decline, but other key markets remain strong appeared first on ICEF Monitor - Market intelligence for international student recruitment.