You could be missing out on hundreds of dollars in savings simply because you aren't checking your credit card merchant offers.
Many major card issuers offer discounts at popular retailers, restaurants and hotels — sometimes worth $100 or more. And taking advantage of these offers is as easy as it gets: Log into your card account online or through your app, review your available offers, add the ones you want and make a qualifying purchase using the card the offer is registered to.
It's a super simple way to save on purchases you were already planning to make, without hunting for promo codes. Here's how the major credit card merchant offer programs compare, plus how to stack offers to maximize your savings.
Amex Offers
Amex Offers is an important part of the trend of card-linked offers, providing an expansive set of offers. You'll often find 100 or more potential discounts, and they can be different for each Amex card you have. With that many to scroll through, you'll almost certainly find some that match your expected spending.
While Amex Offers often lean heavily toward online retail purchases, I do sometimes see travel-related offers. For example, right now on my account, I have offers for $30 off eligible Turo car rentals, $50 off Europcar and $50 off Italo (Italian high-speed) train charges. Amex Offers are targeted, so not every cardmember will see the same deals. My husband and I typically receive different offers in our accounts, which gives us two ways to save.
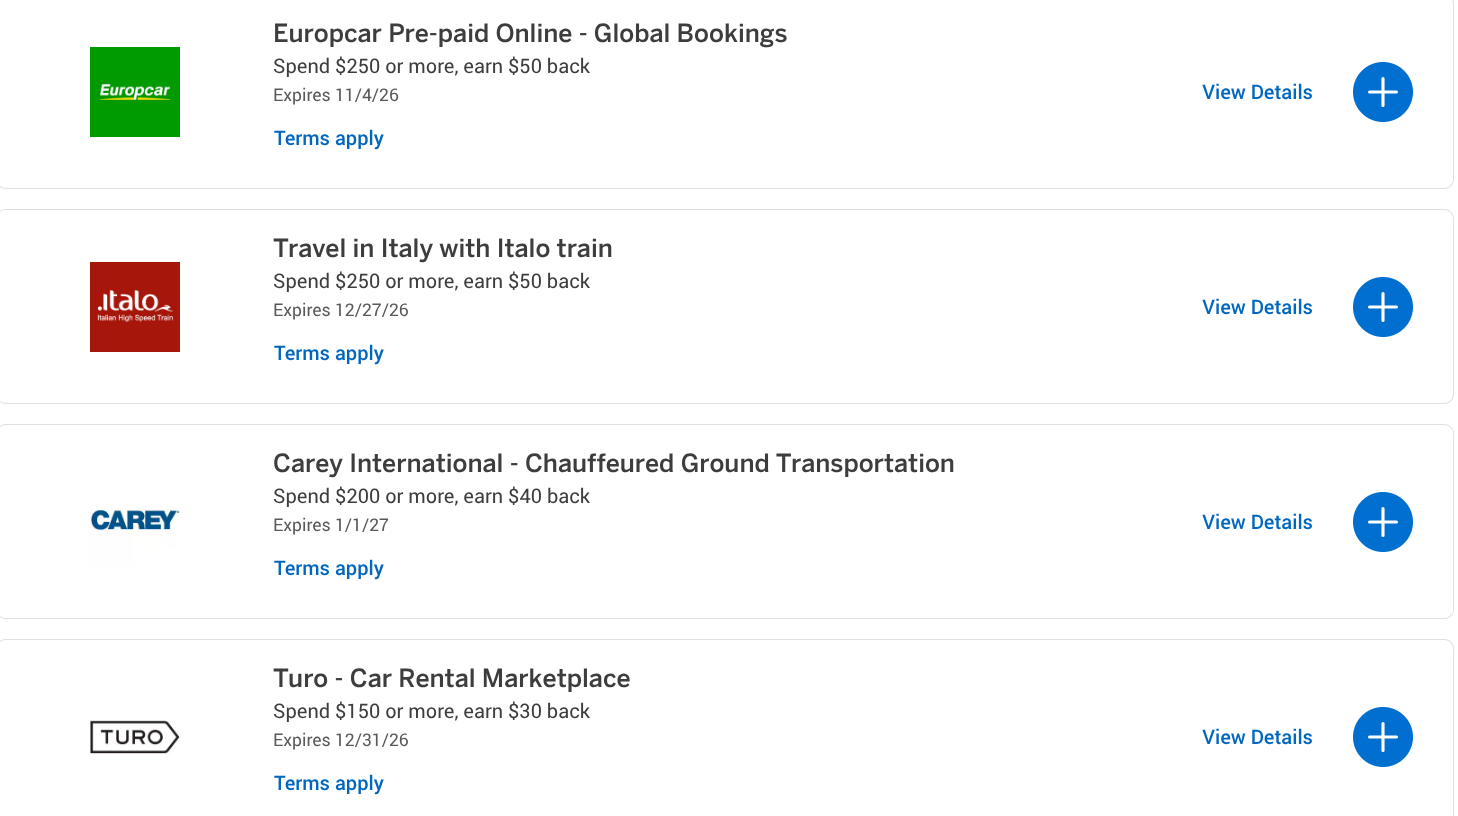
Most of the time, Amex Offers can be combined with other discounts as long as the final charge on your card still meets the minimum listed threshold.
Additionally, Membership Rewards-earning cards sometimes provide bonus points on eligible purchases rather than cash back. For example, you may find an offer for 10,000 bonus points instead of $100.
Since TPG's October 2026 valuations peg Membership Rewards points at 2 cents each, earning your rebate in points can make it an even sweeter deal.
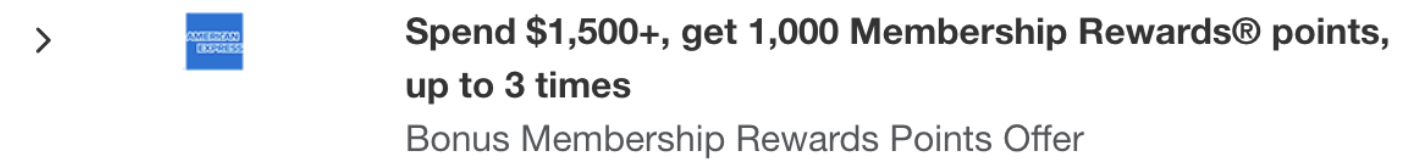
Be careful to check the details for each of these offers, though. Sometimes you'll need to meet the minimum spending requirement in a single transaction. There's no room for error: If you spend one penny short of the required amount, you'll miss out on the deal entirely.
You'll also want to check the offers on all your American Express cards before adding one to your account. You can typically only add a specific Amex Offer to a single card, so you'll want to be sure you've added it to the card that offers the highest discount, best rewards or most comprehensive protections.
Interested in using Amex Offers? Consider applying for one of these Amex cards:
- American Express® Gold Card: Find out your offer and see if you are eligible for as high as 100,000 bonus points after spending $8,000 on purchases in the first six months of card membership. Welcome offers vary, and you may not be eligible for an offer ($325 annual fee; see rates and fees). To learn more, check out our full review of the Amex Gold Card.
- American Express Platinum Card®: Find out your offer and see if you are eligible for as high as 175,000 bonus points after spending $12,000 on purchases in the first six months of card membership. Welcome offers vary, and you may not be eligible for an offer ($895 annual fee; see rates and fees). To learn more, check out our full review of the Amex Platinum Card.
Bank of America Deals
While Bank of America also has a merchant offers section with two different types of offers: online and in-person deals.
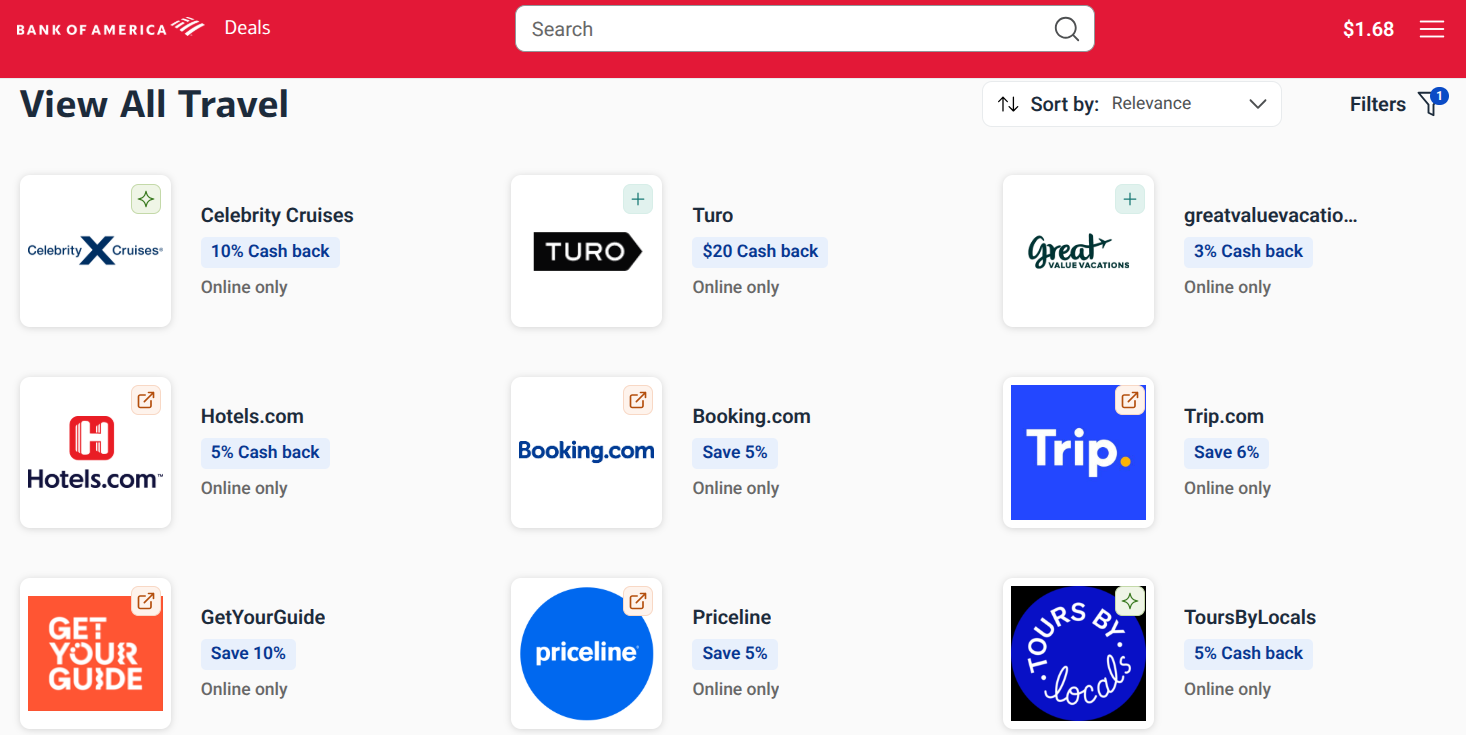
The online offers typically require you to begin your purchase through Bank of America's designated link and pay with your card. Because of this, you'll forfeit the opportunity to earn any rebates or bonus rewards from a shopping portal.
The offers in my account included some where I'd be happy to forgo shopping portals (like 10% back on Celebrity Cruises) and some that are more run-of-the-mill.
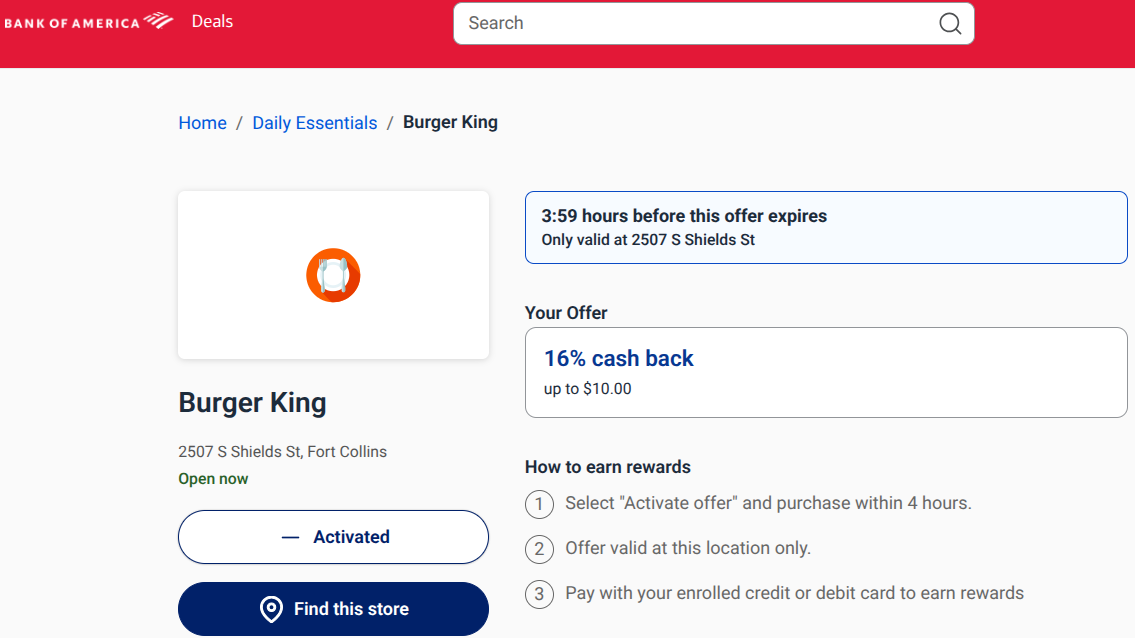
The offers for in-person transactions can be strong, but these, too, are limited. Right now, I'm seeing cash-back offers for Burger King and other food, gas and retail partners.
However, rather than listing a classic expiration date, the clock to use your offer starts ticking immediately. For the Burger King offer, once activated, it was only valid for four hours. That means you'll need to stay closely on top of things to activate and use offers. It's not as "set it and forget it" as some other credit card merchant offers.
One of my favorite travel credit cards from Bank of America is the Atmos™ Rewards Ascent Visa Signature® credit card. It earns 2 points per dollar spent on eligible gas, electric vehicle charging station, cable, streaming services and local transit (including ride-hailing) purchases. That lines up well with a lot of the merchant offers I see in my account.
Related: Bank of America expands rewards access with new no-fee loyalty program
Capital One Offers
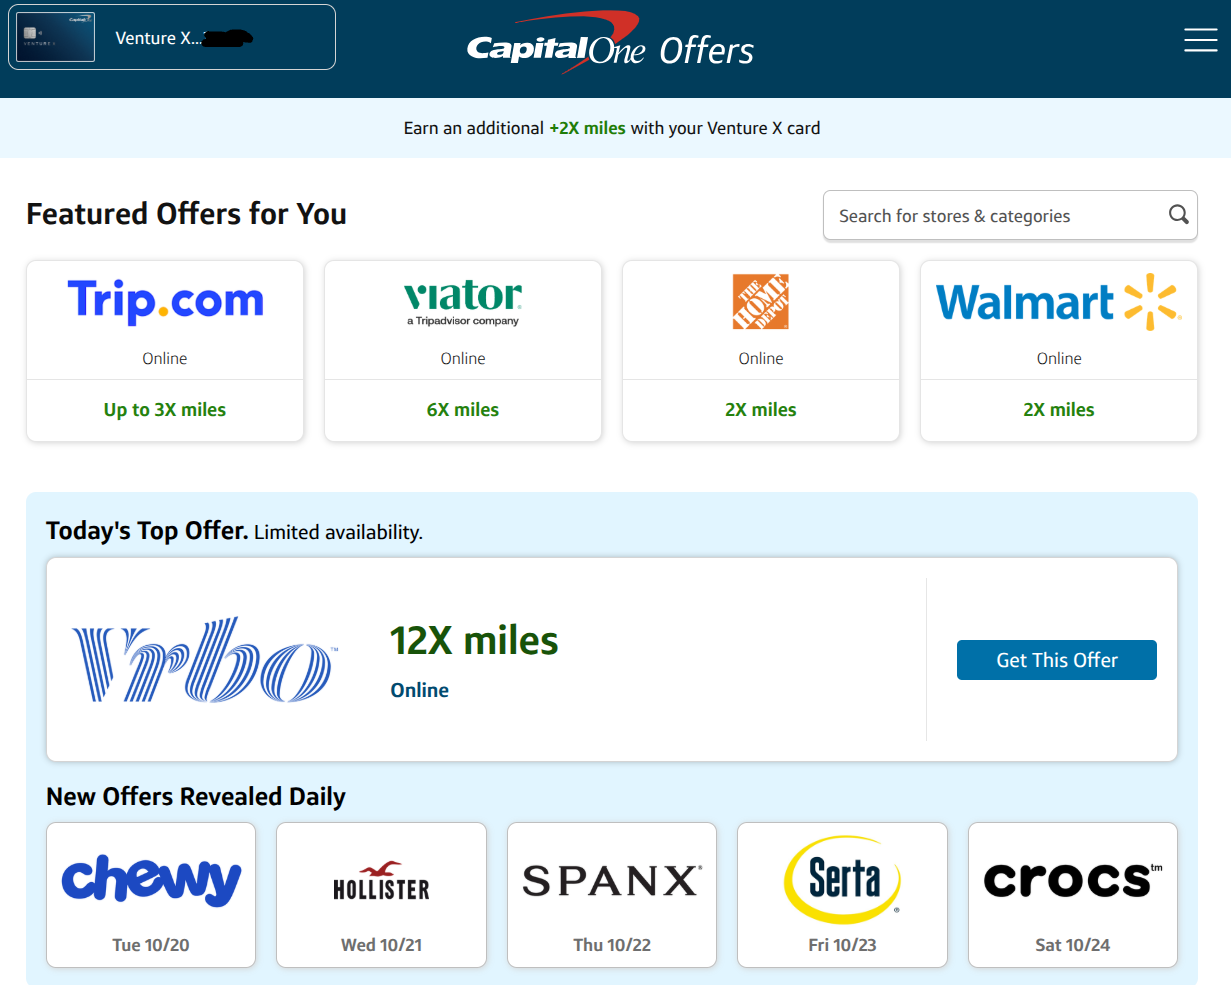
Capital One Offers work a little differently from the other programs on this list. For online purchases, you'll need to click through Capital One's link and complete your purchase in the same browser session, making it function more like a shopping portal. However, Capital One also has in-store offers that you activate before paying with your linked Capital One card.
Because online offers rely on Capital One's tracking link, you generally can't stack them with another shopping portal. Compare the payouts before choosing, keeping in mind that TPG values Capital One miles at more than 1 cent apiece as of our October 2026 valuations. That can make a miles-earning Capital One offer more valuable than a cash-back portal's advertised rate.
If you're looking for a strong card to pair with Capital One Offers, consider the Capital One Venture X Rewards Credit Card. Purchases that don't fall into a bonus category still earn 2 miles per dollar spent, making it an excellent choice for many retail offers.
Related: Complete guide to saving money with Capital One Offers
Chase Offers
One thing I love about Chase Offers is that you can often add the same offer to multiple cards. Since Chase is a popular card issuer, a lot of people have more than one Chase credit card, making this a huge advantage if there are retailers or partners you frequent.
Offers aren't always identical — one card might offer 5% back while another offers 7%, for example — and sometimes the best offer is on my lesser-used card. It can also give you a reason to use an otherwise inactive credit card for a purchase, earning a rebate while showing new card activity.
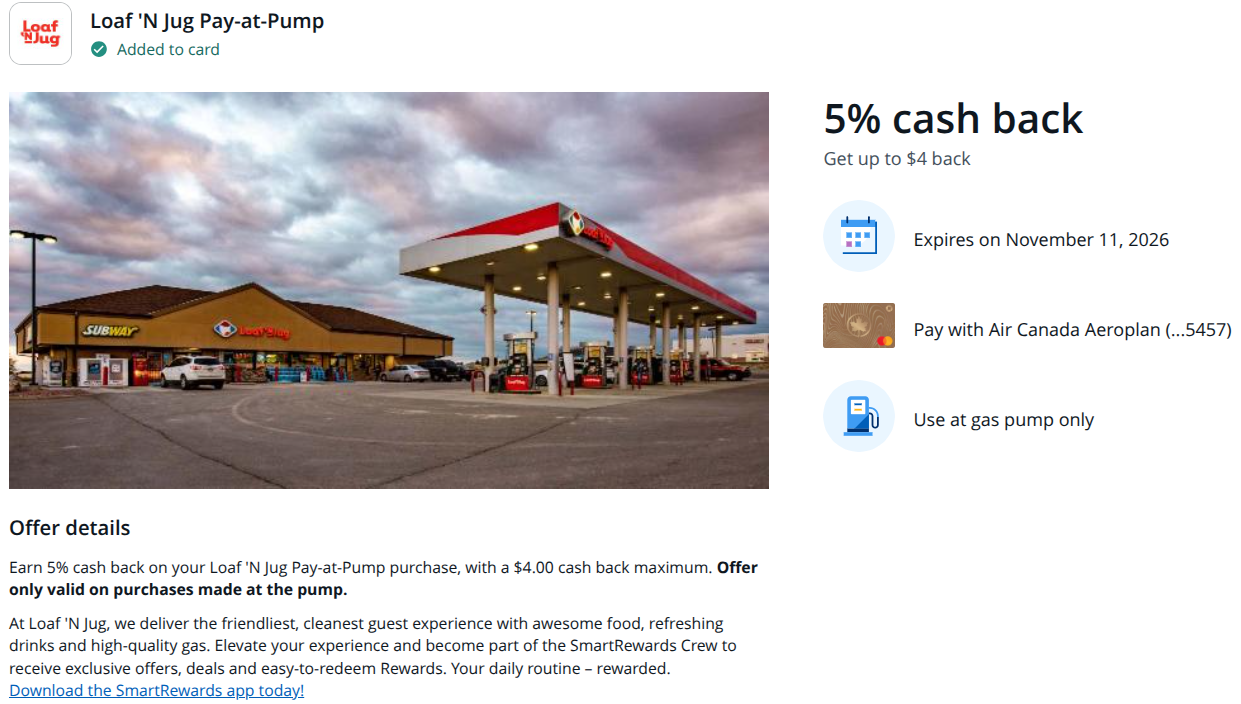
Another thing I love about Chase Offers is that everyday brands are frequently featured. Recent offers in my account have included Loaf 'N Jug gas stations, King Soopers grocery delivery and Sprouts Farmers Market.
On the flip side, Chase Offers frequently come with low limits. For example, this gas offer tops out at $4 in savings.
If you're interested in combining gas and grocery offers with strong rewards, you might want to look into the Chase Freedom Flex® (see rates and fees).
Its rotating quarterly categories earn up to 5% cash back on up to $1,500 in spending each quarter (after activation) on top of what you earn through Chase Offers. Plus, new cardholders can earn $250 cash back after spending $500 on purchases in the first three months from account opening. It's one of our favorite Chase credit cards for everyday expenses.
Citi Merchant Offers
Like Amex, the Citi Merchant Offers program includes offers from a huge volume of merchants. Offers are conveniently sorted by category, making it easy to scroll through and add anything that catches your eye.
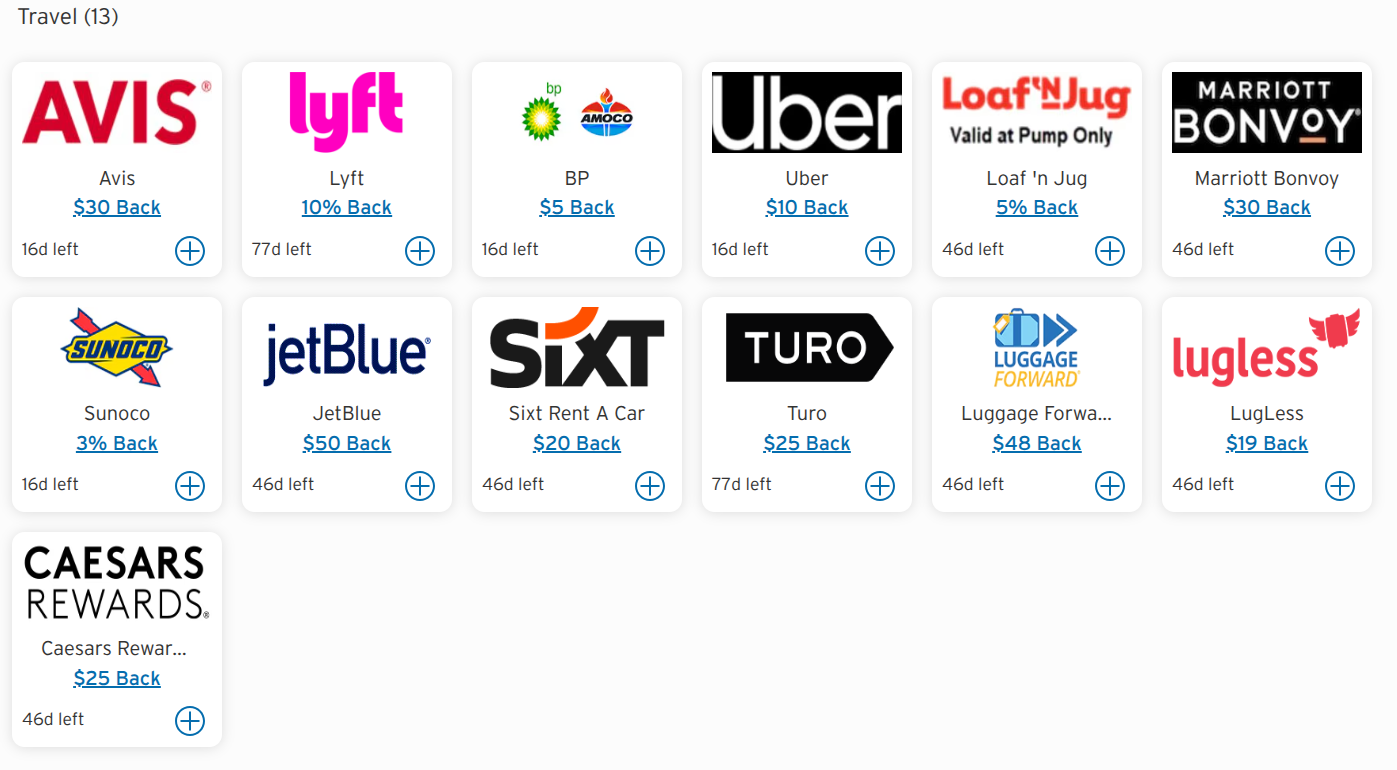
With Citi offers, the devil is in the details. The fine print of each offer is often very specific, so make sure your purchase is in line with the terms and conditions. Sometimes travel discounts only apply to prepaid bookings. Still, if you see a deal like $50 off a JetBlue airfare purchase of $250 or more, the savings are significant enough to be worth your time.
If you're looking for a new Citi card, consider applying for the Citi Strata Premier® Card (see rates and fees). It's currently offering new cardholders 60,000 ThankYou points, earned after spending $4,000 on purchases in the first three months from account opening, which you can use for many great redemptions.
U.S. Bank cash-back deals
U.S. Bank's cash-back deals feature familiar brands you're likely to shop with anyway, like Dunkin', Chewy or CVS. And unlike most of the other card merchant offers we've discussed, U.S. Bank cash-back deals are valid on debit cards, too (though at TPG, we think credit cards are better than debit cards in most scenarios).
Offers are targeted and based on your card activity, so you'll likely see some offers at places you frequent — or their competitors.
Small-business owners looking for a card to pair with these deals should consider the U.S. Bank Business Essentials™ Visa® Card. It earns unlimited 2% cash back on every purchase and has no annual fee, making it easy to stack your regular card rewards with an activated U.S. Bank deal.
Related: How to choose the right credit card for you
Stack with a shopping portal
Many credit card merchant offers can be stacked with shopping portal rewards to earn even more miles, points or cash back.
For example, if the United shopping portal is offering 1 mile per dollar spent at Home Depot, you could click through to earn United miles, then pay with a card that has an activated Home Depot offer to earn additional cash back.
Some merchant offers, especially through Capital One and Bank of America, require you to use their link rather than a shopping portal's, so you'll need to double-check the terms of your offer. But more often than not, you can stack both types of savings.
Most major airlines, hotels and even some card rewards programs have their own shopping portals. Some TPG favorites are Rakuten and Rove. Rakuten lets you earn Membership Rewards or Bilt Points instead of cash back, while Rove earns transferable miles with over 20 partners.
- If you join Rakuten through a referral link by Dec. 31 and spend at least $50 at eligible retailers within 90 days of becoming a member, both you and your referrer will receive a one-time bonus of $50.
- Not a Rove member yet? Sign up through this link and earn a referral bonus of 1,500 miles, with the opportunity to earn an additional 5,000 miles when making your first hotel booking over $500 as a new user with the code "BRIANKELLY500."
Related: Earn points, miles or cash back: How to maximize online shopping portals for your purchases
Use tools to manage and stack offers
Checking every card issuer individually can become tedious, especially if you have several cards. Third-party tools can consolidate your offers and help you identify savings without logging in to every account.
MaxRewards
MaxRewards is designed to help manage your card-linked offers. It gathers deals in one place, tracks expiration dates and recommends which card to use for a purchase, so you can quickly keep an eye on offers across a wallet full of cards. Paid members can also automatically activate offers, potentially capturing deals they might otherwise overlook.
Even with automatic activation, you'll need to review an offer's spending requirement, expiration date and other terms to ensure your purchase qualifies.
Savewise
Savewise is more shopping-focused. It compares rewards across shopping portals and displays card-linked offers alongside them, making it easier to spot opportunities to stack multiple rewards on the same purchase.
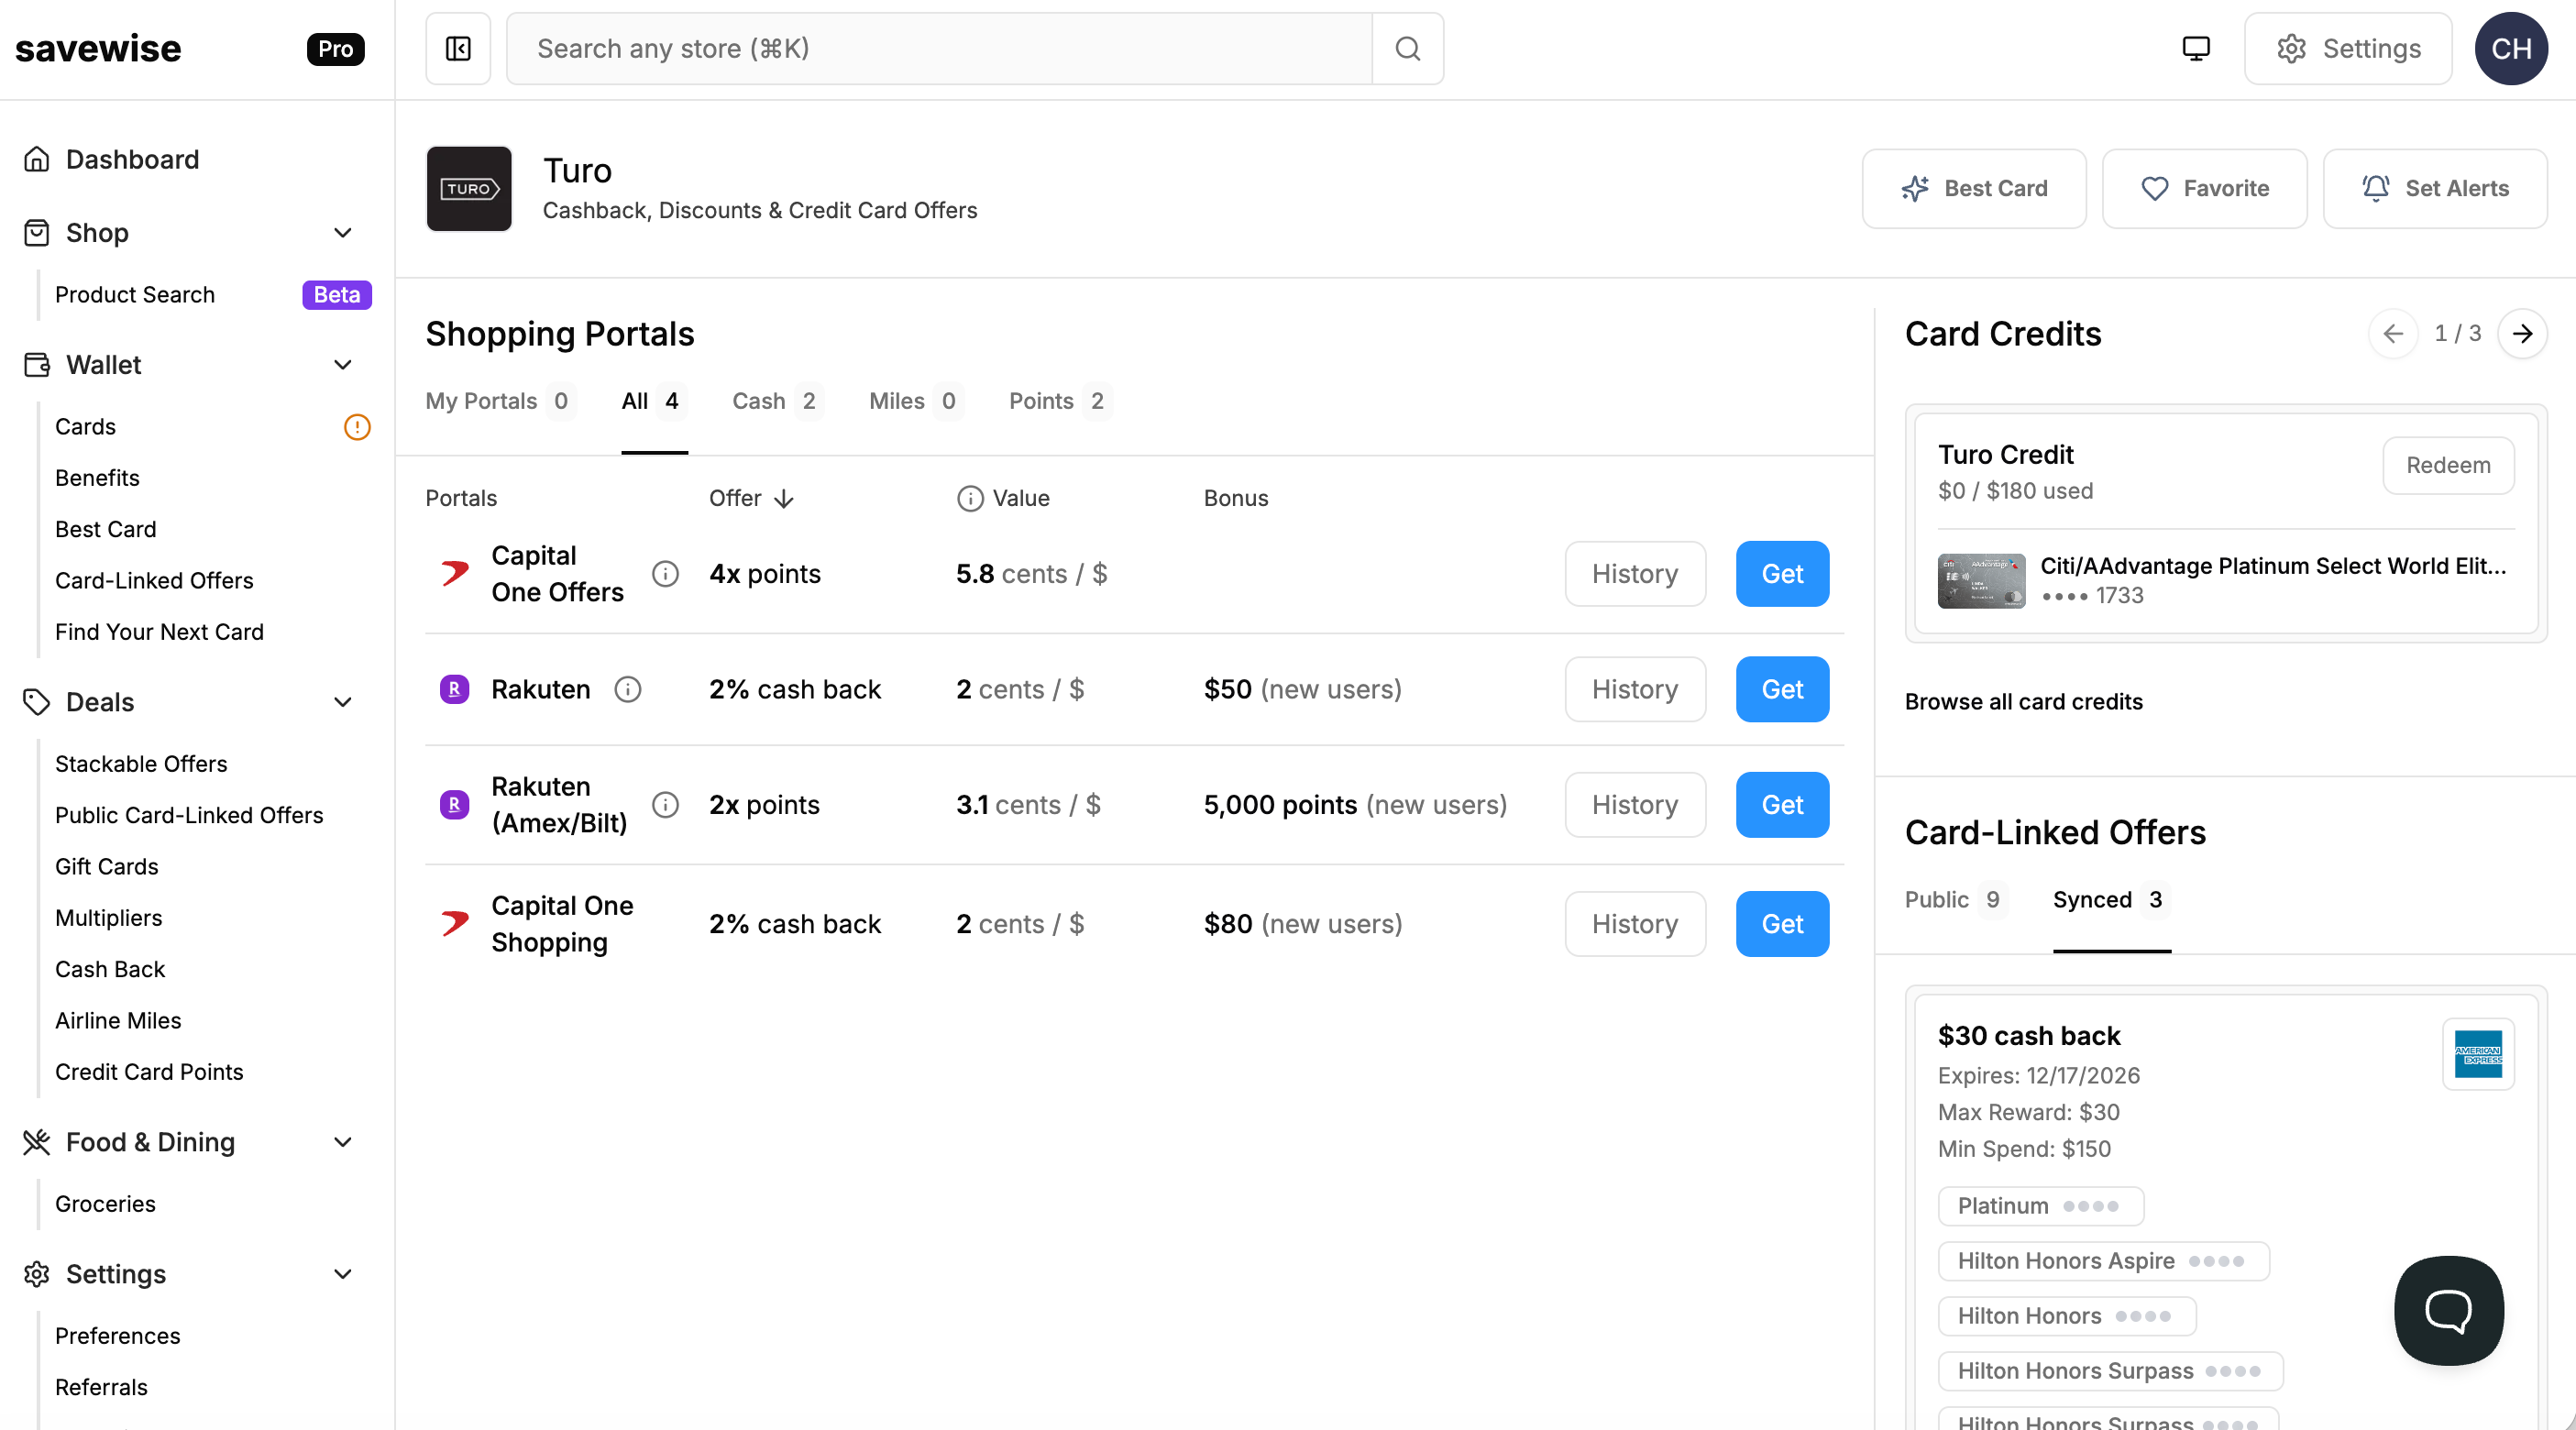
Its paid tier also adds automatic offer activation, offer alerts and rate history. This can be especially useful before a large purchase, when you may want to know whether the current portal payout is competitive.
Related: How I use Savewise to stack shopping portals, credit card offers and cash back for bigger rewards
Bottom line
Amex Offers may have the most eye-catching rebates, but the best merchant offers are the ones that line up with purchases you make anyway. Smaller discounts add up, too, especially if you stack them with shopping portal rewards.
Make a habit of checking your offers whenever you log in to check on your account anyway. If you're unsure whether you'll use an offer, there's generally no downside to activating it just in case. For offers you won't use immediately, take notes on any terms, expiration dates or minimum spending amounts or use a third-party program to help keep track of details.
Otherwise, you could be leaving easy savings on the table.
Related: TPG's 10 commandments of credit card rewards
For rates and fees of the Amex Gold card, click here.
For rates and fees of the American Express Platinum card, click here.
Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.