The future of the LPGA’s television revenue hinges on two massive deals happening elsewhere in sports. With both the PGA Tour and the LPGA holding current contracts that run through 2030, the women’s circuit faces a pivotal moment. The league is already preparing for the next round of negotiations, but the timing depends heavily on what happens with the NFL and the men’s tour. If those deals shift the market value, the LPGA could see a dramatic change in its own payout.
LPGA leadership is actively shifting its focus to these next media rights deals, as reported by Front Office Sports. A looming threat to the women’s circuit is the PGA Tour’s potential early move to market. Both tours currently operate under agreements that extend until 2030.
Directly linked to the PGA Tour’s $700 million annual media contracts are the LPGA’s broadcast deals with CBS, NBC, and Golf Channel. However, the women’s game receives only a small percentage of that rights fee revenue. This financial structure means the LPGA cannot set its own price in a vacuum; it must wait for the broader market to clear.
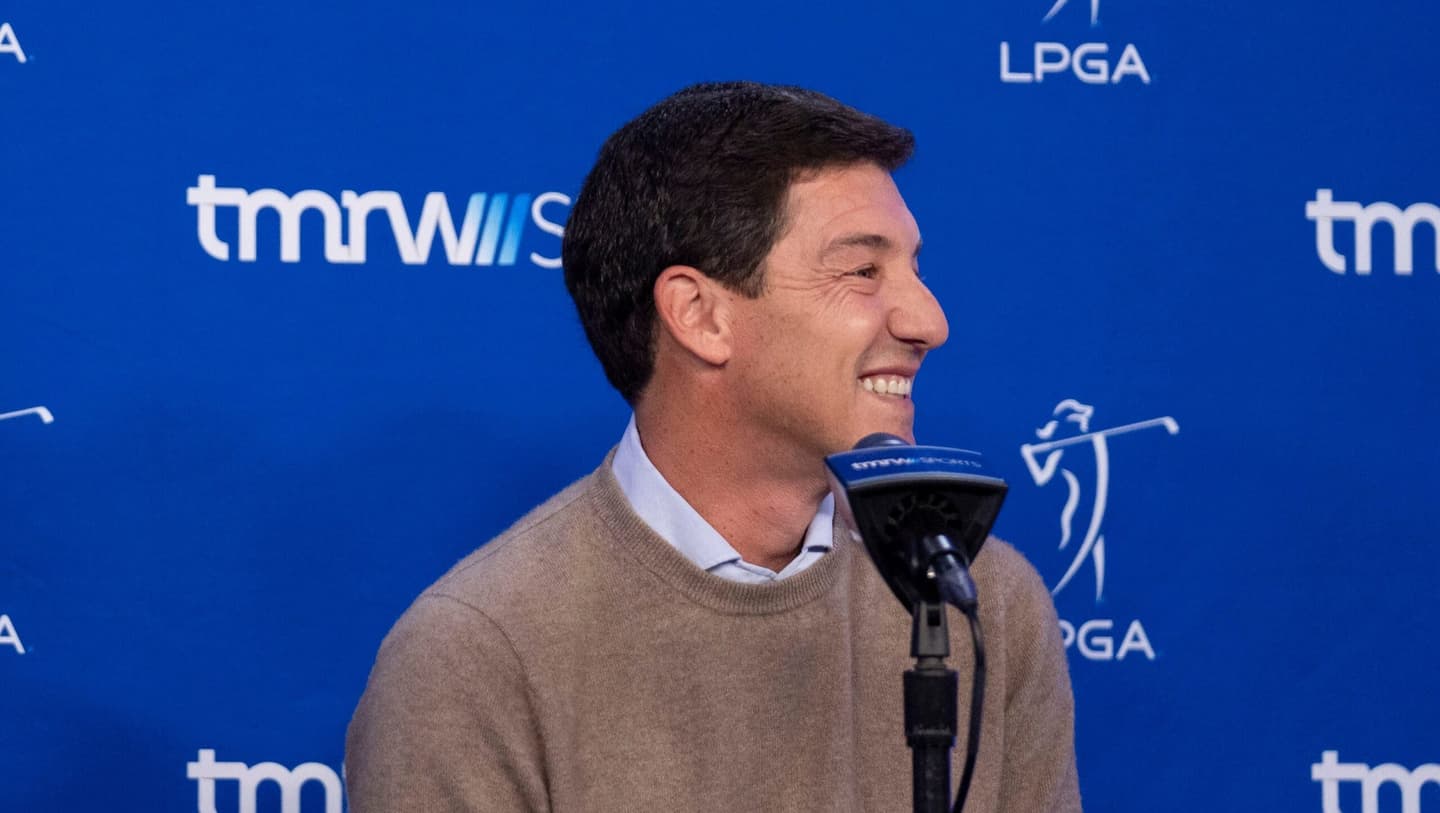
As the NFL plans to exit its agreements after the 2029 season, concerns grow that costlier new league deals could block other sports from securing profits. The sheer cost of securing NFL rights could squeeze the budgets available for other sports. During Tuesday’s Front Office Sports Tuned In summit, LPGA commissioner Craig Kessler stated that negotiations for both the PGA Tour and NFL are under intense scrutiny. He emphasized that the league is preparing for any scenario. “And depending on how those media rights contracts play out, we’ll be ready no matter what the outcome is,” Kessler added.
Despite the uncertainty, the viewing numbers tell a compelling story for the league. Through September, average viewership for LPGA broadcasts in final rounds is at 200,000. This is up significantly from an average of 150,000 in 2025. When Nelly Korda captured the U.S. Women’s Open, NBC recorded the year’s highest audience with 1.3 million viewers. These figures suggest the product is gaining traction even as the business model remains dependent on the men’s tour.
Kessler noted that while “there’s only so much money to go around,” he remains bullish on the LPGA’s potential. He argued that the current valuation does not reflect the growth, stating, “If you look at where we’re valued today, and you compare that to the viewership we drive throughout the golf ecosystem, I would argue we are one of the most undervalued, discounted growth stocks in the sports market today.”
The Variable of Timing and Market Cap
The core issue for the LPGA is the timing of the market. If the NFL and PGA Tour secure record-breaking deals before the LPGA goes to market, it could set a higher benchmark for what a sports property is worth. Conversely, if the market tightens due to the high cost of NFL rights, the LPGA might find fewer dollars available.
Kessler acknowledged the complexity of the situation during the summit. “There are so many variables, and we’ve got a highly capable team working with external advisors to be ready,” he said. This preparation is crucial because the league cannot afford to be caught off guard when the negotiation window opens.
The current landscape creates a unique pressure point. The LPGA is not just negotiating for its own rights; it is negotiating within an ecosystem dominated by the PGA Tour’s $700 million annual deal. Because the LPGA receives such a small slice of that pie, any increase in the total pot is vital. However, the NFL’s potential opt-out in 2029 adds a layer of unpredictability.
Broadcasters might prioritize locking in NFL rights over expanding golf coverage, or they might be forced to pay a premium for the NFL that leaves less room for other sports. The LPGA’s strategy relies on demonstrating that their viewership growth justifies a larger share of the remaining budget.
Front Office Sports reporting highlights that the league is aware of these constraints. The sentiment among industry observers is that the NFL deal could act as a ceiling for other sports contracts. If the NFL commands a massive increase, networks may not have the flexibility to offer the LPGA a significantly higher rate without cutting costs elsewhere.
This makes the LPGA’s ability to prove its value through viewership numbers, like the 2.2 million peak for Korda’s win, even more critical. The league needs to show that it is not just a small add-on to the PGA package, but a standalone asset with significant growth potential.
What the Numbers Mean for the Future
The jump from 150,000 to 200,000 average viewers represents a 33% increase in a single year. That kind of growth is rare in sports broadcasting and suggests the LPGA is successfully capturing a wider audience. Kessler’s comment about being an “undervalued, discounted growth stock” reflects this reality.
If the league can maintain this trajectory, it could leverage these numbers during the next negotiation cycle. The challenge remains the structural dependency on the PGA Tour. Until the LPGA can negotiate its own independent rights or a significantly larger share of the joint deal, its fate remains tied to the men’s game and the NFL’s spending power.
The commissioner’s confidence is evident, but the variables remain high. The team working with external advisors is tasked with creating a strategy that works regardless of the NFL or PGA outcomes. Whether the market expands or contracts, the LPGA must be ready to step into the conversation. The goal is to ensure that the viewership gains translate into financial reality. As Kessler noted, the potential for upside is tremendous, but only if the league can navigate the complex web of media rights negotiations that are currently unfolding across the sports world.
The next concrete step for the league involves the ongoing monitoring of these negotiations. While no specific date for the LPGA’s next deal has been announced, the industry is watching the NFL’s 2029 opt-out clause and the PGA Tour’s early market moves closely. The LPGA will need to present its case once the broader market signals become clearer. Until then, the focus remains on building the brand and proving the value of the product to potential partners.
Looking Ahead to the 2029 Opt-Out
The immediate future for the LPGA depends on the outcome of the NFL and PGA Tour talks. The LPGA faces a ticking clock to establish its position as the NFL prepares to opt out of its contracts after the 2029 season. The league will need to decide when to enter the market to maximize its value. If they wait too long, they might miss the window of opportunity created by a booming NFL deal. If they move too early, they might settle for less than their true worth.
The LPGA’s leadership has made it clear they are ready for any outcome. The next scheduled event for the league is the continuation of the current broadcast season, with the goal of building on the 200,000 viewer average before the next major negotiation cycle begins.