16h05 ▪ 6 min read ▪ by Lydie M.
Summarize this article with:
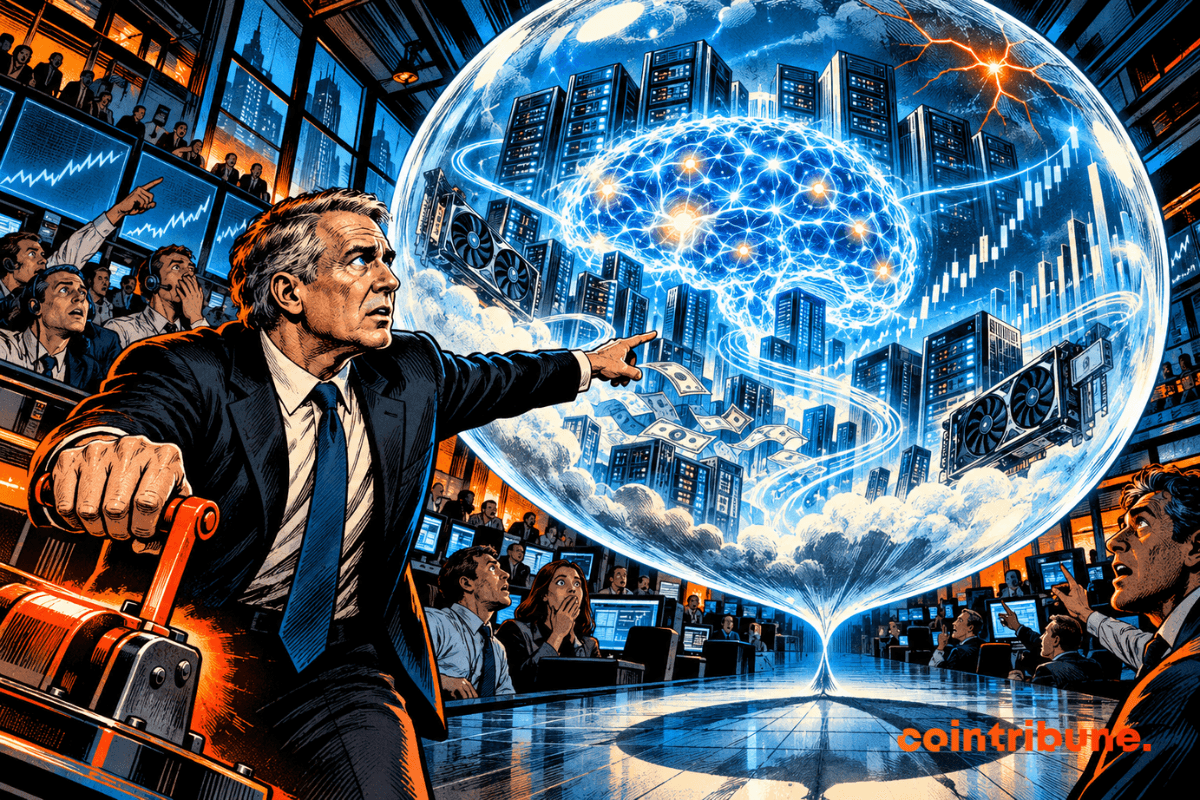
Ken Griffin believes investors are “almost certainly” in an AI-related bubble. The founder of Citadel does not, however, question the technology itself. His concern is mainly about the amounts invested, the cost of GPUs, and the difficulty many companies have in turning their expenses into productivity gains. For him, a correction could eliminate many players while allowing the future giants of the sector to emerge.
In brief
- Ken Griffin believes the AI market almost certainly shows bubble characteristics.
- He especially warns about possible GPU overcapacity and the still uncertain profitability of investments.
- Griffin still thinks survivors could dominate the market for several decades.
Ken Griffin almost certainly sees a bubble in AI
Ken Griffin delivered his diagnosis during the Future of Global Markets conference organized by Citadel in New York. The billionaire thus joins several investors who are already questioning a possible overheating of AI-related valuations.
His position remains, however, more nuanced than a simple call to sell. “Any radical transformation of our economy is generally related to a bubble,” he explained. Griffin notably cites the Internet. In the late 1990s, companies without a real business model had reached valuations that were difficult to justify.
Many disappeared after the Internet bubble burst. Amazon, for its part, remained. Griffin even admits regretting selling his own Amazon shares too early. For AI, he sees a comparable mechanism. Markets are already anticipating a huge transformation of the economy, while not all companies have yet proven they can generate enough money with this technology.
Investments are still climbing, though. According to LSEG data cited this week, Amazon, CoreWeave, Google, Meta, Microsoft, and Oracle had already issued about $193 billion in bonds by early August to directly or indirectly finance their AI-related infrastructures. In 2024, this figure was only $16.7 billion.
GPUs could become much less profitable
Griffin is especially watching the chip market. He compares GPUs to airplane seats: once the infrastructure is purchased, the extra cost to use unused capacity becomes relatively low.
The problem begins when supply exceeds demand. Griffin recalls what happened with fiber optics in the early 2000s. Telecom operators had installed a huge amount of capacity thinking that demand would immediately follow.
It did not follow fast enough. Prices collapsed. The head of Citadel wonders today if some AI chips could experience the same scenario. GPUs five or six years old are still rented at prices he considers particularly high.
He doubts this situation could last another five or six years. The questions are no longer only about investors, either. In August, economists from the ECB were already judging a correction of AI-related tech stocks probable.
Companies are also beginning to look more closely at their bills. Griffin believes American businesses have had very mixed results with their AI models. Some really save time and increase productivity. Others spend a lot without yet being able to precisely measure the return.
OpenAI and Anthropic charge for models among the highest performing on the market. But for certain tasks, much less expensive open-source models may suffice. This comparison becomes important when bills reach millions of dollars.
An AI bubble can burst without killing the technology
Griffin therefore does not see the possible existence of a bubble as proof that AI is overvalued overall. His own group already uses the technology extensively. At Citadel, some AI agents can reduce research work that previously took several weeks to just a few hours. The gain is very tangible.
Griffin also thinks AI could open a particularly favorable period for entrepreneurs. Small companies will be able to automate functions once reserved for much wealthier groups. However, not all currently valued players as future winners will probably survive.
This is where his parallel with the Internet bubble makes perfect sense. Internet technology did not disappear after 2000. It became much more important. But a large part of the companies considered revolutionary at the time disappeared.
The survivors took a huge lead. Griffin thinks the same scenario can happen with AI. Companies that survive a possible correction could become market leaders for the coming decades.
The current risk mainly comes from the gap between investments and the revenue still generated. The debate intensified this year despite Nvidia’s impressive results. In February, their performance had already reignited questions about the sustainability of massive AI spending. Griffin gives no date for a burst. He also does not advise selling AI-related stocks. His warning is simpler: a technology can truly transform the world and be, at the same time, at the heart of a financial bubble. The Internet has already shown that.
Maximize your Cointribune experience with our "Read to Earn" program! For every article you read, earn points and access exclusive rewards. Sign up now and start earning benefits.
Join the program
A
A
Lydie M.
Enseignante et ingénieure IT, Lydie découvre le Bitcoin en 2022 et plonge dans l’univers des cryptomonnaies. Elle vulgarise des sujets complexes, décrypte les enjeux du Web3 et défend une vision d’un futur numérique ouvert, inclusif et décentralisé.
DISCLAIMER
The views, thoughts, and opinions expressed in this article belong solely to the author, and should not be taken as investment advice. Do your own research before taking any investment decisions.