South Korea's cumulative auto insurance loss ratio, which had been climbing through this year, turned lower on a year-on-year basis for the first time in September. The improvement reflects a sharp drop in rainfall and lower highway traffic volume, both of which reduced accident risk. Still, concerns remain that the ratio could deteriorate again as fall travel picks up and vehicle repair costs rise.
The four major non-life insurers — Samsung Fire & Marine Insurance, DB Insurance, Hyundai Marine & Fire Insurance and KB Insurance — posted a simple average cumulative auto insurance loss ratio of 84.7% for January through September, the non-life insurance industry said on the 23rd. That is 0.76 percentage point lower than the 85.46% recorded a year earlier. The cumulative ratio had stayed above year-earlier levels through the end of August before turning lower in September. As of the end of August, the cumulative ratio stood at 84.7%, 0.3 percentage point higher than the 84.4% a year earlier.
The shift was driven largely by a sharp improvement during September alone. The four insurers' monthly loss ratio averaged 84.97% in September, down 9.23 percentage points from 94.20% in the same month last year. That is the largest year-on-year decline for any month this year.
Seasonal factors, including lower rainfall, contributed to the improvement. Rainfall in September totaled 26.4 millimeters, about one-ninth of the 228.8 millimeters recorded in the same month last year. With torrential September downpours far less frequent than a year earlier, risks tied to severe weather — such as accidents on wet roads and flooded vehicles — declined.
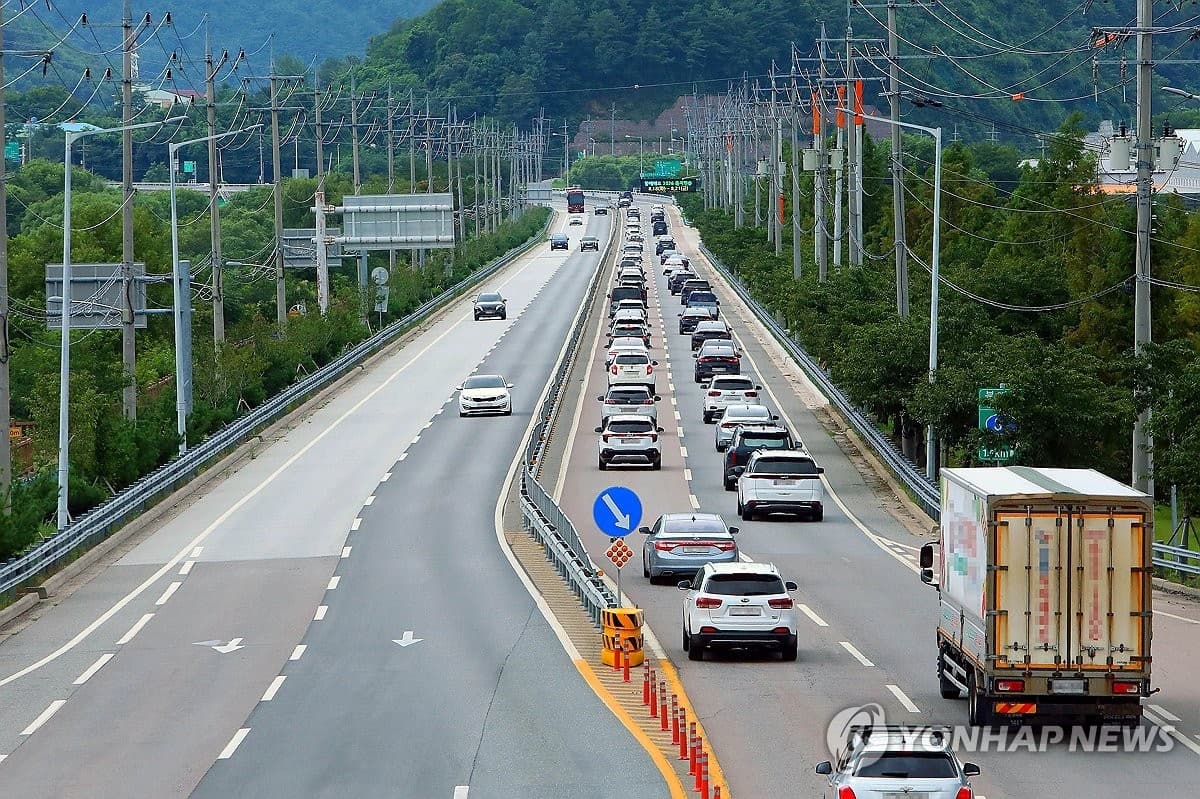
Lower traffic volume was also cited as a factor. Highway traffic totaled 265.03 million vehicles in September, down about 7.1% from 285.38 million in the same month last year. The industry estimates that less driving reduced the likelihood of accidents.
Whether the improvement will hold through year-end remains uncertain. As foliage season peaks in October, increased travel by fall sightseers could lift both the number of traffic accidents and the cost of injuries per accident. Factors pushing up the cost of claims payouts, including higher auto repair rates and wages for daily-hire workers, also remain in place.
Non-life insurers are concerned the loss ratio could worsen again. The break-even point for auto insurance at major non-life insurers is generally put in the low 80% range, meaning profitability pressure persists even with the cumulative ratio falling in September.