The amount young South Koreans borrowed from banks through mortgages rose this year, but the loans covered a smaller share of the value of the homes they pledged as collateral. Analysts warn that rising home prices and tighter lending rules together could force young buyers to put up more of their own money.
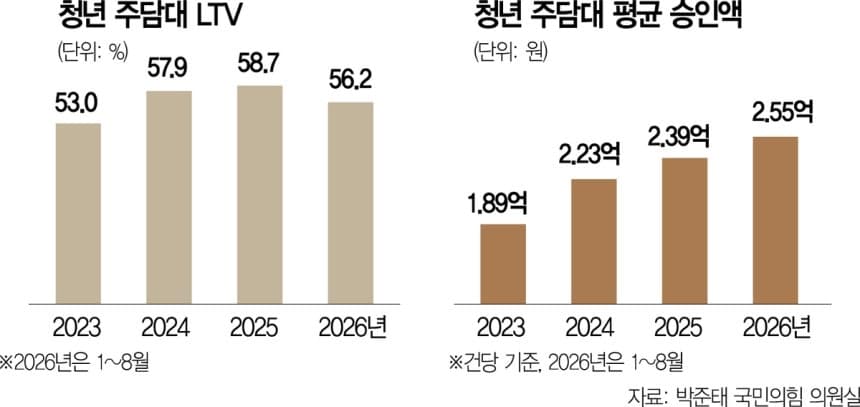
The average loan-to-value (LTV) ratio on mortgages extended to young borrowers by domestic banks stood at 56.2% from January through August this year, according to Financial Supervisory Service data submitted to Park Jun-tae, a lawmaker of the People Power Party who sits on the National Assembly's National Policy Committee. The data was released on the 21st. That is down 2.5 percentage points from 58.7% last year.
It is the first annual decline in the average LTV on mortgages for young borrowers since 2022. The ratio climbed steadily from 42.7% in 2022 to 53.0% in 2023, 57.9% in 2024 and 58.7% last year, before the upward trend broke this year. Mortgages for newlyweds moved in the opposite direction, with the average LTV rising 1.3 percentage points to 65.1% this year from 63.8% last year.
The LTV ratio measures how much has been lent against the appraised value of a home. A lower ratio means the approved loan accounts for a smaller portion of that value. "A drop in the LTV ratio means young people may not have been able to borrow enough to buy a home," an official at a commercial bank said. "Their funding burden appears to be growing."
While the lending-capacity measure worsened, the amount approved per loan increased. Mortgages approved for young borrowers totaled 22.1 trillion won ($15.4 billion) from January through August, across 86,536 approvals, or about 255 million won per loan. That is roughly 7% higher than last year's average of 239 million won.
The average approval per mortgage for young borrowers has risen every year, from 170 million won in 2022 to 189 million won in 2023, 223 million won in 2024 and 239 million won last year, extending the increase to a fourth straight year through this year. Loan sizes have grown, yet the share of collateral value they represent has shrunk.
Financial industry officials point to rising home prices and successive rounds of tighter lending rules as possible drivers of the shift. "Home prices have kept rising, and lending curbs aimed at reining in that increase have continued throughout the year," an official in the financial sector said. "Various policies chosen to stabilize the market appear to have combined to push down the share of collateral value young people could borrow against."
Income gaps within the younger age group may also have affected loan approvals. Higher-earning young borrowers were able to take out relatively large loans, while those with lower incomes may have struggled to win approval or received smaller amounts, according to this analysis. "It looks like only those who could borrow did, and those who could not found it even harder," another official in the financial sector said. "People with high salaries borrowed more, while low-income groups may have been unable to borrow at all or were approved for only very small amounts."
A gauge of the debt-servicing burden relative to income has also turned higher. The average debt service ratio (DSR) on mortgages for young borrowers rose 1.1 percentage points to 32.5% from January through August this year, from 31.4% last year. The average DSR had declined steadily from 39.7% in 2022 to 37.4% in 2023 and 33.4% in 2024 before rebounding this year.