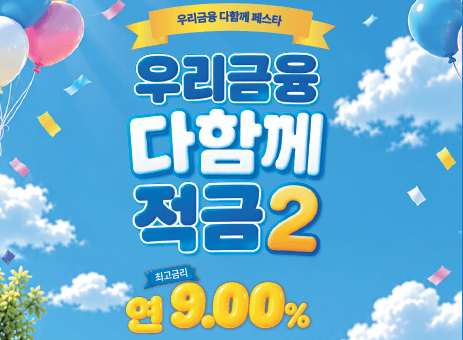
Money is flowing into Woori Bank's savings product offering an annual rate of up to 9%, as commercial banks raise deposit rates one after another.
Time deposits at South Korea's five largest banks stood at 1,007.5 trillion won ($706 billion) at the end of last month, up 58 trillion won from the end of June, according to financial industry data on the 15th. The balance, which was around 939 trillion won at the end of last year, declined through the first quarter before turning higher in the third quarter as stock market volatility eased.
The inflows reflect aggressive rate increases by banks amid a broader uptrend in interest rates. After the Bank of Korea lifted its base rate to 3.0%, one-year deposit rates at major banks climbed above 3.5%. Woori Bank raised the rate on its WON Plus Deposit by up to 0.2 percentage points this month, bringing the one-year rate to 3.6%. NH NongHyup Bank's NH All-One e-Deposit pays 3.65%, while Hana Bank's Hana Time Deposit offers 3.6%.
With customer interest in deposit and installment savings products growing, banks are also competing to launch special offerings with headline-grabbing rates. Woori Financial Group put high-rate products front and center at the 2026 Woori Financial Together Festa, a campaign run jointly by eight affiliates this month. Woori Bank introduced Woori Financial Together Savings 2, which carries a rate of up to 9.0%. The one-year flexible-deposit product allows contributions of up to 300,000 won a month. It pays a base rate of 3.5%, with up to 5.5 percentage points added for customers who meet certain conditions.
Woori Financial Savings Bank is selling TOK7, a seven-month installment savings product with a base rate of 7.0% and no additional conditions. Woori Investment & Securities offers 3.95% on one-year time deposits structured as issued notes for individual customers, with an extra 0.1 percentage point for those who sign up online.
"The structures differ from product to product, so it is hard to compare them on headline rates alone," an official at a commercial bank said. "You have to look at the preferential conditions and the limits as well."