Executive Summary
- Buyers from the past two years hold a cost basis above $88K, and they have turned price back twice this year.
- Bitcoin holds above the True Market Mean and has twice bounced on the US Spot ETF Cost Basis near $81.5K.
- Long-term holders have largely stopped selling at a loss, and holders in profit now outspend holders in loss, as in past recoveries.
- The ETF bid of late September did not last, and the funds are net sellers again.
- Liquidation clusters of similar size sit on both sides of price, and the largest bids on the Binance book have gathered at $80K.
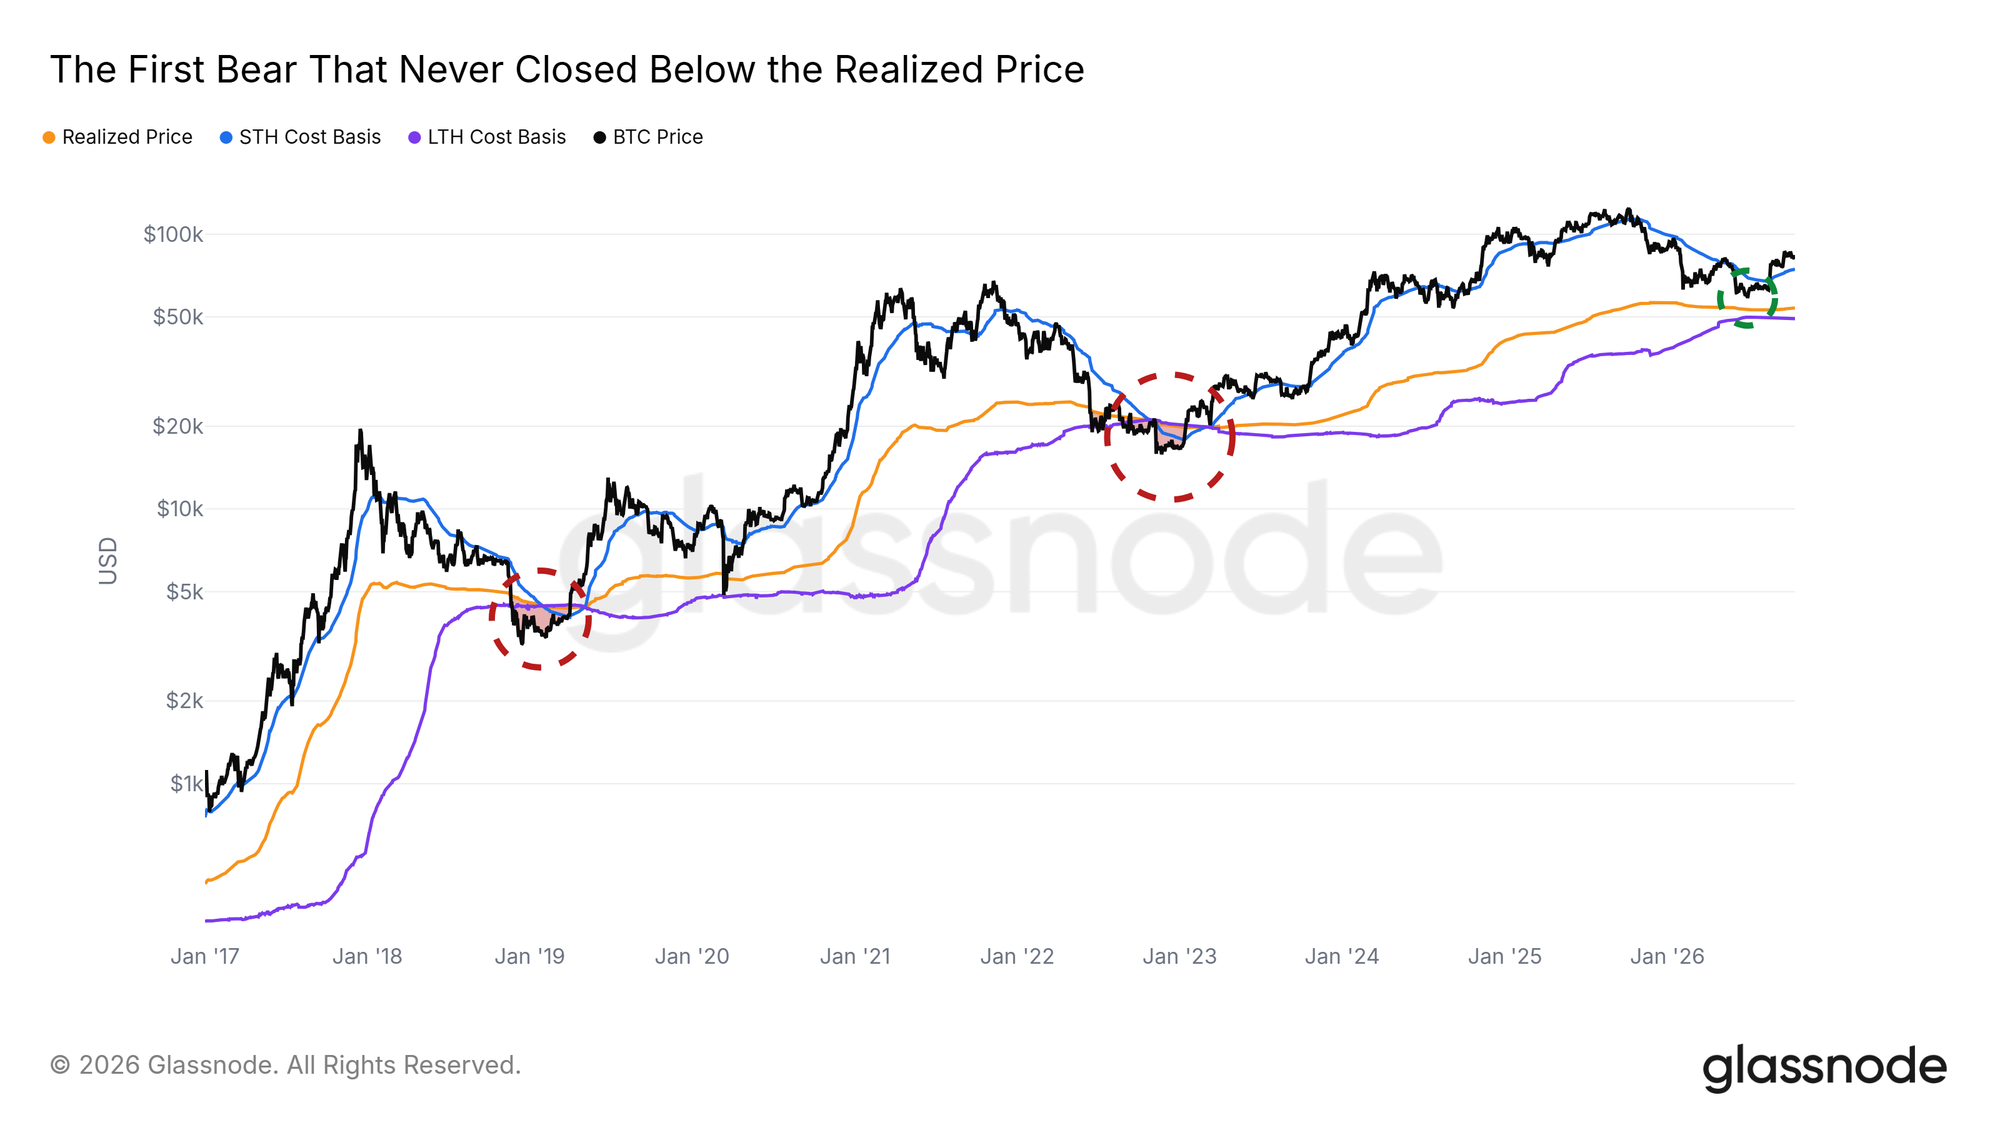
- Unlike the 2018 and 2022 bear markets, this one never closed below the Realized Price, and its low stayed far above the Long-Term Holder Cost Basis.
- September's CPI came in above forecasts, with an October rate decision and the US midterms still ahead.
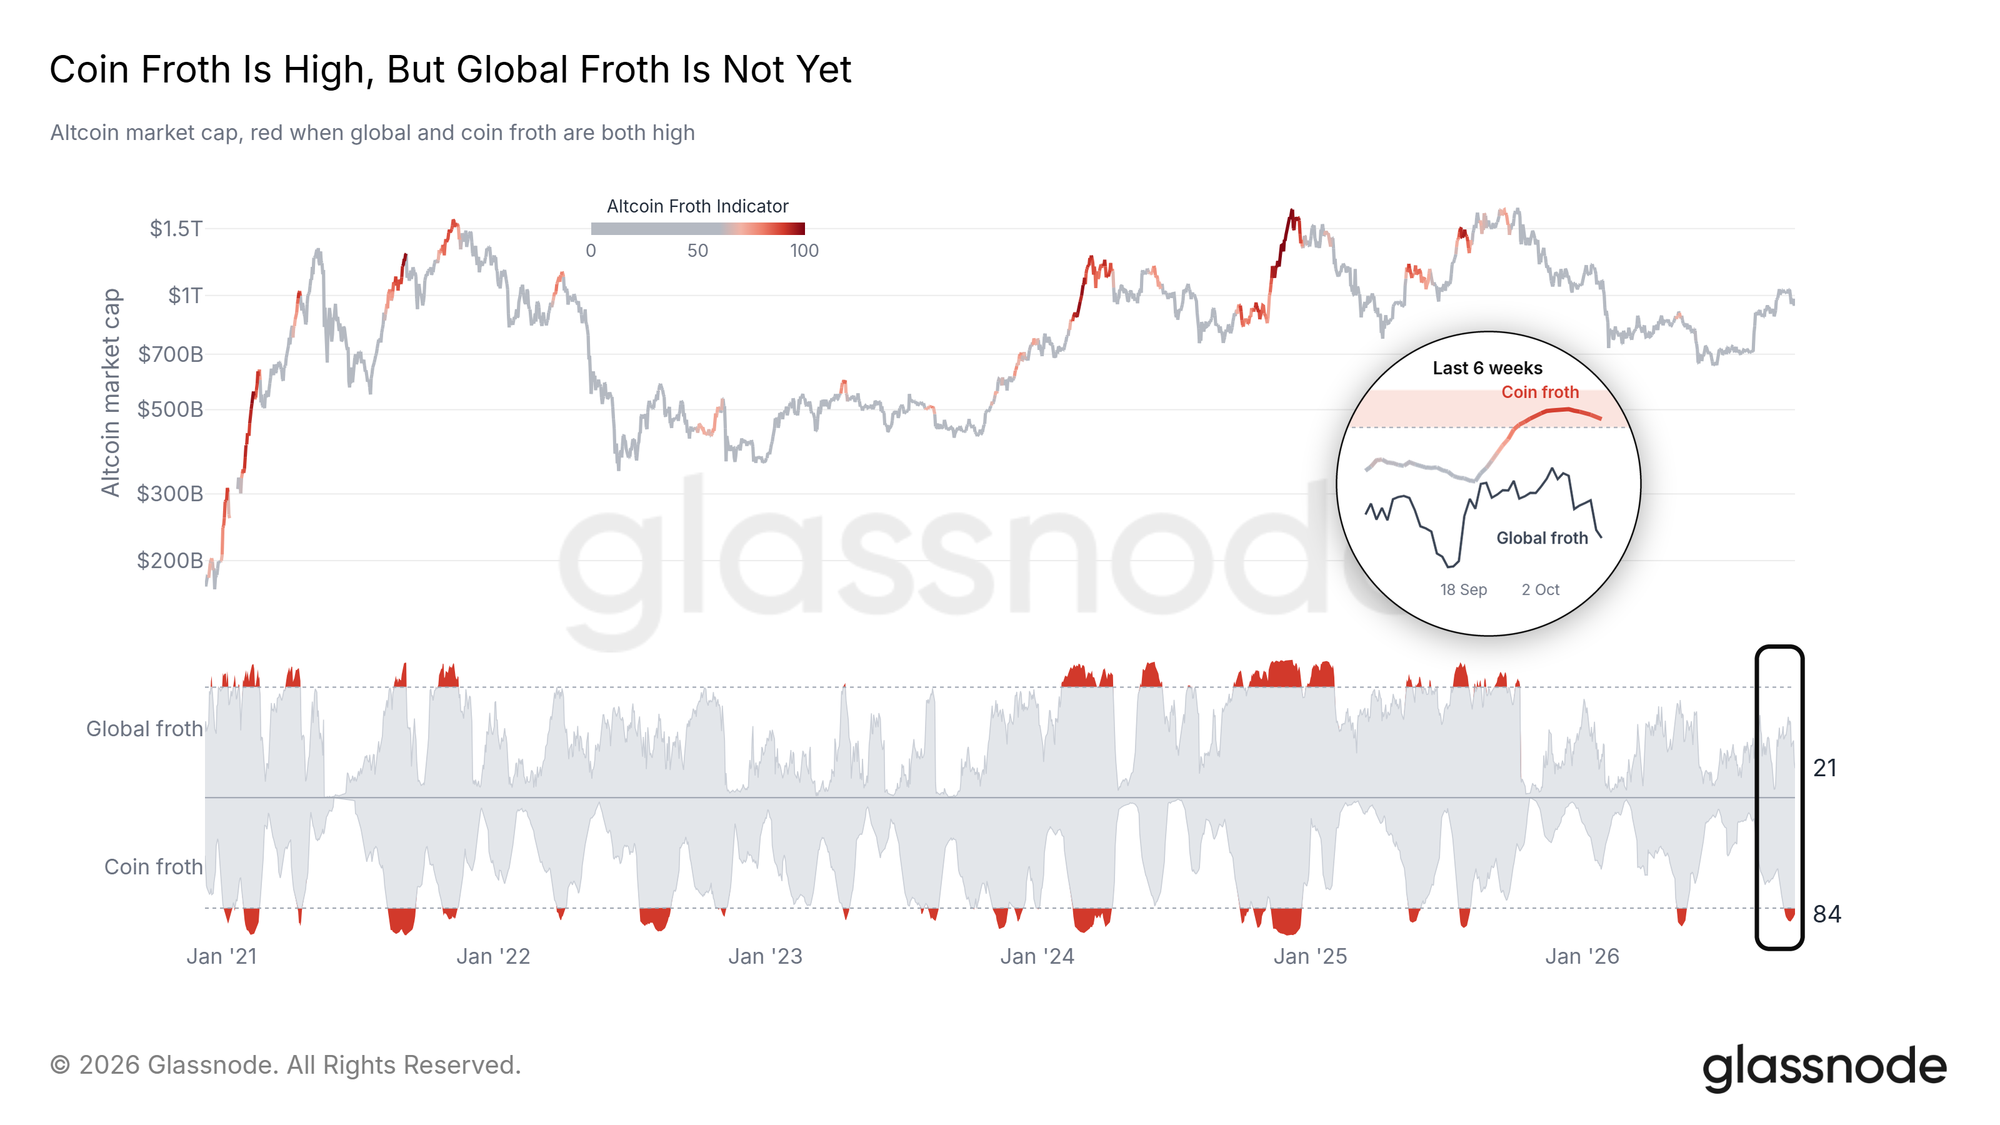
- Altcoins are frothy coin by coin, but froth across the whole market is still low.
Ready to get ahead of markets and sharpen your foresight? Try Glassnode. Sign up or talk to sales.
Stuck Under the Top Buyers
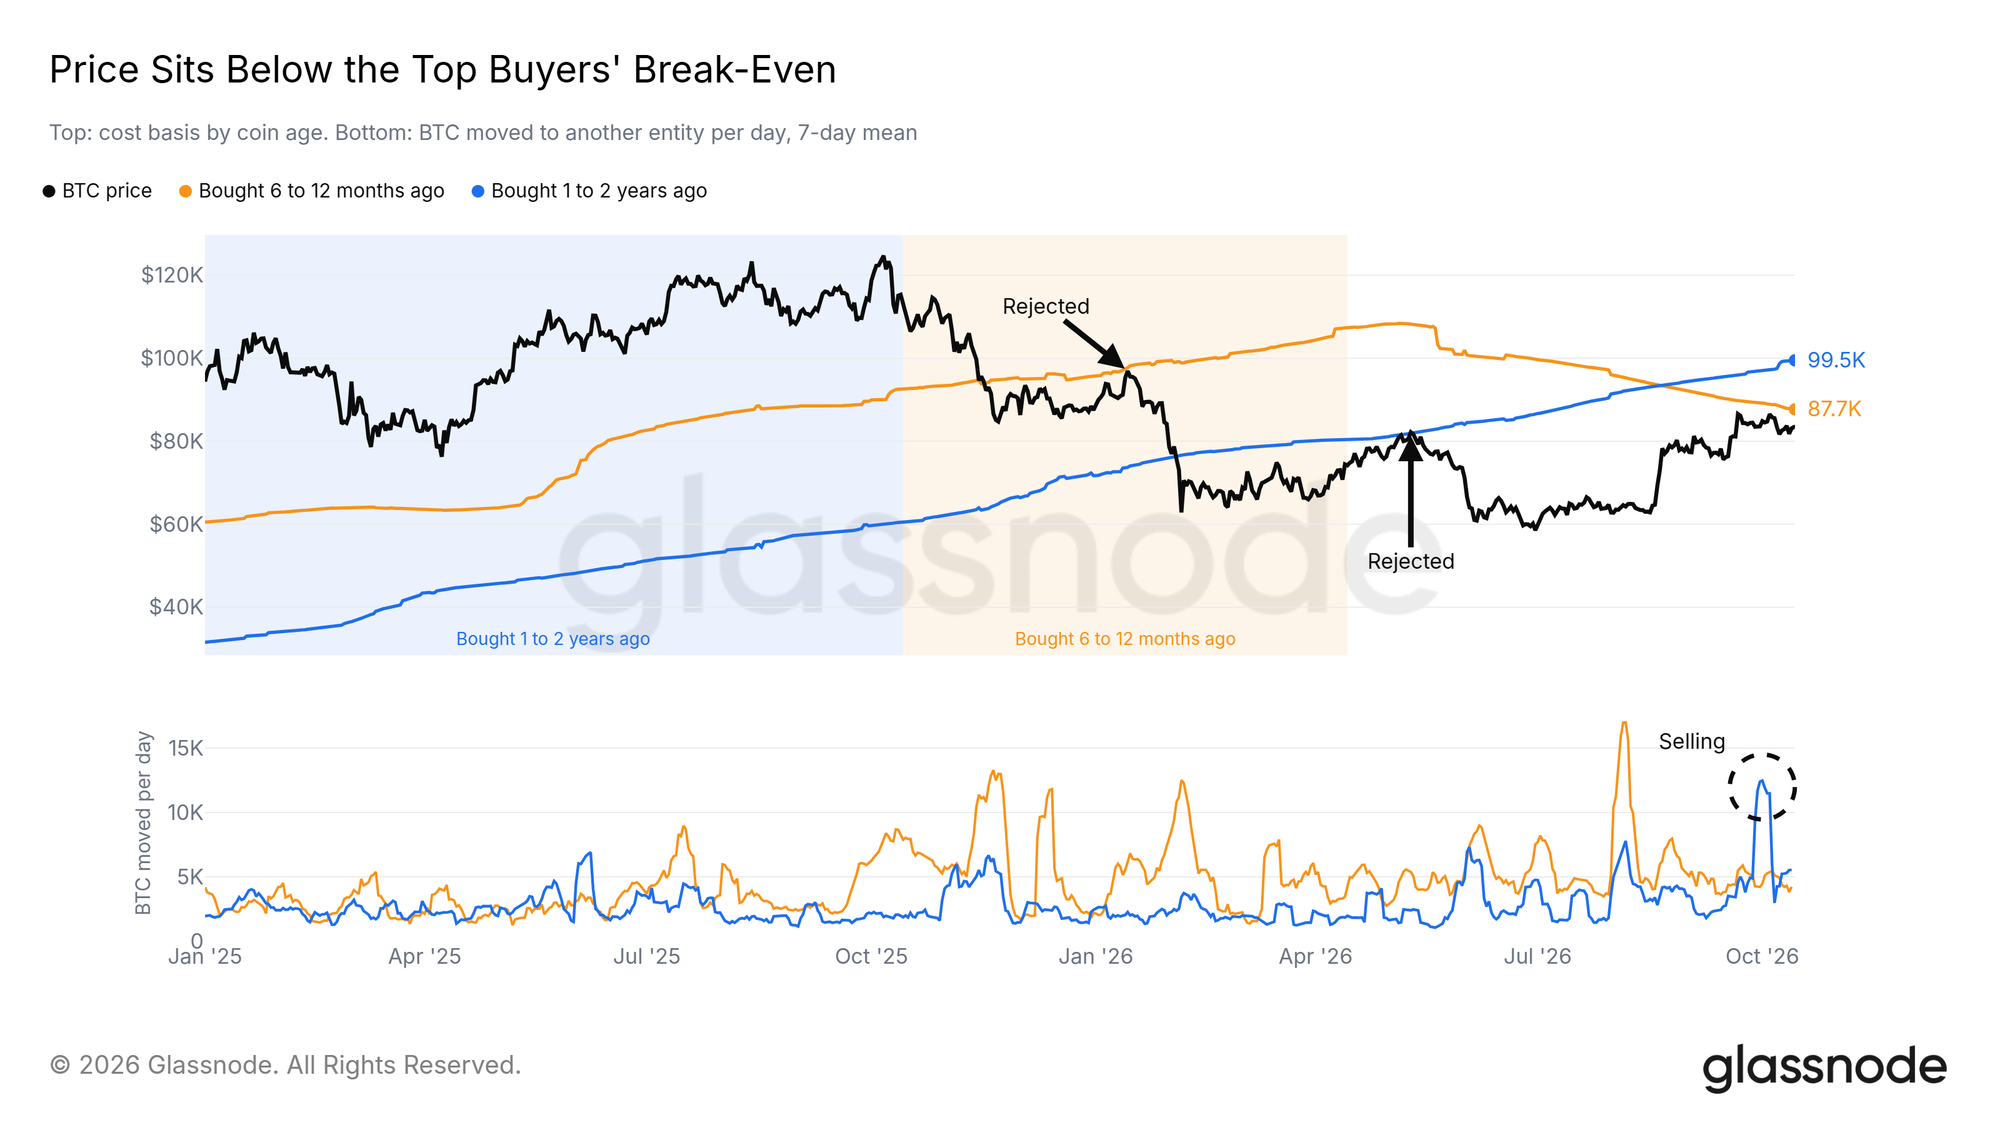
Two large groups of holders sit above price. Coins bought 6 to 12 months ago, in the late stage of the 2025 rally and the decline that followed, have a cost basis of about $88K. Coins bought 1 to 2 years ago sit higher still, near $100K.
Both lines have already turned price back this year. Bitcoin rose to the 6-12 month cost basis in January and then fell by more than a third. It met the 1-2 year cost basis in May and fell by about a quarter. The 1-2 year holders also stepped up their selling into the rally at the start of October.
Until Bitcoin closes above $88K, each push higher meets holders who can sell near their break-even.
Holding Above the Cost Bases
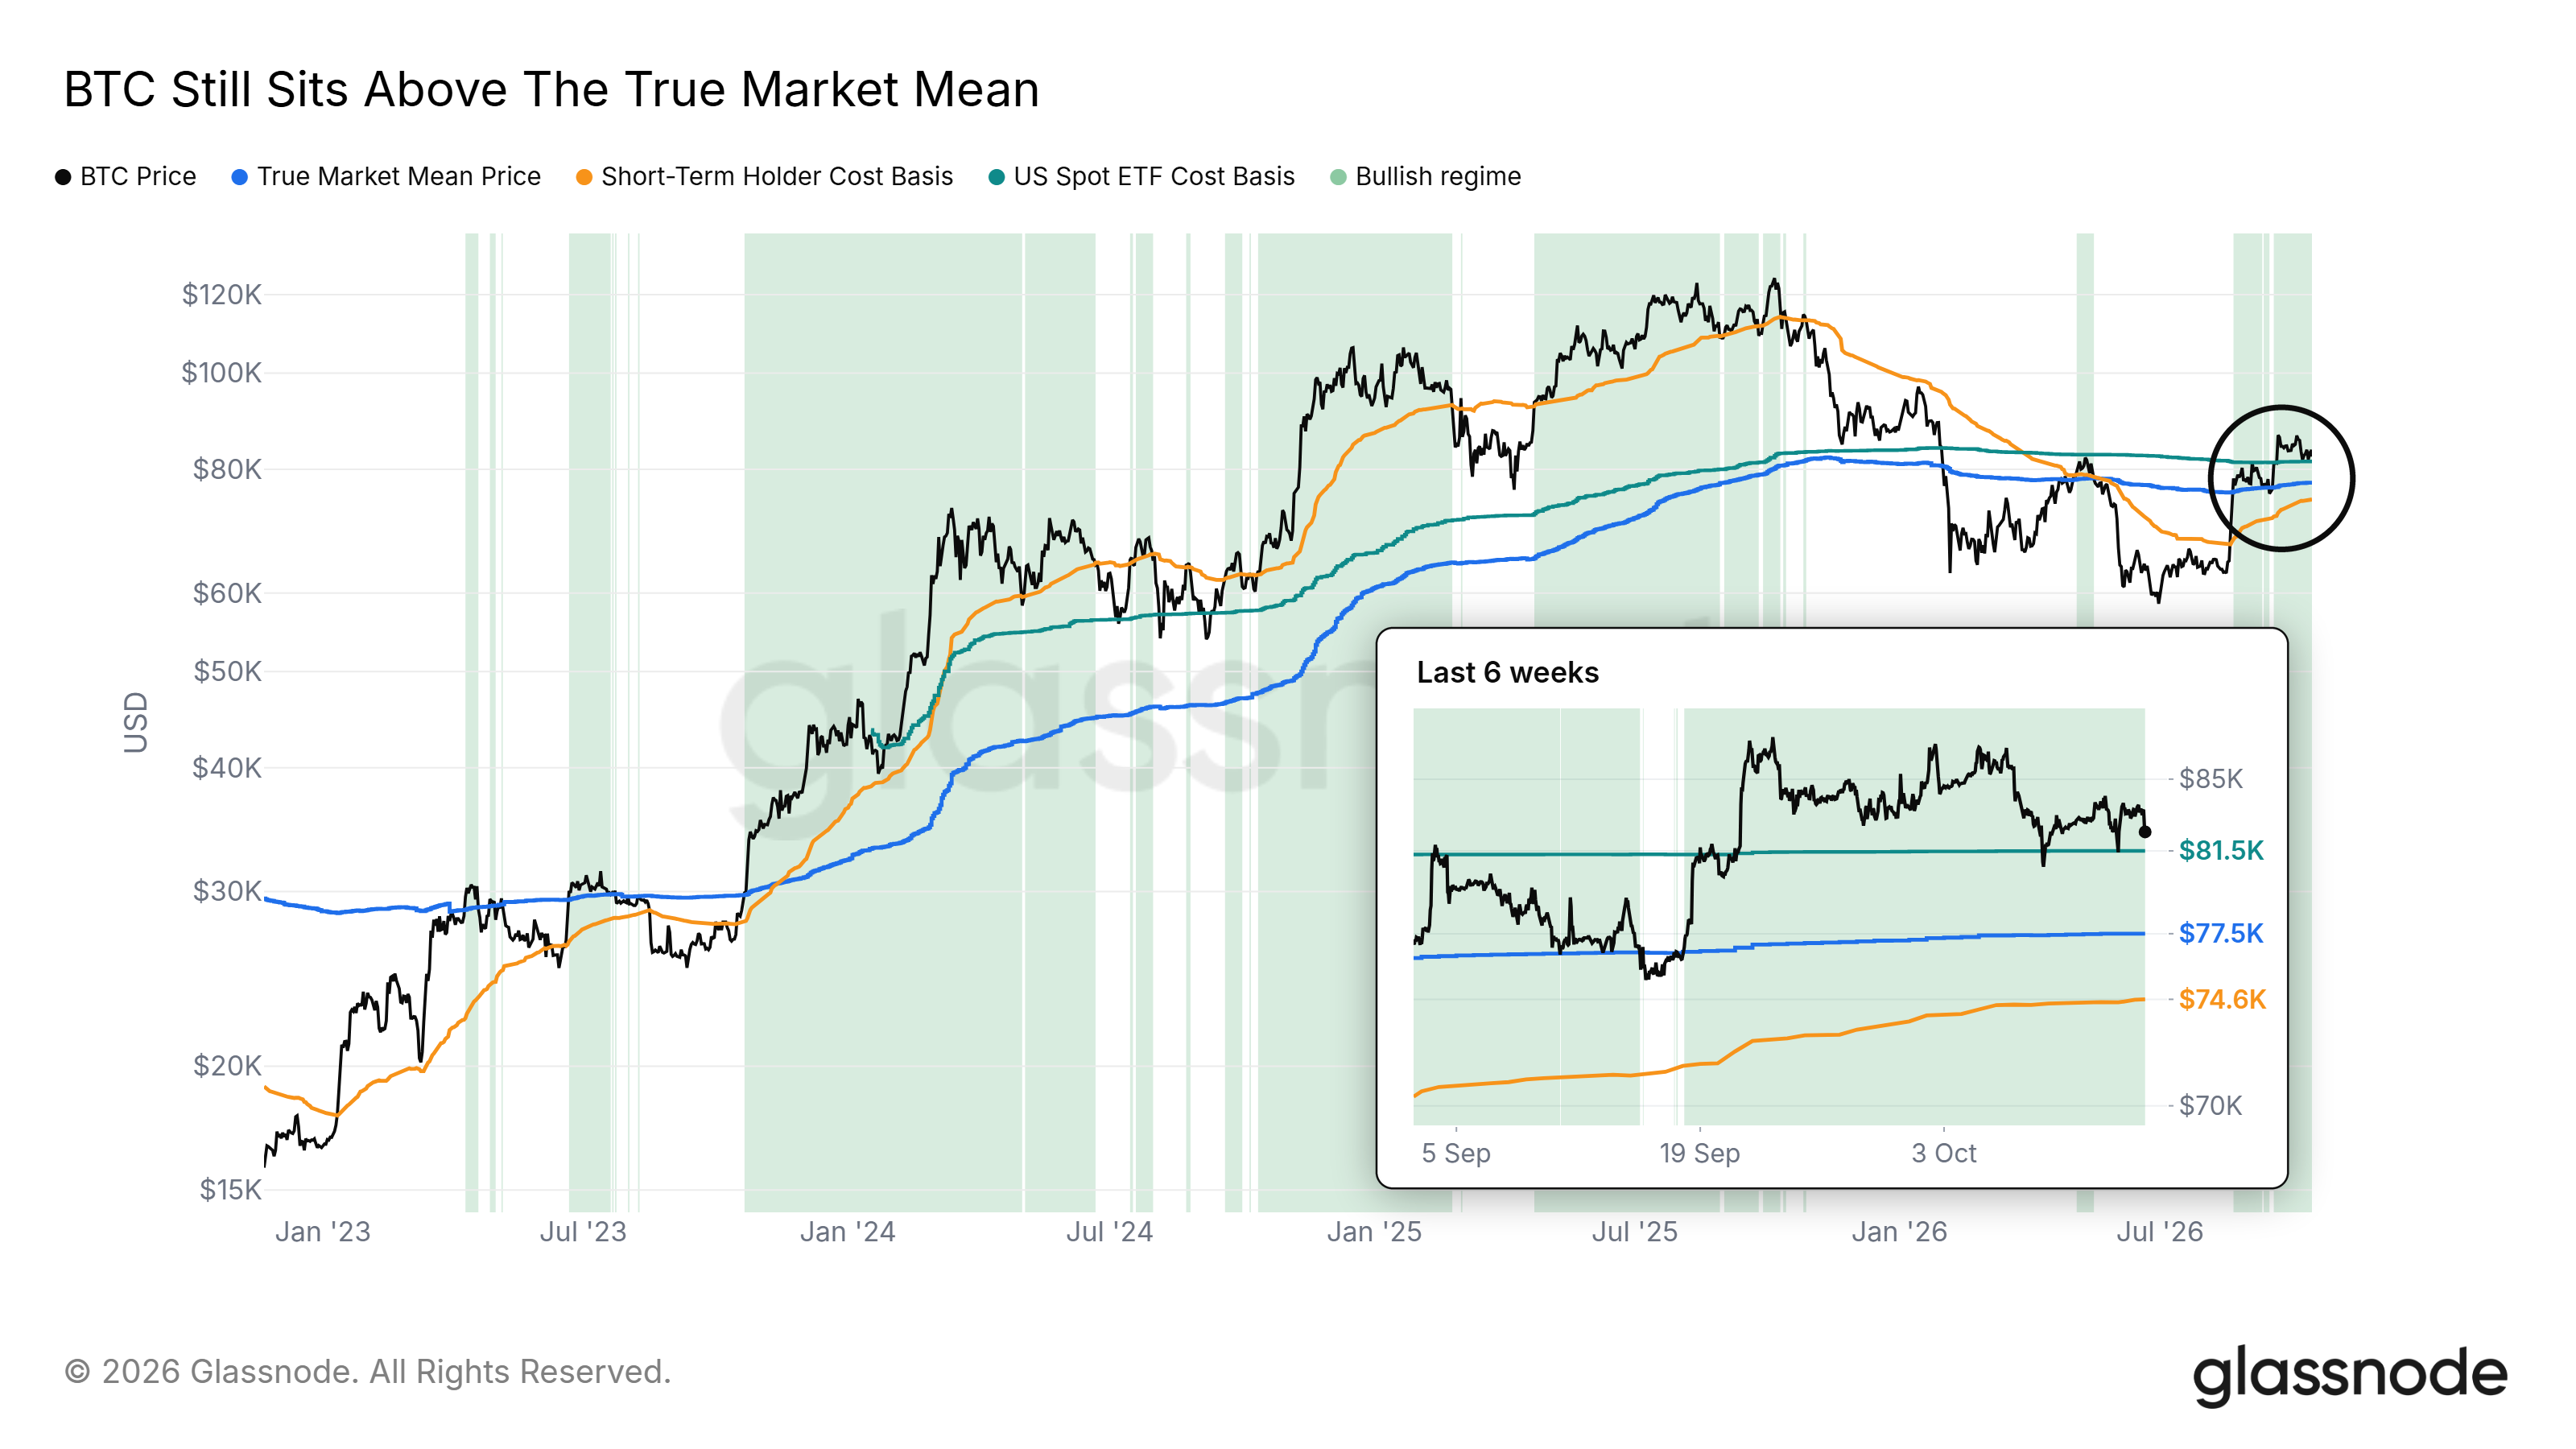
Bitcoin trades above the True Market Mean, the average cost basis of active investors, near $78K, and further above the Short-Term Holder Cost Basis. Price has held above both since September 18, the stretch the chart shades as the bullish regime.
A third line now sits closer to price: the US Spot ETF Cost Basis, the average price the US spot ETFs paid for the coins they hold, at about $81.5K. Bitcoin dipped under it on October 8 and again on October 13, and both days closed back above it. Every daily close since September 21 has held above this line.
A daily close below it would put the average ETF holder back at a loss and remove the nearest on-chain support.
Losses Have Dried Up
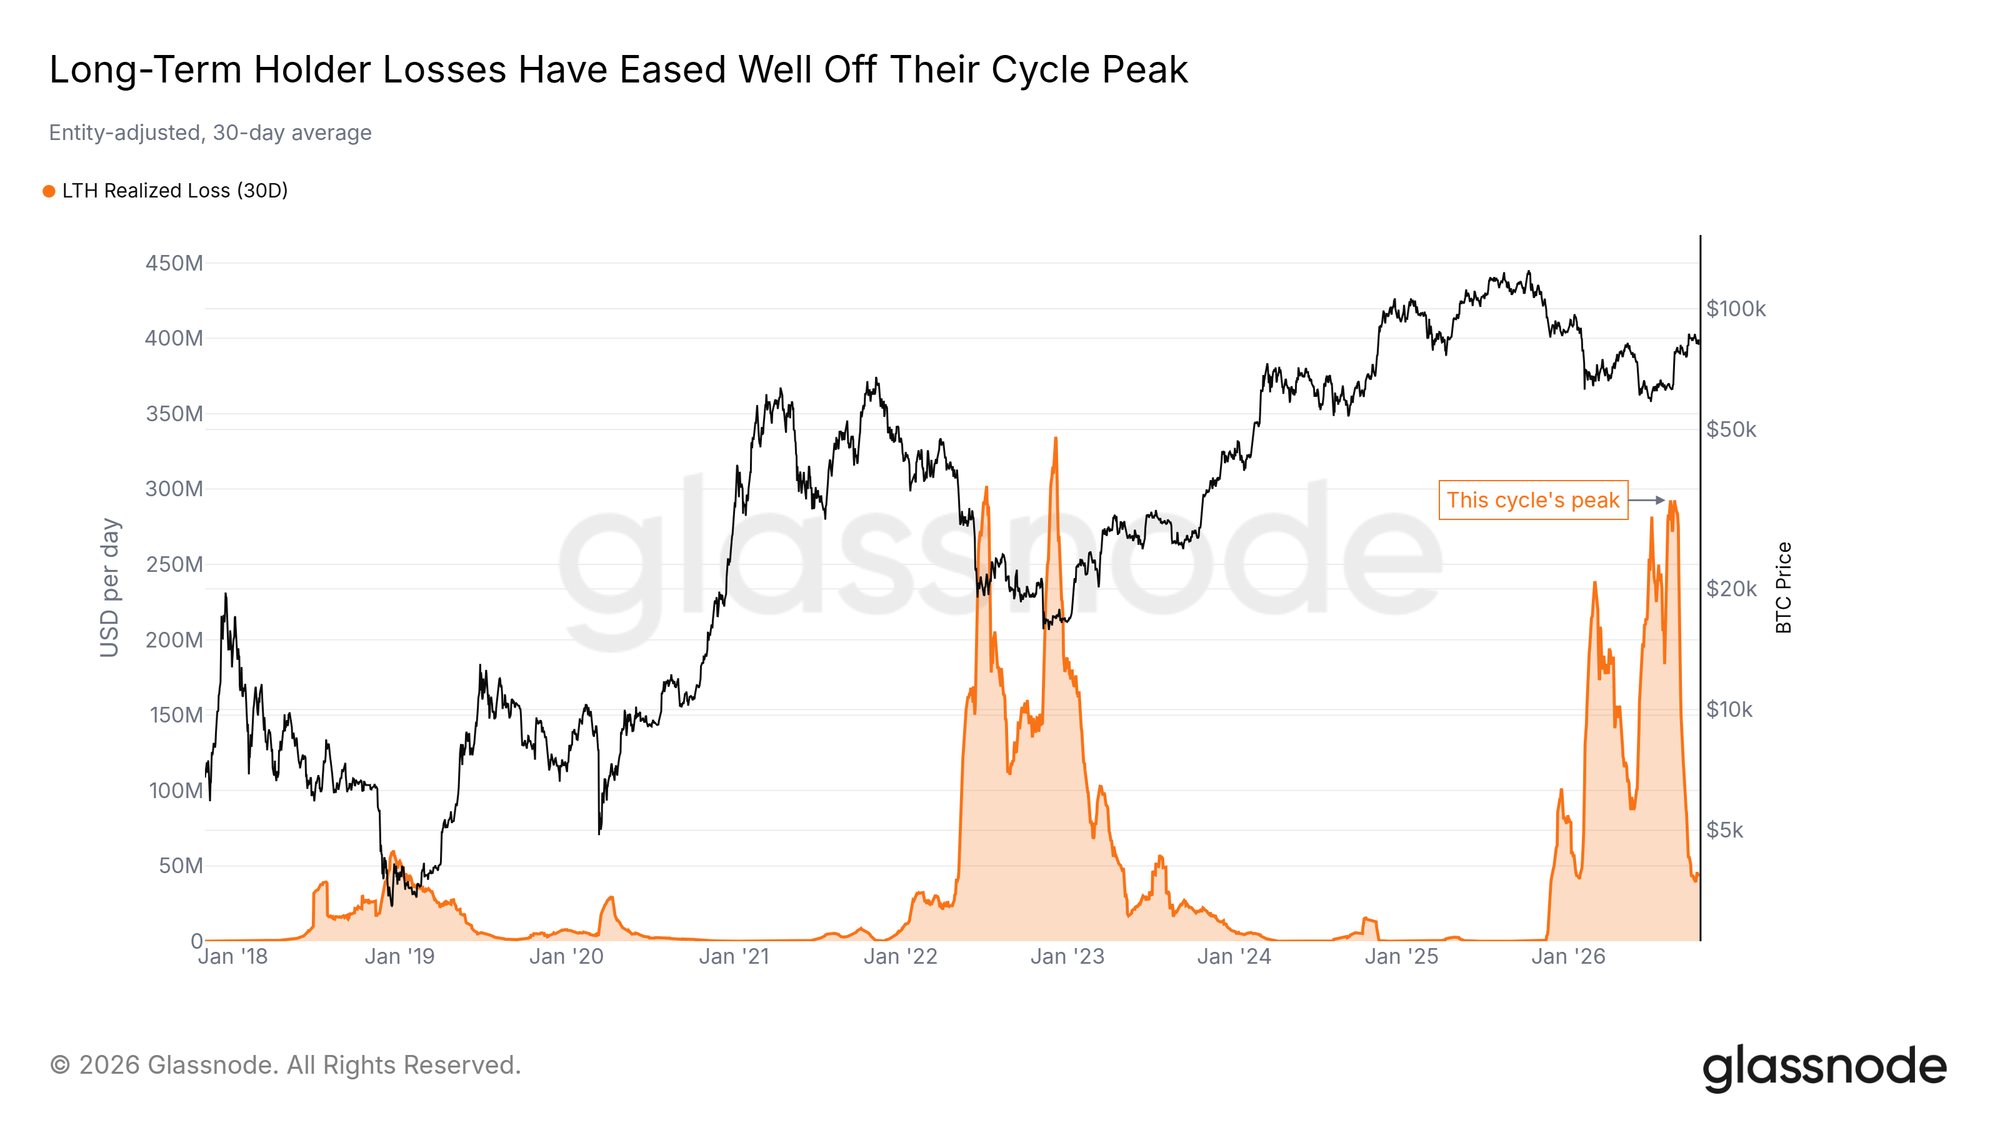
Long-term holders have largely stopped selling at a loss. Their Realized Loss peaked on August 12 and has since fallen by about 85%. In 2022, the peak in these losses came within weeks of the cycle low.
With that selling mostly done, the coins that change hands are increasingly sold at a profit.
Profit Takers Lead Again
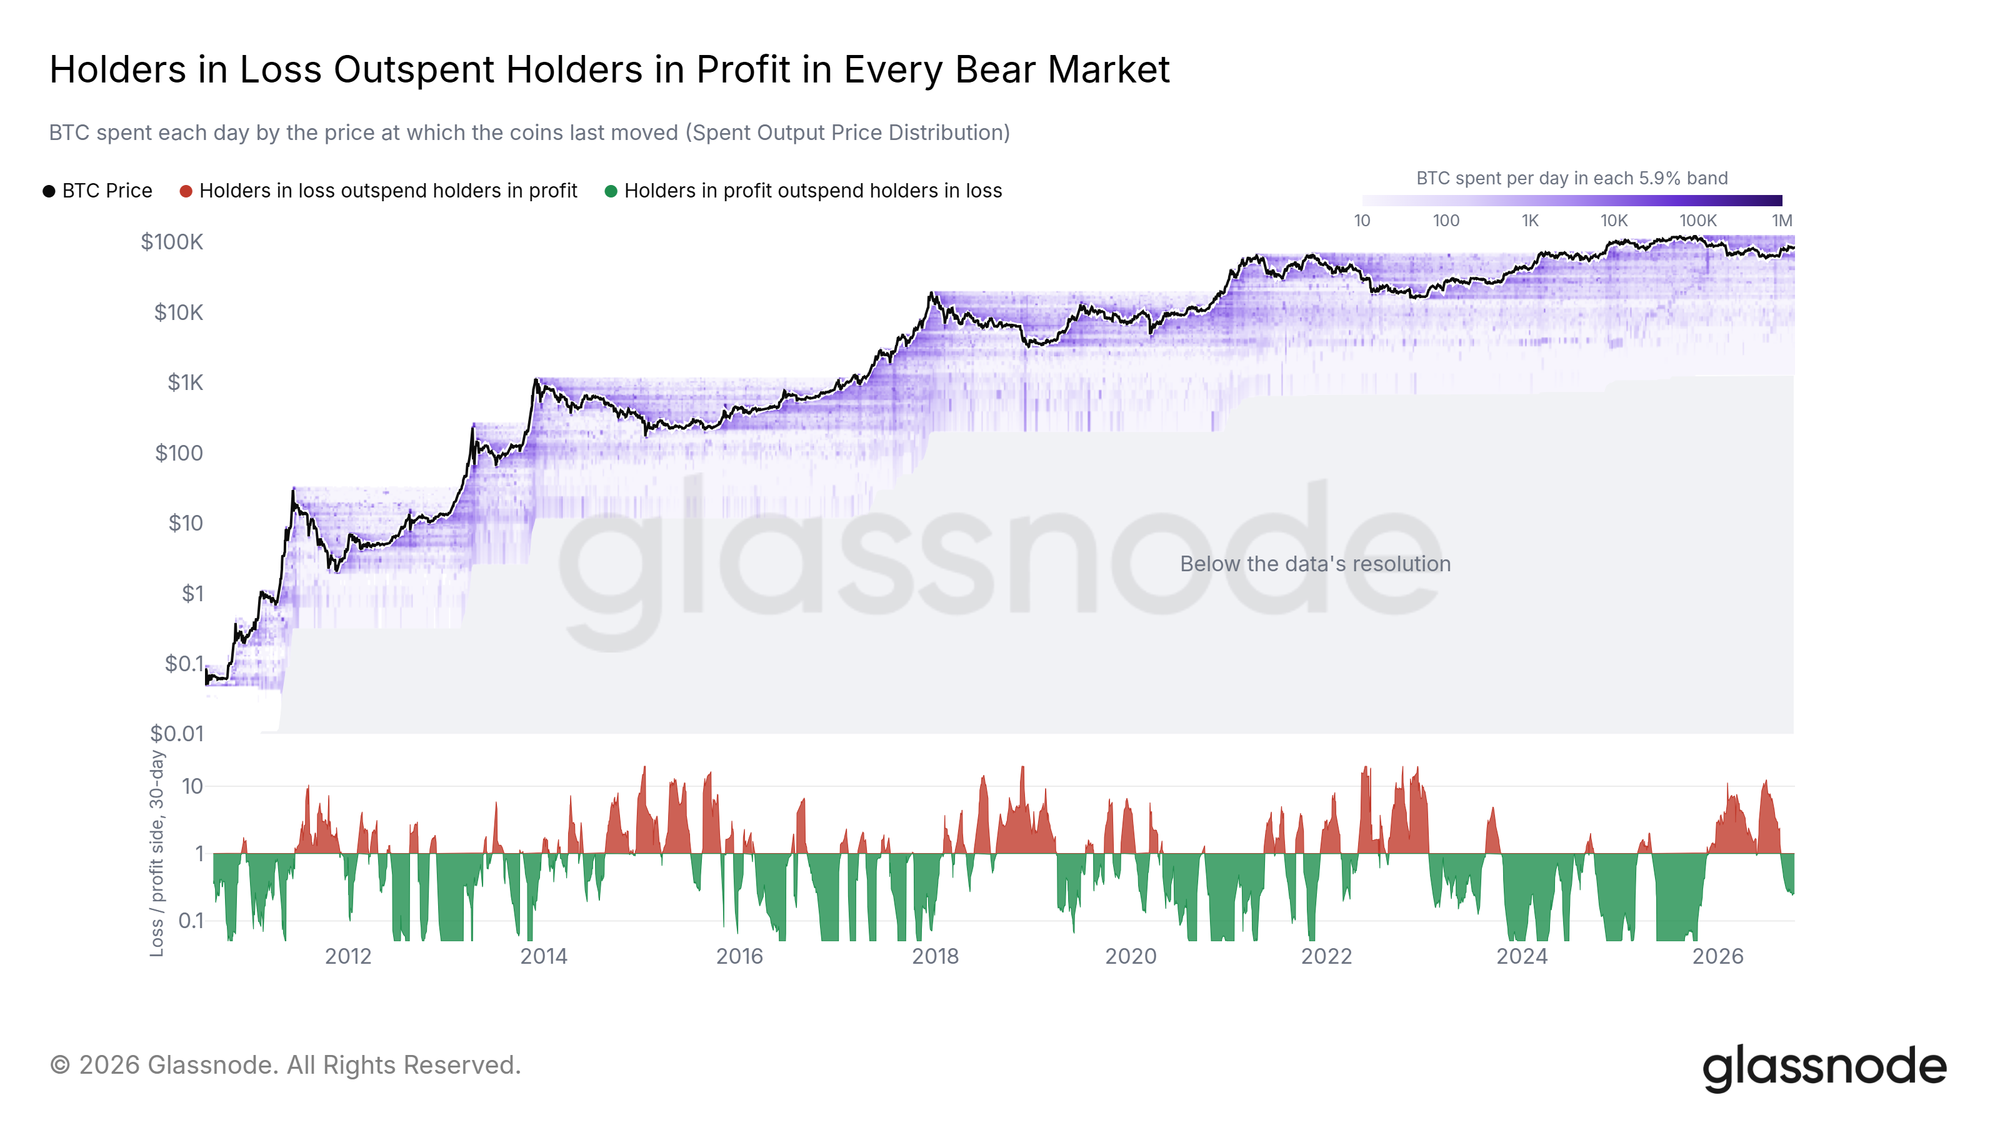
The Spent Output Price Distribution sorts each day's spent coins by the price at which they last moved, so it shows where today's supply comes from. In every bear market since 2011, holders in loss spent more coins than holders in profit, and in every bull market the reverse held. At the June low, coins spent at a loss outnumbered coins spent in profit by about twelve to one.
The balance flipped in late August. Holders in profit now spend about four coins for every coin spent at a loss. Profit-taking can slow a rally, but the same balance held through every past bull market.
The ETFs Turn Sellers Again
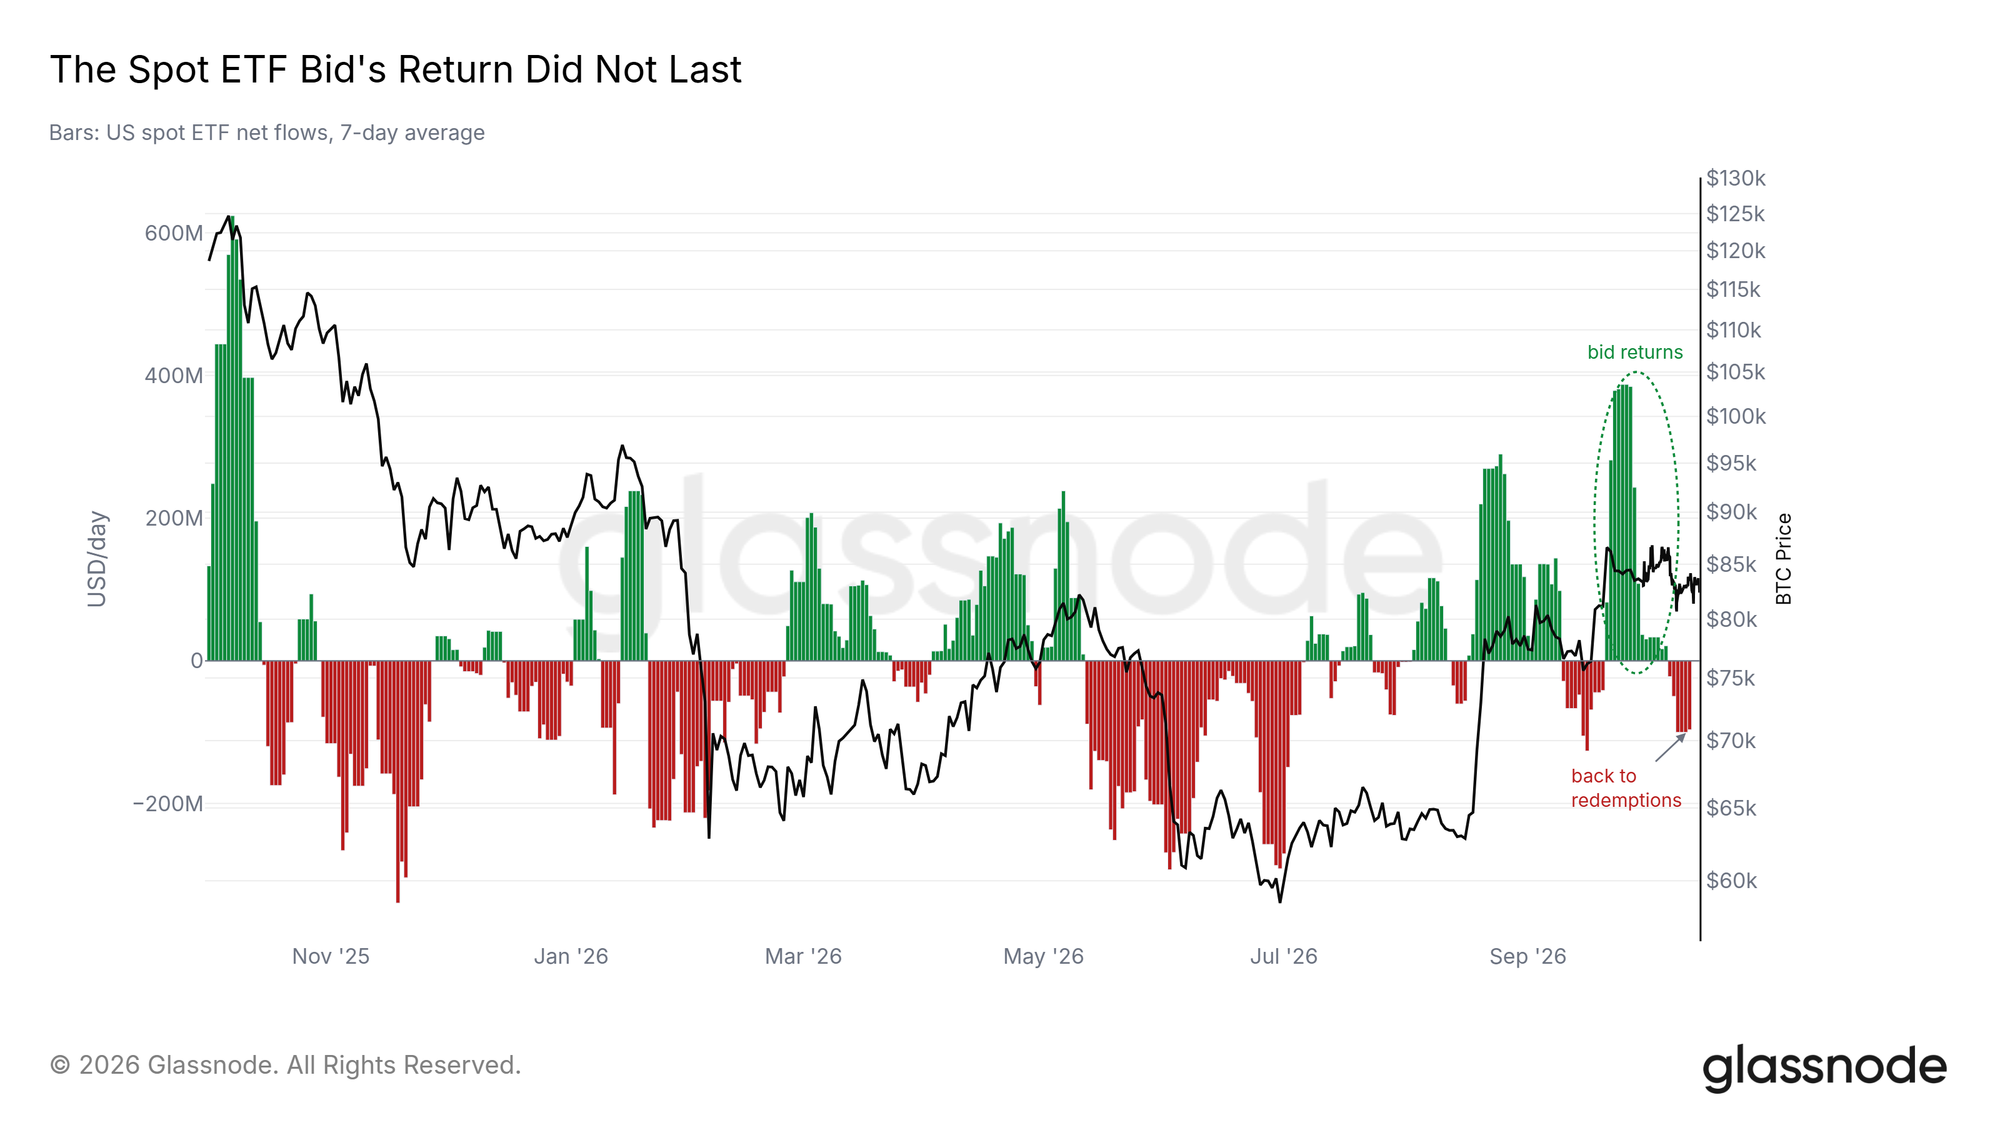
The US spot ETFs bought heavily as Bitcoin broke above $85K in late September. Between September 21 and October 6, they took in nearly $3B, their fastest pace of buying since November 2025.
That bid has not lasted. Since October 7, the funds have seen about $760M of net outflows. With the ETFs selling and the top buyers selling near their break-even, there is little fresh demand behind price. A return to steady ETF inflows would be the clearest sign that demand is back.
Levels on Both Sides
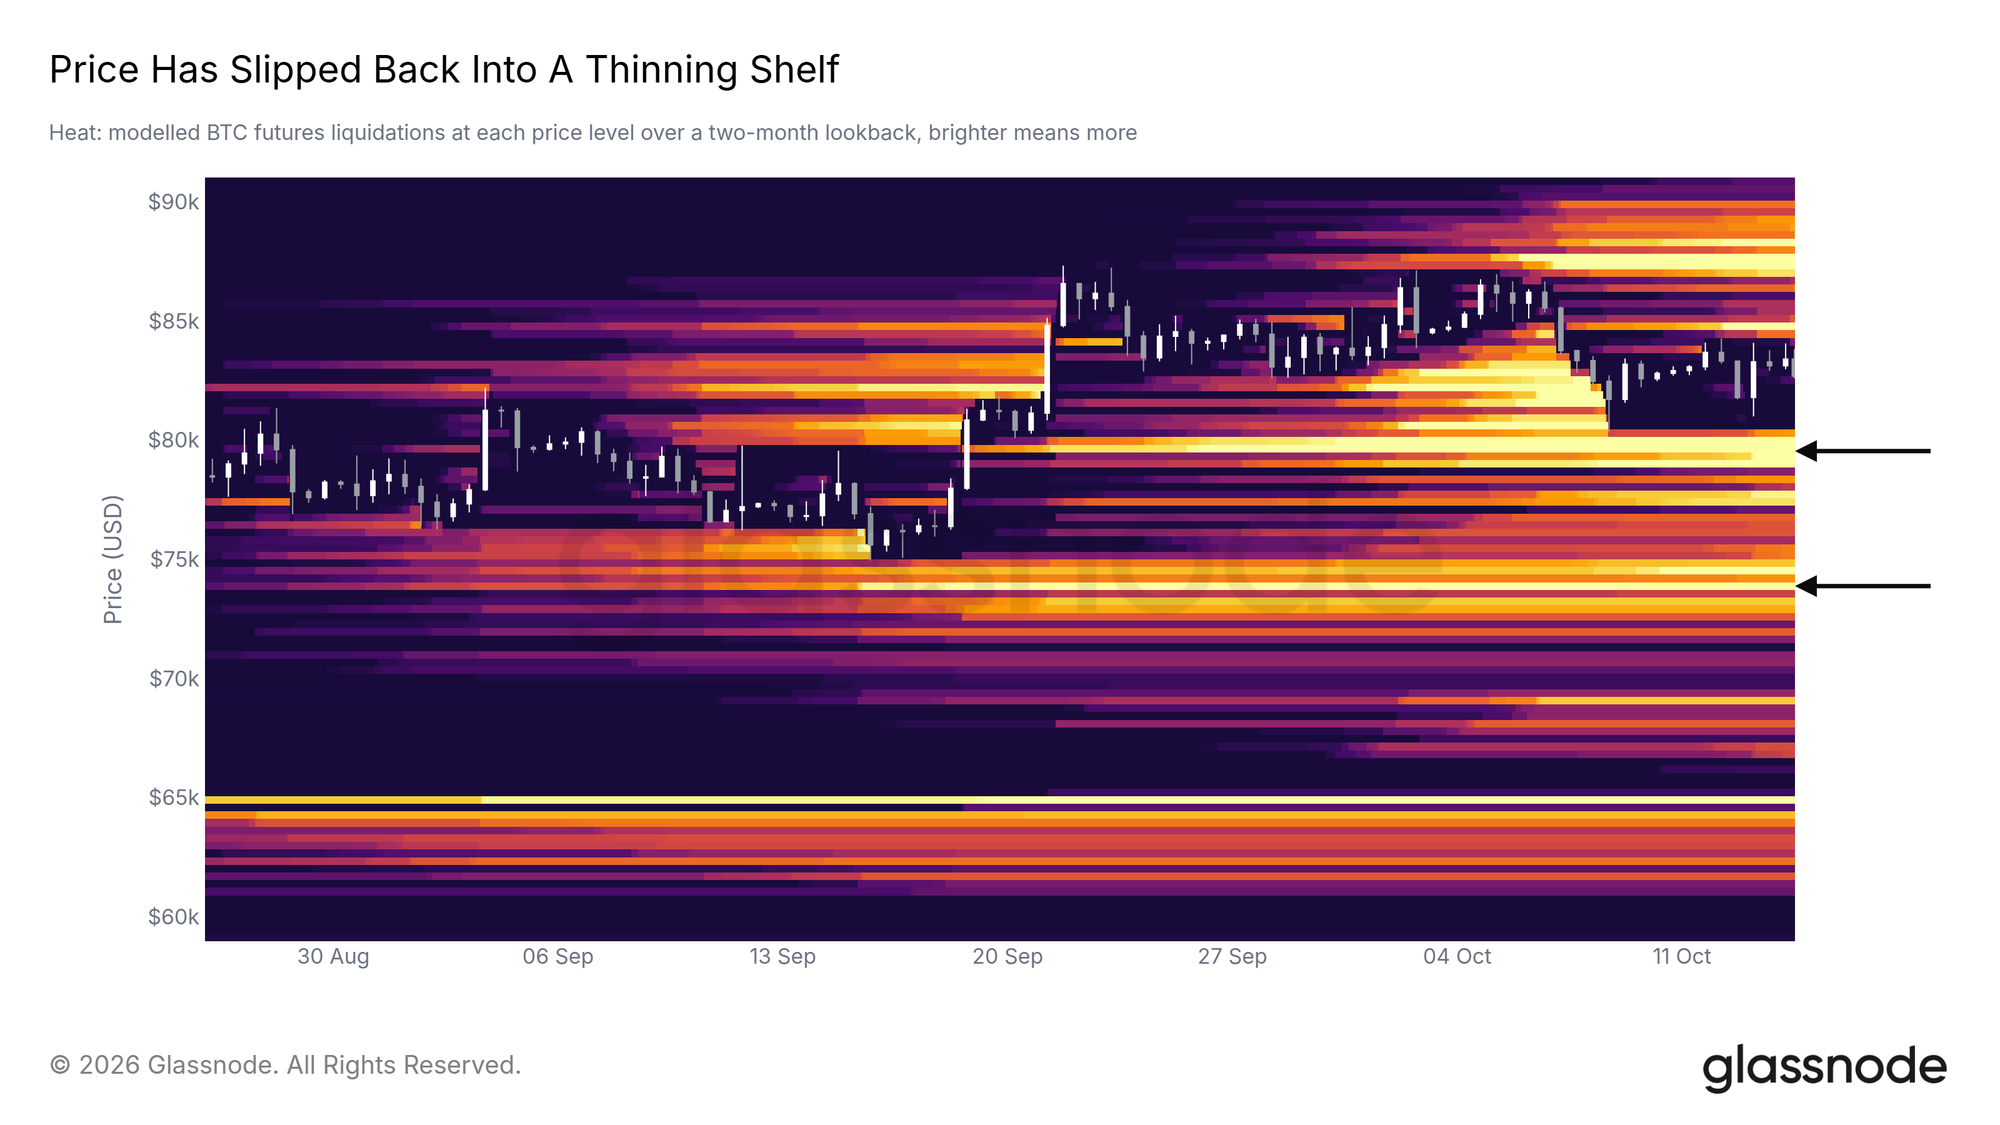
Futures positioning leaves room for moves in both directions. On the two-month liquidation heatmap, which models where leveraged positions would be forced to close, the shelf of levels around price has thinned by more than a fifth in a week. The largest clusters now sit further out, and they are about the same size: one just under $80K, the other near $88K.
Should price slip below $80K, forced selling of long positions could deepen the drop. A push up into the cluster near $88K, right at the 6-12 month cost basis, could force short sellers to buy back and carry price higher for a time. Without spot demand behind it, such a squeeze would run into the top buyers' selling and would be hard to hold.
Bids Gather at $80K
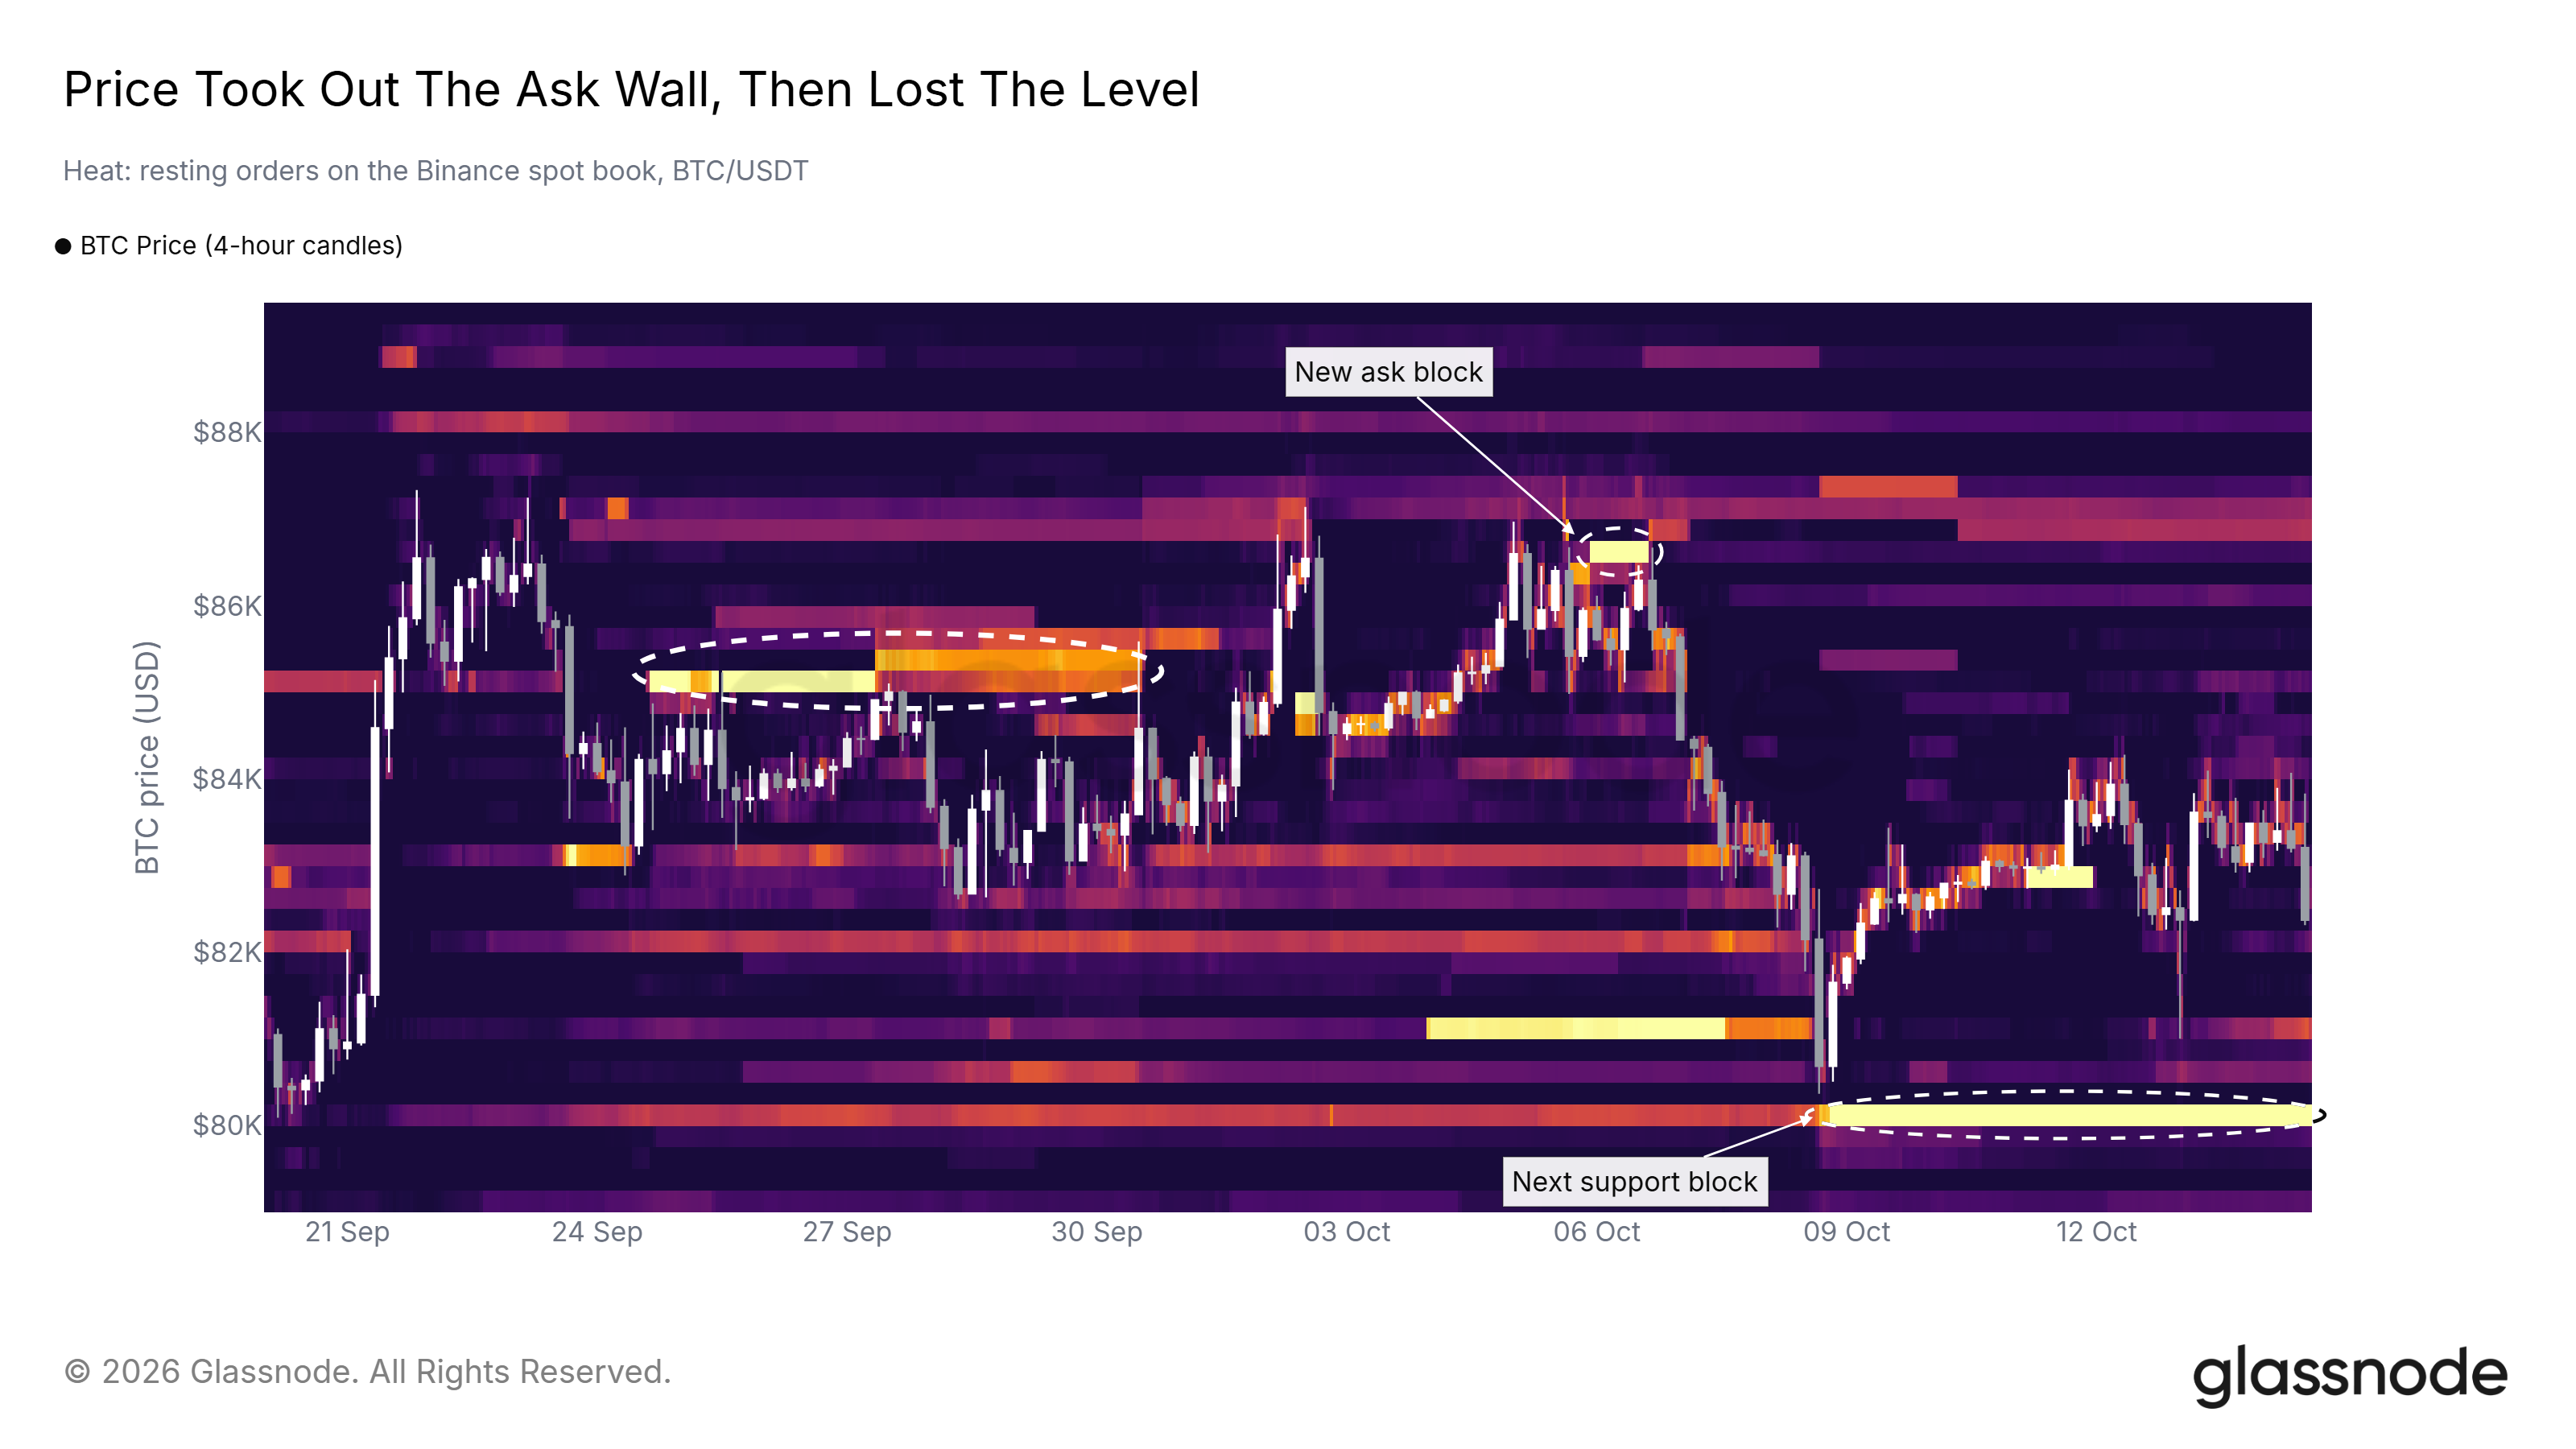
Last week, this report pointed to the bids at $81K on the Binance spot book. Bitcoin traded through them on October 8, and the largest block of bids now sits one level lower, at $80K. It grew sharply late on October 8 and has held since.
The block sits just under the US Spot ETF Cost Basis, so the zone between $80K and $81.5K is where order-book and on-chain support overlap. A break below it would bring the liquidation cluster just under $80K, and then the True Market Mean near $78K, into play.
A Shallow Bear Market
In the 2018 and 2022 bear markets, Bitcoin spent months below the Realized Price, the average price paid for every coin in circulation. This bear market never closed below it. Even at its lowest close, on June 30, Bitcoin sat about a tenth above the Realized Price, and further still above the Long-Term Holder Cost Basis.
A bottom this shallow means the average holder never went under water. With price back above the True Market Mean and the Short-Term Holder Cost Basis, the cycle looks early in a recovery.
Macro Turns Harder
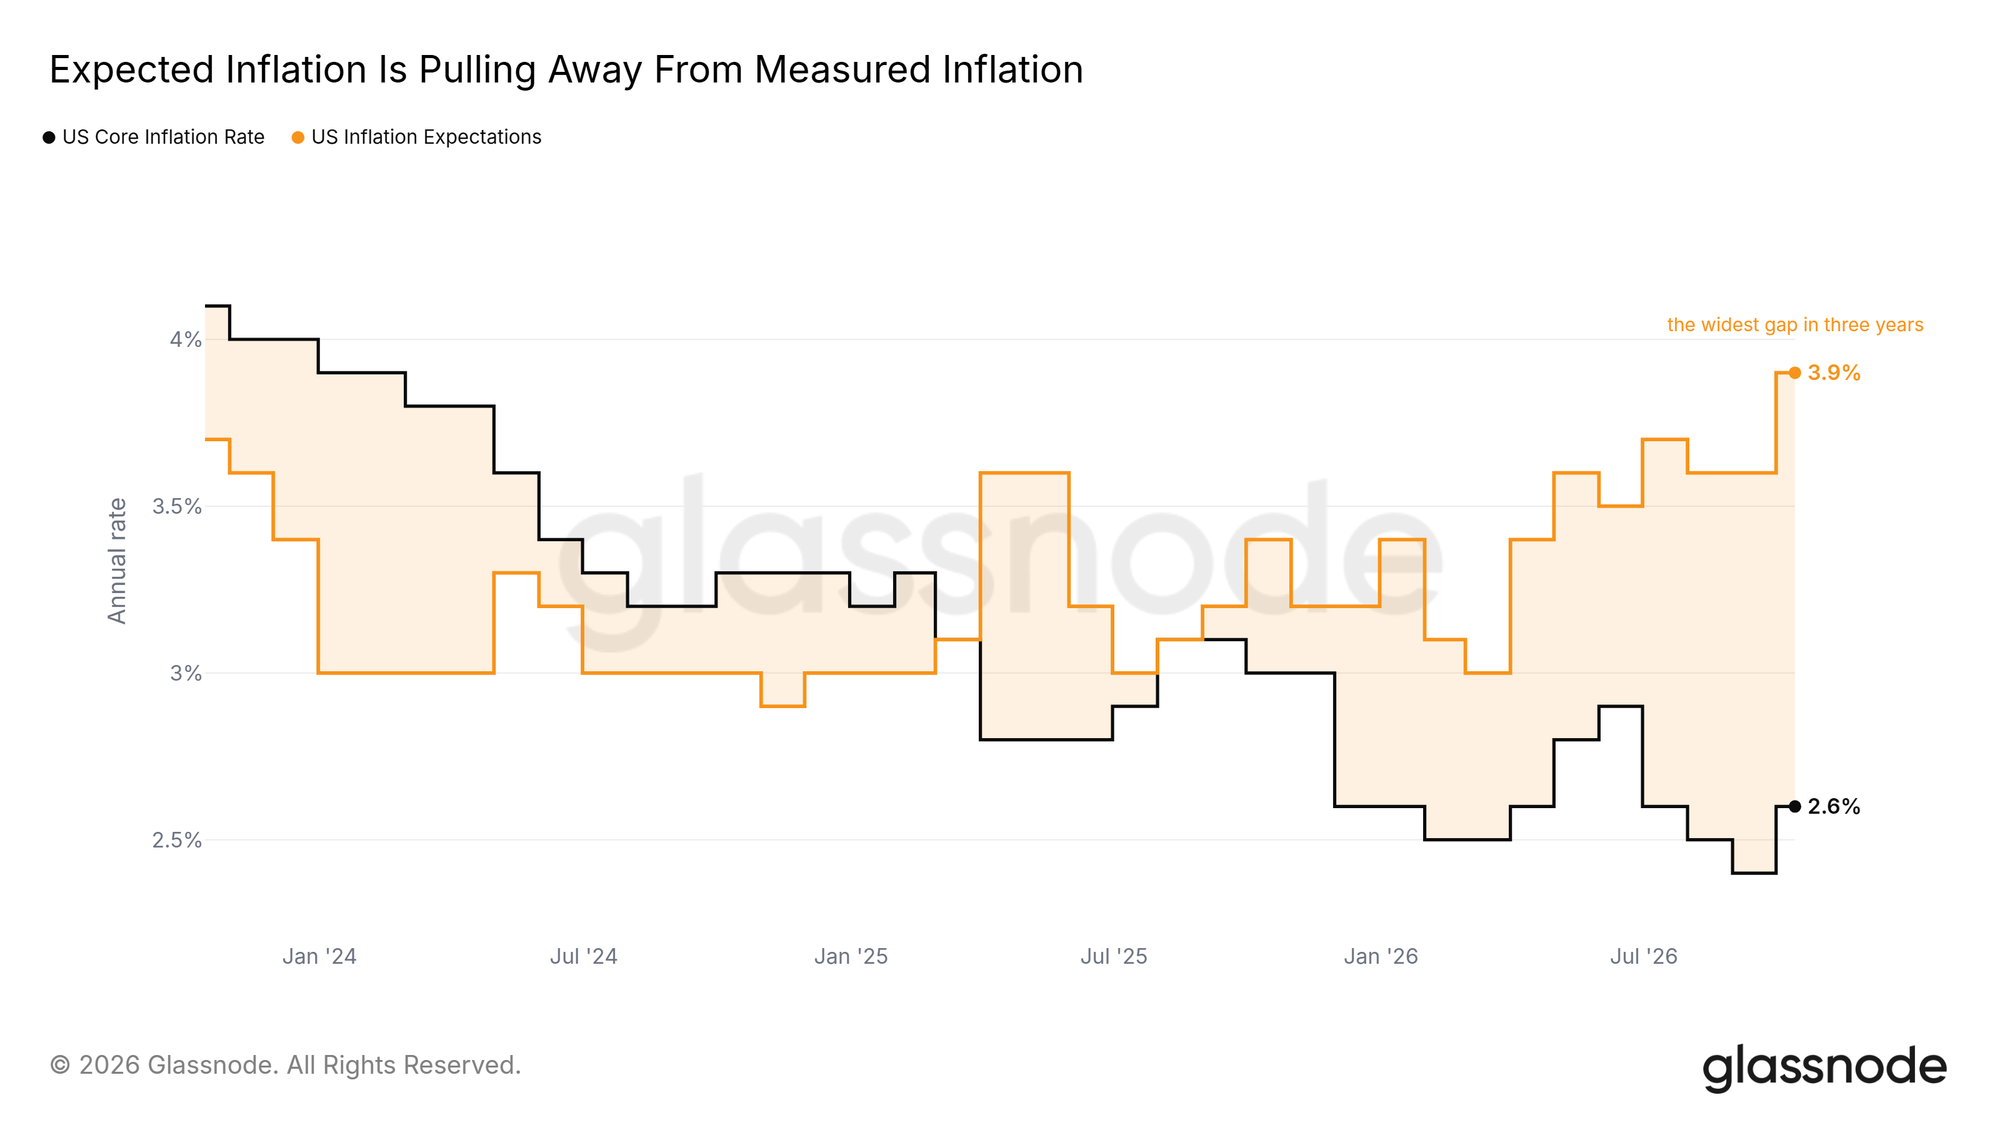
September's CPI, released today, came in above forecasts, with headline inflation at 3.7% and core inflation, which leaves out food and energy, at 2.6%. Bitcoin dipped within minutes of the release. Household inflation expectations have climbed further, and their gap over core inflation is now the widest in three years.
The Fed has already moved once. On September 16, it raised rates by a quarter point, its first hike since 2023. Bitcoin took that in its stride: it barely dipped over the next three days and stood more than a tenth higher a week later. After today's print, futures traders raised the odds of a second hike at the meeting that ends on October 28, and the US midterm elections follow on November 3.
Altcoins Froth Coin by Coin
The Altcoin Froth Indicator combines two readings, each ranked against its own history: coin froth, which tracks how many altcoins carry heavy leverage against their own past, and global froth, which applies the same test to the altcoin market as a whole. Coin froth has sat in its top fifth since September 28. Global froth is low, and it has not been in its top fifth since the run-up to the October 2025 crash.
Froth inside many single coins, while the market as a whole stays calm, points to pockets of crowded leverage. Those pockets would be the most exposed if Bitcoin slips toward the $80K bids.
Conclusion
Bitcoin is boxed in between firm support below and heavy supply above. The near term argues for caution: the ETFs are selling again, September's CPI came in hot ahead of the October rate decision and the midterms, and the buyers of the past two years wait near their break-even above $88K. The longer view is stronger: loss-taking has dried up, holders in profit lead the spending, and this bear market never closed below the Realized Price.
A daily close above $88K, with ETF inflows returning, would show demand absorbing the overhead supply. A break of the $80K bids and the ETF cost basis would bring the True Market Mean near $78K into view.
Data as-of October 13, 2026 for daily on-chain metrics, October 12, 2026 for ETF flows, and October 14, 2026 for hourly price, the liquidation heatmap and the Binance order book. The September core CPI print comes from the BLS release of October 14, 2026; the most recent daily points remain subject to revision.
Disclaimer: This report does not provide any investment advice. All data is provided for informational and educational purposes only. No investment decision shall be based on the information provided here, and you are solely responsible for your own investment decisions.
Exchange balances presented are derived from Glassnode’s comprehensive database of address labels, which are amassed through both officially published exchange information and proprietary clustering algorithms. While we strive to ensure the utmost accuracy in representing exchange balances, it is important to note that these figures might not always encapsulate the entirety of an exchange’s reserves, particularly when exchanges refrain from disclosing their official addresses. We urge users to exercise caution and discretion when utilizing these metrics. Glassnode shall not be held responsible for any discrepancies or potential inaccuracies.