Hey all, Jason here.
I just finished copy editing in a hotel lobby outside of Barcelona. It’s 1:00am, which is equivalent to maybe 9:00pm in normal time. When this lands in your inbox, I should be on a flight back to Amsterdam (though with the civil unrest in Barcelona and KLM warning again of weather disruptions at Schipol, who knows.)
It has been an amazing, fun, exhausting two weeks on the road in Mexico City (muchas gracias a todos en Monato, Juan Miguel Guerra Dávila de Revolut, y Neri Tollardo de Banco Plata por una bienvenida muy cálida), Las Vegas (too many people to name), Barcelona, and todo mi familia en Mataró.
Until next time! 🇲🇽 🇺🇸 🇪🇸 🇳🇱
Subscribe or Support by Upgrading
Vegas is over. Fintech deserves something different.
Partner content: Enough with the endless expo aisles and badge scans. Let’s talk about what actually matters.
At NerdCon, Chime co-founder Ryan King reveals why Chime built its own banking core. Revolut US CEO Cetin Duransoy takes on whether Revolut can win America. And Figure CEO Michael Tannenbaum asks whether blockchain can finally fix the mortgage industry.
Add the nerds from Visa, Stripe, Plaid, Socure, Sardine and hundreds more. No traditional expo. No conference theater. Just the people building what’s next.
Less than 4 weeks. One very different fintech event.
NerdCon. San Diego. November 18–20.
FBW readers get 20% off with code FBW20.

Is Asking For A Tip “Free Speech”? EarnIn Says It Is.
“Congress shall make no law respecting an establishment of religion, or prohibiting the free exercise thereof; or abridging the freedom of speech, or of the press; or the right of the people peaceably to assemble, and to petition the Government for a redress of grievances.”
So reads the First Amendment to the United States Constitution. (As someone who occasionally writes on controversial topics, I’m familiar with it!)
Activehours, Inc., better known as EarnIn, is arguing that a Maryland law violates both the company’s First Amendment rights and it’s users’, by prohibiting their freedom to express themselves — by asking for and by leaving “tips,” respectively.
The suit, filed in U.S. District Court in Maryland, is the latest skirmish over the business models and monetization strategies employed by earned wage access providers.
For those who are unfamiliar, EWA providers are typically grouped into two categories: employer-integrated and direct-to-consumer.
Employer-integrated providers typically enter into contracts and connect to companies’ payroll, time, and attendance systems. This integration gives the EWA provider deterministic information on a user’s hours worked and accrued wages, net of taxes, benefits, and other payroll withholding. The EWA provider is repaid concurrently with a user’s payroll, making the credit risk near zero. Functionally, an employer-integrated EWA provider is underwriting the risk of the company not making payroll, rather than the likelihood of a user taking an advance not being able to repay it.
By contrast, direct-to-consumer EWA providers do not typically have access to users’ payroll, time, and attendance data. They employ a number of other techniques, including analysis of bank account transaction data and, in some cases, GPS location tracking, to estimate a user’s accrued but unpaid wages. Repayment typically comes from an external linked bank account, which does present the risk of a DTC EWA provider not being able to successfully collect previously advanced wages.
EWA products are typically structured as “non-recourse,” meaning that if a provider is unable to collect, they cannot pursue repayment using the tools a creditor typically would, such as by reporting negative information to credit bureaus, referring debt to a third-party collection agency, filing a lawsuit, seeking to garnish a user’s wages or other funds, or selling the debt to a third party.
Revenue models for employer-integrated and DTC EWA providers vary. In employer-integrated models, some companies will cover some or all costs as a benefit to their employees. But more common EWA revenue models include charging monthly subscriptions for access to the product, charging “expedited funding” fees, and soliciting “tips” from users.
Some EWA companies also provide payroll cards or a neobank-like product, enabling users to have EWA draws and their payroll deposited to the provided cards / accounts, thereby allowing the EWA company to earn interchange revenue on users’ card spend.
EWA providers typically argue that this overall product structure — non-recourse and costs that, they argue, are not finance charges — mean that EWA products do not meet the definition of credit under most federal and state laws and regulations.
EarnIn explains in its new lawsuit that “[t]his non-recourse structure is not incidental or accidental—it is a fundamental feature of the product’s architecture. EarnIn designed Cash Out to operate differently from a loan—not to circumvent the law, but to benefit workers by creating a product whose features are distinct from loan and credit products in their most essential and impactful ways. Unlike a payday lender, EarnIn cannot—and does not—bring court actions, report to credit bureaus, file bankruptcy claims, sell debts, garnish wages, or pursue litigation or arbitration to collect outstanding Cash Out disbursements.”
While EWA providers generally argue they are providing a truly novel and helpful product — access to wages a worker has already earned but not yet received — consumer advocates and some policymakers argue that EWA is merely a payday loan in disguise and can lead to similar if not worse “debt traps” for consumers.
A 2023 report from the California Department of Financial Protection and Innovation analyzed use of the product in the state. The DFPI’s analysis found annualized percentage rates — admittedly a flawed metric for assessing the cost of advances that are typically repaid in about 10 days — could reach over 1,300% on the smallest advance amounts.

APRs on larger advance amounts dropped rapidly, with the typical APR for advance amounts of over $500 coming in at 23% — in the range of a typical near-prime installment loan and orders of magnitude lower than the cost of accruing a similar amount of bank overdrafts.
The same DFPI report found users of EWA products, both tip-based and non-tip-based, took an average of nine advances per quarter, with the heaviest users taking as many as 25 advances per quarter.
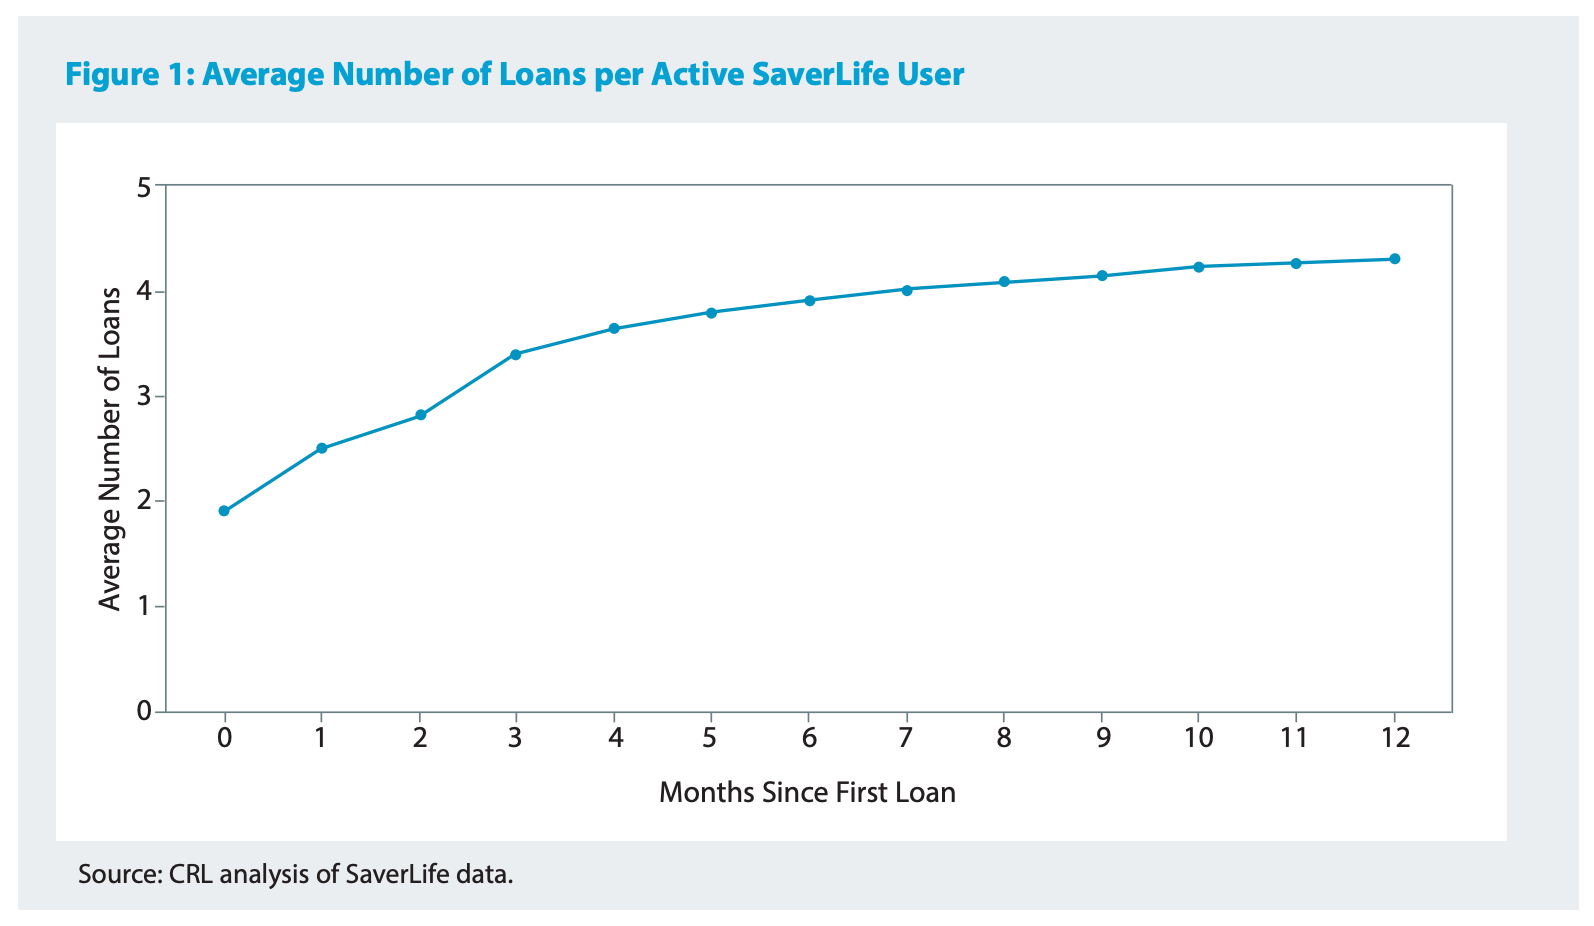
A more recent report from the Center for Responsible Lending that analyzed data from financial health platform SaverLife found that, once users began using EWA, the number of loans they took tended to increase over time.
However, industry trade association the American Fintech Council argued that the CRL’s report contained material inaccuracies and relied on an unsound methodology. The AFC wrote in part at the time:
The CRL report’s most significant methodological flaw lies in its unrepresentative sampling. Its focus on a chronically vulnerable subset of users, while excluding occasional and short-term participants, dramatically overstates claims of dependency and usage escalation. Without adjusting for external shocks such as job loss or medical emergencies, the analysis mistakes correlation for causation—misinterpreting temporary increases in EWA use as evidence of structural harm. This biased sampling obscures the reality that most EWA users engage intermittently, not chronically, and that responsible design practices—such as withdrawal caps and payroll integration—actively minimize risk of habitual use.
The footnote that ate model risk
Partner content: Buried in a footnote of SR 26-2 is a line every bank deploying AI should have taped to their monitor: generative and agentic AI are “not within the scope of this guidance.”
Some read that as a free pass. I don’t. Examiners haven’t stopped asking about AI. They’ve just stopped telling you what the answers should be.
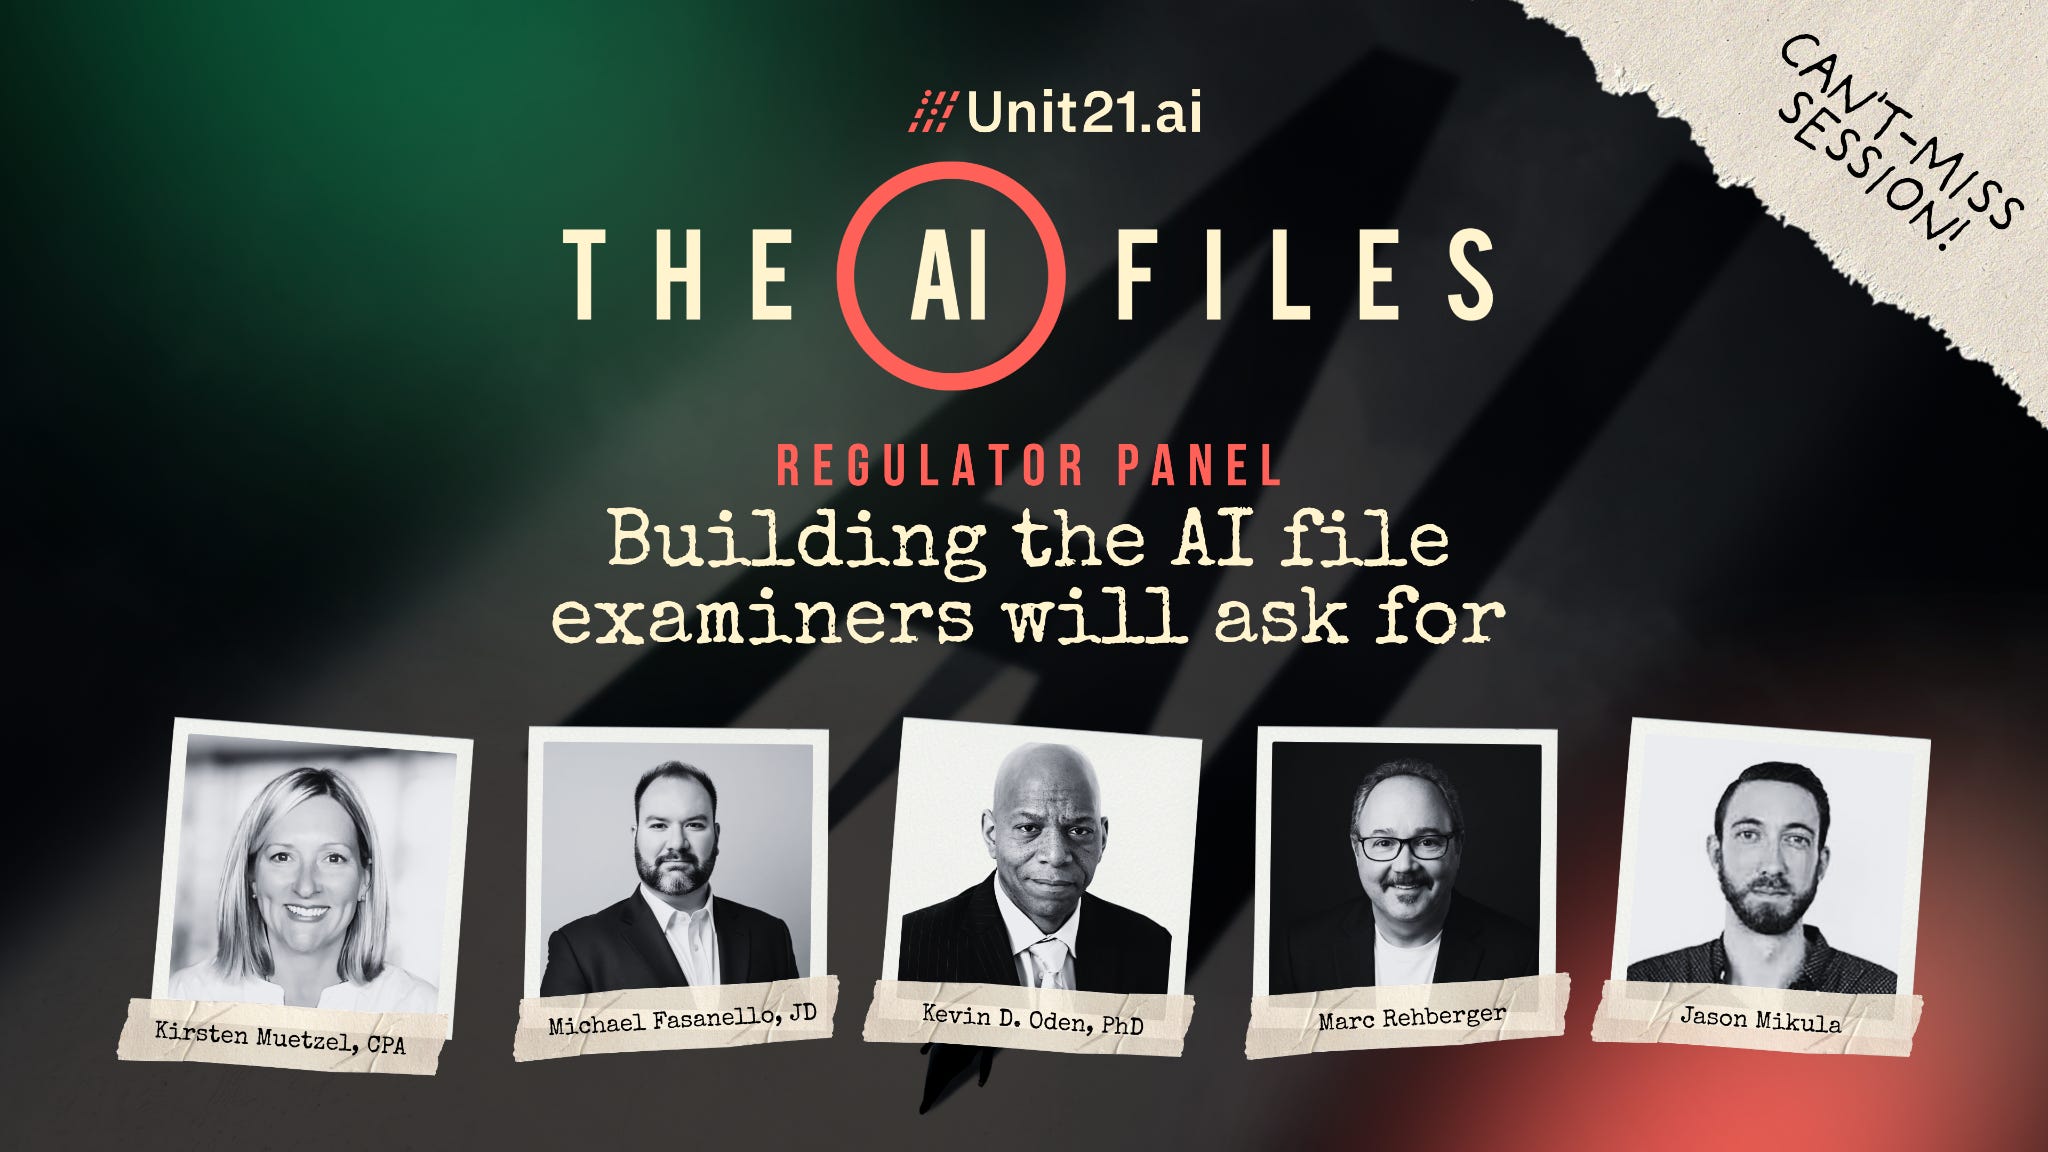
On Nov 3 I’m moderating a panel that will try to fill that gap. Our case: a sponsor bank’s fintech partner wants AI to auto-close 40% of its alerts, and the exam is 90 days out. Joining me:
Kirsten Muetzel, former Fed examiner who now steps into banks under regulatory pressure
Kevin Oden, model risk validator and former Wells Fargo risk executive
Marc Rehberger, who builds AI inside banks for a living
Michael Fasanello, BSA Officer at Bakkt and former FinCEN attorney
I’ll be pushing them for the uncomfortable specifics: what goes in the file, and what number is “good enough.”
Nov 3 · 11:15am PT / 2:15pm ET · Free, virtual
Just 1 of 7 sessions as part of The AI Files. Also hear from practitioners like Rob Fenner of Rippling, Zaheer Jassat of Zepz, Sid Talreja of Circle, Jorge Cortes of Kinecta FCU, and more.
Freedom To Tip?
The case EarnIn filed last week, captioned Activehours, Inc. v. Brown et al, is hardly the first litigation or regulatory action the company has been party to. The company’s lengthy history of litigation and regulatory actions has included:
State attorney general actions
Nov. 2024, District of Columbia: The D.C. Attorney General sued EarnIn. It alleged unlicensed lending at APRs exceeding 300%, violating D.C.’s 24% cap, and deceptive “no mandatory fees” marketing. In May 2025 the court dismissed the claims that EarnIn’s Cash Out product is a loan, deferring to D.C.’s banking regulator. The false-advertising claims are continuing.
Aug. 2026, Colorado: The Colorado Attorney General sued EarnIn. It alleged unlicensed high-cost lending in violation of state law and a deceptive “dark pattern” tipping design. It said EarnIn collected more than $16 million in tips and expedite fees from state residents between January 2023 and July 2025.
State regulatory actions and legislation
2019, New York-led multistate: New York’s Department of Financial Services led a group of ten states and Puerto Rico in investigating the payroll advance industry, including EarnIn. NYDFS subpoenaed EarnIn customer data and found tips on a $100 could be as high as $14.
2023–24, Connecticut: The state legislature passed a law to begin treating tips and expedite fees as finance charges under its state small-loan law. EarnIn left the state on Jan. 1, 2024.
July 2025, Colorado and Wisconsin: EarnIn replaced tips with fixed expedite fees in both states, citing new regulatory guidance.
October 2025 and October 2026, Maryland: A 2025 law treats certain EWA as loans requiring a state license, and requires a no-cost option and fee limits. A 2026 law, which became effective on October 1 — the impetus for EarnIn’s lawsuit — bans EWA providers from accepting or soliciting tips.
Civil litigation
2019, Perks v. Activehours (California federal court): A class action related to overdraft fees caused by EarnIn’s account debits. The suit settled in 2021 for $3 million and up to $9.5 million in forgiven advances.
2019, Stark v. Activehours (California federal court): Alleged that tips were undisclosed finance charges and that users who didn’t tip had their borrowing limits lowered. The case was voluntarily dismissed.
2022, Golubiewski v. Activehours (Pennsylvania federal court): A Pennsylvania usury and Truth in Lending Act suit. The case remains ongoing.
2024, Orubo v. Activehours (California federal court): A Georgia payday-lending and Truth in Lending Act suit. In April 2025 the court held that tips and expedite fees are plausibly finance charges.
2024, Thomas v. Activehours (Maryland federal court): In August 2025 the court allowed Maryland consumer-loan and Truth in Lending Act claims to proceed. In August 2026 the court found the plaintiff plausibly alleged that EarnIn’s advances are “debt” under Maryland’s debt-collection law.
2025, Hardy-Gerena v. Activehours (D.C. Superior Court): A consumer-protection class action, though it was dismissed in deference to D.C.’s banking regulator.
2025, Stow v. Activehours (North Carolina federal court): A North Carolina lending and debt-collection suit. The court sent the case to arbitration in October 2025.
2025, Ramirez v. Activehours (California federal court): A Military Lending Act, Truth in Lending Act and Illinois predatory-lending suit. The court denied EarnIn’s motion to dismiss in March 2026, and the case remains pending.
The new case stems primarily from the Maryland law seeking to prohibit EWA apps like EarnIn from soliciting tips that went into effect on October 1, 2026.
EarnIn’s complaint echoes the language of EWA proponents and industry trade associations, describing the product as an “innovative response to a familiar problem in American financial life” — that “workers often earn wages days or weeks before payday, but cannot use those wages when bills, medical expenses, car repairs, or other urgent needs arise.”
EarnIn’s complaint positions its direct-to-consumer offering favorably to other financial instruments, saying, “EWA products allow workers to access a portion of wages they have already earned, meaning individuals do not need to resort to payday loans, overdraft fees, or revolving credit card debt to cover short-term expenses. In that way, EWA products provide workers with a practical, low-cost tool for managing the timing mismatch between when they earn money and when they need it.”
EarnIn, like many other EWA providers, offers users a free option, which can take 1-2 days for funds to arrive, or users can opt to pay an expedited funding fee. The company also asks all “customers to include a tip as part of their transaction to support EarnIn’s mission of offering low and no cost, easy-access EWA products to millions of workers.”
While EarnIn’s filing says that “many customers decline the voluntary tip option without any impact to their Cash Out experience,” this was not always the case.
The company faced a 2019 class-action suit, mentioned above, over allegations that users who did not tip had their maximum advance amounts lowered and/or lost access to certain products and features altogether. EarnIn’s own website stated this was its practice at the time, according to 2019 NBC News coverage of the company.
When Maryland initially passed a law regulating EWA in 2025, the framework it created did permit tips, so long as such payments were made solely at the user’s discretion and the EWA provider made clear disclosures that tips were optional and not a condition of receiving service.
However, this April, Maryland Governor Wes Moore signed another measure addressing EWA in the state, SB 94. According to a news release at the time (emphasis added):
The Earned Wage Access bill closes regulatory loopholes for app-based payday loans that allow workers to borrow against their wages before the end of the payroll cycle. This legislation follows a 2024 Market Inquiry that revealed Maryland consumers paid over $35 million in fees on 5.5 million transactions using these apps between 2019 and 2024. This new law officially bans the exploitative practice of lender “tipping.”
The ban halts “dark-pattern pricing,” where manipulative app designs pressure consumers of limited means into paying hidden fees disguised as tips that average more than $280 per user.
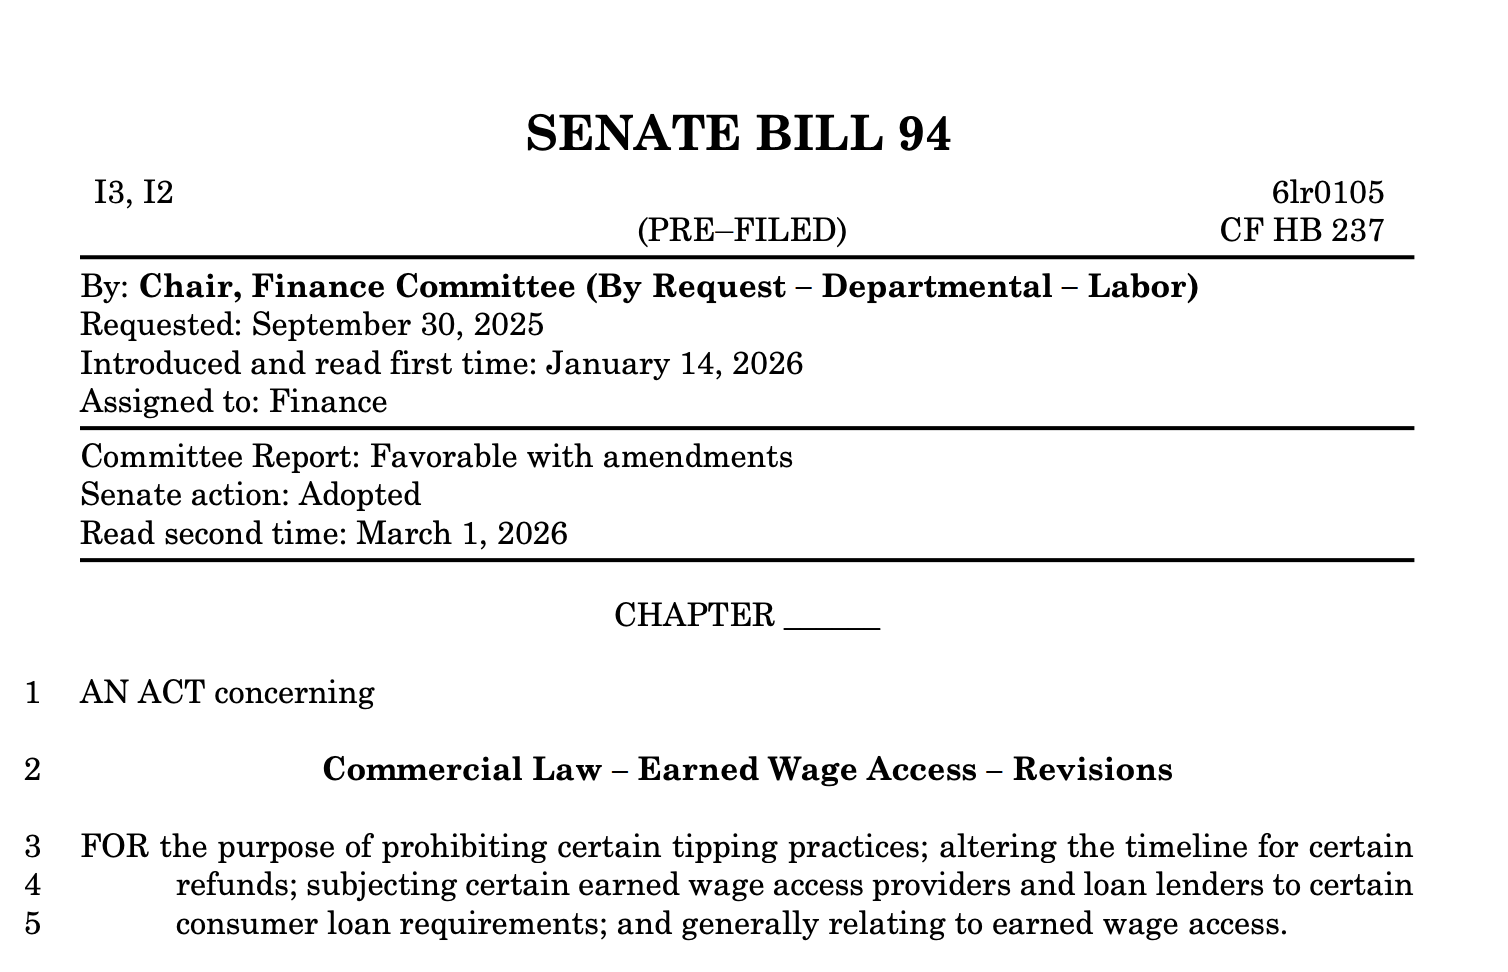
The updated measure not only prohibited EWA providers from soliciting or accepting tips, but also required EWA providers to disclose that they are prohibited from accepting tips from consumers.
EarnIn’s complaint notes that “[n]o other Maryland law targets a specific industry by compelling this kind of speech or by prohibiting the mere request for a voluntary tip or donation” and further argues that “by stating that EWA providers are prohibited from accepting or retaining tips, the law also imposes a blanket ban on the expressive conduct of Maryland workers to provide tips.”
Thus, EarnIn argues, “SB 94 is a content- and speaker-based restriction on protected speech that violates the First Amendment.” The new law “targets earned wage access providers and forbids them from engaging in constitutionally protected speech: the solicitation of tips from users of their service who want to support the endeavor,” EarnIn’s complaint says.
Maryland workers’ constitutionally protected free speech rights are also infringed by the law banning EWA providers like EarnIn from soliciting or accepting tips, the suit argues, because “the law also imposes a blanket ban on the expressive conduct of Maryland workers to provide tips.”
Maryland Law Also Violates Due Process, EarnIn Suit Says
In addition to the tipping- and free speech-related arguments, EarnIn argues that Maryland violated the company’s due process rights in how it has handled its licensing application — specifically, in demanding EarnIn pay millions in restitution before the state will grant the license.
Prior to the initial 2025 EWA law, the Maryland OFR had issued guidance in 2023 on whether or not EWA providers need to be licensed under the existing state lending law. Per the 2023 guidance, DTC EWA providers “were subject to a case-by-case, ‘facts and circumstances’ analysis to determine whether the provider is a lender required to obtain a license,” EarnIn’s complaint explains.
The guidance stated that for DTC providers, like EarnIn, “whether an EWA product constitutes a loan under Maryland law depends on: (1) who bears the economic risk of default; (2) the level of contact between the EWA provider and the consumer; and (3) whether fees or tips are paid to the EWA provider,” per EarnIn’s complaint. EarnIn says that the Maryland OFR never gave the company any indication that licensing under the state’s existing lending laws was necessary.
The 2023 guidance underwent no notice-and-comment rulemaking process, had no public comment period, and was not published in the Maryland Register.
When, following passage of Maryland’s 2025 EWA law, EarnIn did, as required, submit an application for a lending license, the OFR delayed granting its license for over a year. The OFR “refuses to issue a license unless EarnIn pays millions of dollars in so-called restitution and monetary penalties for EarnIn’s supposed failure to obtain a license for over 10 years before 2025 and over 6 years since OFR’s first investigation of EarnIn—something it had no obligation to do prior to the passage of the EWA statute,” EarnIn’s complaint alleges.
Maryland is “[h]olding EarnIn’s license for ransom unless EarnIn pays unlawful and retroactive monetary penalties,” which, EarnIn argues, unconstitutionally violates the company’s due process rights.
In addition to the constitutional claims, EarnIn’s suit is seeking a declaratory judgment that its EWA products offered prior to the effective date of the 2025 EWA law were not “loans,” that tips and optional expedited transfer fees are not “interest,” and that the OFR’s 2023 guidance lacks the force of law, as it was not promulgated in compliance with the Maryland Administrative Procedure Act.
Asked about the suit, David Durant, EarnIn’s Chief Legal & Regulatory Officer said in part:
EarnIn builds its products to give workers more flexible, transparent alternatives to overdraft fees, late fees and other costly options for access to funds. EarnIn sued Maryland to protect those choices for our customers and for all Marylanders. SB 94 is a content- and speaker-based restriction on protected speech that violates the First Amendment. EarnIn’s tip solicitations communicate a truthful, non-misleading message: that optional tips help support EarnIn’s mission of providing workers access to their own earned wages without mandatory fees or interest. That's not consumer protection, it's the state protecting the status quo when workers need better products.
Asked to comment, Aleithea A. Warmack, Deputy Communications Director at the Maryland Office of the Attorney General declined to do so. The Maryland Office of Financial Regulation did not respond to a request for comment as of the time of publication.
Whipsaw, State by State
In the “debanking” report released by the Office of the Comptroller of the Currency earlier this month, the OCC warned of the potential for public policy, as expressed through formal law and regulation and more subjective supervision and enforcement, to “whipsaw” between administrations.
The OCC report spoke primarily to federal banking policy. And indeed, federal policy that speaks to whether or not EWA should be considered “credit” and associated costs should be considered “finance charges” has seen this whipsaw effect.
In November 2020, under then-Director Kathy Kraninger, the Consumer Financial Protection Bureau offered an advisory opinion that offered safe harbor for certain kinds of EWA programs. The opinion specified that a narrow set of employer-integrated EWA programs that met specified conditions would not be considered “credit” under the Truth in Lending Act.
Then, in July 2024, under then-Director Chopra, the CFPB proposed an interpretive rule that would have treated EWA products as “credit” under the Truth in Lending Act and would have deemed costs, like expedited funding fees and, in most circumstances, tips, as “finance charges.” The proposal was never officially finalized.
In 2025, the CFPB, led by acting Director Russ Vought, withdrew the Chopra-era proposal and issued a new advisory opinion that “covered” EWA programs are not credit, so long as the products cap advances at wages already earned, based on payroll data; be repaid through payroll deduction; disclaim any recourse against the worker, debt collection or credit reporting; and do no credit underwriting.
EarnIn’s First Amendment arguments against Maryland’s attempt to ban “tipping” business models are novel — but the whack-a-mole game between states and unconventional, often higher-cost forms of borrowing are not.
The state-by-state legal battles over EWA seem likely to continue indefinitely, with the added uncertainty of what may happen at the federal level under a future set of financial regulators.
Things To Know & Other Good Reads
OCC Advances U.S. Digital Asset Leadership with Final Rule to Implement GENIUS Act (Office of the Comptroller of the Currency)
US banks are blocking third-party AI agents access to customer accounts, sources say (Reuters)
Ramp applies for national trust bank charter from OCC (Banking Dive)
Plata CEO Says Fintech’s Annualized Revenue Reaches $1 Billion (Bloomberg)
Cross River to acquire Accrue (Payments Dive)
Cash-flow credit analytics startup Prism Data raises $20M (Prism Data)
Saudi Arabia’s Fintech Oasis: A Market Flowing with Opportunity (Fintech Under the Hood)
Capital Wars: CoreWeave and the Economics of a Data Center Build (Net Interest)
Money2026 (Fintech Takes)
A Material World: Getting lost in the definitions in regulators’ material financial risk rule (Fintech Takes Banking)
Listen: Congress May Flip. What Actually Changes for Banks? (Banking with Interest)
About Fintech Business Weekly
Looking to work with me in any of the following areas? Email me.
Buy my best-selling book, Banking as a Service: Opportunities, Challenges and Risks of New Banking Business Models, here
Vendor, partner & investment opportunity advice and due diligence
Fintech advising & consulting
Sponsoring this newsletter
News tip or story suggestion — reach me on Signal at mikulaja.01