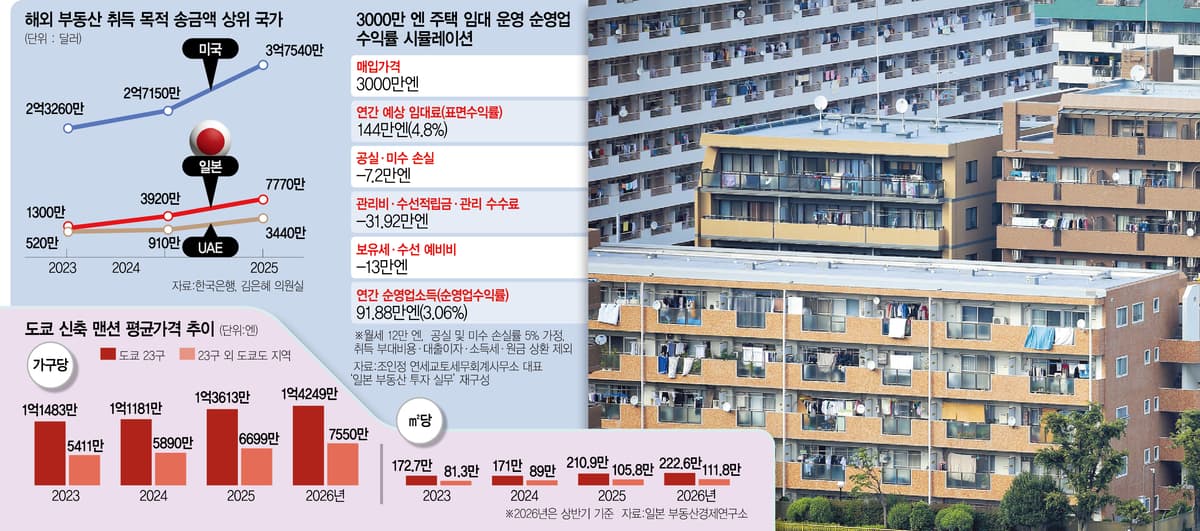
A weaker yen is drawing more Korean investors to Japan's property market. Tokyo real estate, once the preserve of institutions, is increasingly attracting individuals. Their approaches vary: buying a tower mansion, or high-rise apartment, in Tokyo for short-term rental income and capital gains; securing a second home for stays in Japan while the yen is at historic lows; or purchasing a building of small rental units to collect monthly rent. Yet with local home prices and lending rates both rising, applying the old investment playbook is unlikely to deliver the returns investors expect, analysts say. Experts advise weighing the cash that actually remains after taxes, management costs and financing expenses, rather than focusing solely on the buying opportunity created by the weak yen.
Consultations on Japanese residential investment increasingly center on the price burden in prime Tokyo districts and on checking returns against rising mortgage rates, according to financial industry and overseas property investment sources on the 23rd. Some investors are broadening their search to other large cities such as Osaka, or cutting back on borrowing and approaching the market as a way to diversify assets.
Capital Gains or Rental Income
Remittances by Korean residents to buy property in Japan rose about sixfold, to $77.7 million (about 102.8 billion won) last year from $13 million (about 17.2 billion won) in 2023, according to Bank of Korea data submitted to the office of Rep. Kim Eun-hye of the People Power Party. The number of transfers also rose, to 169 from 74 over the same period. Through April this year, the total stood at $36 million across 95 transfers. Japan's share of all remittances for overseas property purchases climbed to 13.2% last year and 17.1% in the January-April period this year, from 3.5% in 2023. The figures combine individuals and corporations and exclude funds raised through local borrowing, meaning actual investment is larger.
"Japan is emerging from prolonged deflation and has seen prices and wages rise over the past three to four years," said Kim Hyung-yoon, an adviser at law firm Yulchon and a former head of alternative investment at KB who specializes in the field. "Through the long deflation, housing was seen as an asset that loses value over time. That perception is changing as people experience rising home prices and rents."
Cho In-jung, head of Yonsei Kyoto Tax Accounting and a specialist in international taxation, said many clients she advises are weighing asset diversification and ease of management. "They view Japanese property as an investment where the goal is not to make a lot of money but to avoid losing a lot," she said. Some are also looking for a home they will use themselves, prompted by a child's studies abroad or business travel, she said.
Individual investors generally take one of two approaches: pursuing capital gains, or covering holding costs and loan payments with rent while hoping for a gain on an eventual sale. The weak yen lowers the purchase cost in won terms, and low local interest rates were long seen as another draw because they could lift returns on equity. Interest in Japan's housing market has grown in particular because mortgage restrictions in Korea have made borrowing difficult at home, while Japanese lenders will extend loans even to foreign buyers if there is cash flow such as monthly rent.
For rental properties, the size of a loan can be assessed based on cash flow, calculated by subtracting management fees and other costs from expected rent. Rent alone does not determine the limit; the borrower's credit, the value of the collateral and each lender's terms are also factored in. Highly developed property management services are another convenience for investors living abroad. Local management firms, including affiliates of major companies such as Mitsui Fudosan, handle tenant recruitment, rent collection and complaints, allowing owners to run properties while living in Korea. "There is a system in place for collecting rent through a management company and receiving reports on the property's condition," Kim said. "It is convenient, but the fees have to be taken into account as well."
Tokyo Prices and Rates Climb, Shifting Attention to Osaka
The catch is that Japanese property prices are also rising quickly, and local price gains can offset the advantage of the weak yen. The average price of a newly built condominium in Tokyo's 23 wards reached 142.49 million yen in the first half of this year, up from 114.83 million yen in 2023, according to Japan's Real Estate Economic Institute. The average price per square meter rose over the same period to 2.226 million yen from 1.727 million yen. Cho said new condominiums in Tokyo's three central wards typically exceed 300 million yen, and that tower mansions whose prices have risen sharply sometimes yield rental returns of only about 2%.
Among Korean investors, more are buying existing homes, known locally as used housing, instead of new units. An official at a firm that provides property investment consulting between Korea and Japan said that with equity of 1 billion won or more, used housing in Tokyo can be an option, while equity of around 500 million won points to large cities such as Osaka. Kim Yong-nam, chief executive of Global PMC, said investors need to distinguish between holding a tower mansion for personal use and diversification and investing in housing that generates continuing rental income.
Rising interest rates have also made the conditions investors must examine more demanding. "Rather than the gross yield, which divides annual rent by the purchase price, you have to look closely at net operating income, which subtracts operating expenses," Kim said. If the borrowing rate is higher, negative leverage can occur and actually reduce returns.
Yang Jong-wook, a team leader at Shinhan Bank's real estate investment advisory center, said local lending rates he has recently tracked are approaching 3%, making it harder to boost returns on equity through borrowing as investors did in the past. Faced with the price burden in prime Tokyo, some are widening their search to outlying areas near train stations, or to Osaka and Fukuoka, he said. Demand from those seeking to hold a second home or a high-end property with their own funds for diversification, by contrast, remains steady, he said.
The high cost of prime Tokyo is pushing some investors to look elsewhere, including Osaka's Umeda district, where affluent tower mansions are clustered, and prime locations in Fukuoka. Unlike Tokyo, these areas have yet to impose rules on Airbnb and other lodging for foreign visitors, and as Chinese investors withdraw amid a decline in Chinese tourism, investment interest is growing among Taiwanese and Korean buyers.
One of Cho's clients bought a tower mansion in Osaka's Umeda for 120 million yen. The buyer took out a 50 million yen loan in June at an annual rate of 1.95% and added 70 million yen of their own funds, with acquisition and registration costs and brokerage fees separate. Monthly rent is 270,000 yen, for a gross yield of 2.7% a year. But by the firm's calculation, 803,000 yen remains from annual rent of 3.24 million yen after interest, management company fees, fixed asset tax and tax filing costs. That is before principal repayments and additional taxes. Under the same conditions, a 3% annual rate would cut the remainder to 278,000 yen. Conversely, keeping the current rate while raising rent 5% would lift it to 956,900 yen. Rent increases, however, depend on lease terms and negotiations with tenants, so rising market rents in the area do not translate directly into higher income. The timing and feasibility of any increase have to be weighed against the lease terms and discussions with the tenant.
Small Rental Units an Alternative; Count Fees, Vacancies and Currency
For those seeking steady rental income, small rental units occupied by office workers and others are worth considering alongside expensive tower mansions. "Investors need to temper expectations for further capital gains on tower mansions and pay attention to the cash flow generated by small rental units in areas with easy commutes," Kim said. The point is to look for properties where facilities can be upgraded when a tenant changes and rents adjusted to match market levels nearby.
Before buying, it is important to obtain lease contracts, records of actual rent payments, tax notices, statements of management fees and repair reserves, and long-term repair plans. Buyers should also check whether the expected rent shown in advertisements matches the rent currently collected. Fees paid to tenant management firms are separate from the building's own management charges and repair reserves, so care is needed not to leave costs out. "Returns on property vary depending on where it is and how you buy it, so it is risky to assume Japanese investment is good no matter what," Kim said. "On borrowing, too, rather than assuming you can get a set percentage of the purchase price, you should start by looking at how much of the principal and interest you can repay out of rental income after costs."
Investment performance has to be judged through to the point the money is recovered. Incidental costs at purchase, taxes and repair expenses during the holding period, and selling costs all weigh on the outcome. Even if a property turns a profit in yen, gains can shrink if the yen weakens further when the money is converted into won. Interest and management fees keep accruing even if a sale is delayed or a unit sits vacant. Before counting on a gain from a sale, what needs checking is whether the cash flow can carry the investor through that period. "Investors have to distinguish between betting on price gains in tower mansions and securing steady cash flow from rental housing," Kim said. "Rather than short-term capital gains, they need to approach this as a way to diversify assets and earn rental income over the long term."