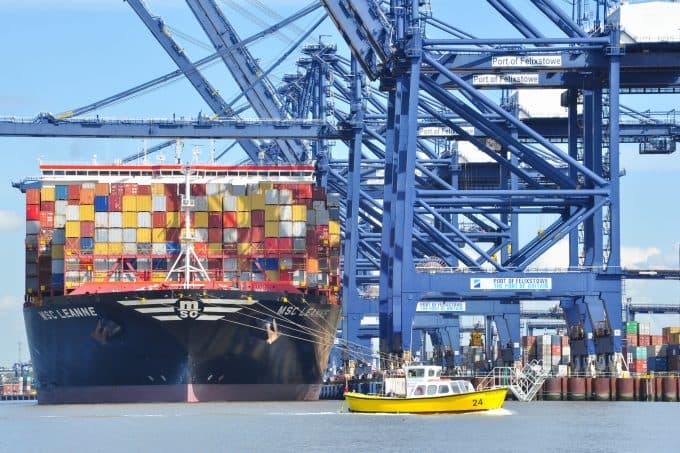
© Peter Moulton Dreamstime.com.
Would a carrier really design its Asia-Europe network around shaving marginal ETS dollars, which it can recoup through surcharges anyway?
In short, carriers did redesign for the ETS – though not around the ETS alone.
Carriers have redesigned Asia–Europe loops to cut their exposure, and they were right to. But the money is not marginal, a surcharge does not make it someone else’s problem, and carbon was never the first reason to call Britain first. Those ports suit the ships; the EU Emissions Trading System made a good choice better.
A few months ago, the EU ETS Observatory published a report stating that UK volume growth was a direct result of shippers seeking to minimise the EU-ETS charges – bullocks, if you ask me.
Container Trade Statistics (CTS), which counts laden boxes by origin and destination, has UK trade up 3% in 2025, against 5% for North Europe as a whole: the Netherlands grew 6%, France 5%, Poland 18%. Britain grew, but slower than its neighbours.

Source: Container Trades Statistics
For a carrier to reduce its exposure is not just an operational saving, it is a commercial competitive advantage: the less your “Carbon surcharge” is, the more attractive your all-in freight charge – you certainly don’t want to be the most expensive in the market.
How a first call is chosen
A rotation is built from constraints before costs: transit time; maximum draught and air draught; the number of cranes and how far and high they reach; the volume each port generates; rail and road links inland; and berth windows that fit the schedule. Only then does the voyage costing run; fuel, port charges, charter hire and, since 2024, carbon. Together they make up the unit cost.

Source: Solvens Advisory
The first call in North Europe is the most demanding, because the ship arrives from Asia at its deepest draught. Few terminals take a 24,000 teu vessel at full scantling draught without restriction: Rotterdam, Felixstowe, and London Gateway can. Antwerp or Southampton take the same ships, but with draught limits. Wilhelmshaven has the water, but calling there first adds transit time to every port after it.
Put Felixstowe or London Gateway first and nothing is lost; the ship has the water, UK importers get the fastest transit, and almost no nautical deviation means the next port is served swiftly thereafter.
Taking the Asia leg out of the ETS as well is a win-win, and carriers took it deliberately.
The test to come
Sea-Intelligence Consulting found the 2026 networks cut ETS-chargeable distance by another 11%. This is simply optimisation, and cost nothing operationally. The evolution of Gemini’s AE3 shows this – Algeciras out at both ends, London Gateway first, and Southampton last – presented by Hapag-Lloyd as ‘enhanced Baltic coverage’ and better for UK exports. Both are true.
Brussels now proposes that container ports with deepsea infrastructure, within 150 nautical miles of the EU, no longer count as a break in the voyage. Felixstowe, London Gateway, and Southampton would qualify. Carriers would pay more, but it is doubtul the rotations would change: the ships still need the water, and Rotterdam still has no spare berths.
That makes the listing a useful experiment. If Britain mostly stays first, once the carbon reward has gone, the leakage thesis will be buried once and for all.
A tax that barely decarbonises
Step back, and the UK first-call says something less comfortable about the ETS itself. In shipping, its effectiveness has been limited, for at least two reasons.
The first is above – carriers optimised their networks within the rules, as they were entitled to, and importers were spared hundreds of millions of euros a year: the Observatory puts the allowances not collected at the three UK ports alone at about €316m. But the deeper cost is not the revenue. A UK first-call does not change a ship’s emissions: same ship, same miles. It removes the carbon price from the Asia leg, the longest of the voyage, and with it any ETS reason to slow down or burn a bio-blend there. The price signal, which is the point of the scheme, stops at the Channel.
The second is where the money goes. Shipping now pays for all its in-scope emissions, roughly 90m tonnes, about €7bn a year at €80. Since 2023, member states have been asked to spend all ETS revenue on climate and energy, and in 2024 they reported 80%. But climate is not shipping. The commission’s carbon market report found about 5% of national ETS revenue went to industrial decarbonisation, and only France and Estonia ringfence a share for shipping. The Innovation Fund holds 20m allowances for maritime projects over 2024–2030, about €1.6bn in all, against a bill of €7bn a year.
In other words, the industry pays for a transition it barely gets to finance.
Brussels has noticed. Its July proposal would create a reserve of up to 110m allowances from 2028 to 2040, covering 55%–90% of the price gap for sustainable fuels and zero-emission propulsion. Per tonne of green fuel, that is generous. In total it is about €0.7bn a year, a tenth of what shipping pays, and if claims exceed it, every claim is cut.
FuelEU Maritime shows the alternative. Its compliance cost stays inside the industry: a ship that over-complies pools its surplus with one that falls short, and the money moves from one shipowner to another that has invested in cleaner fuel. The ETS takes the same industry’s money to national treasuries and asks it to decarbonise anyway.
Carriers do not design networks around the ETS. They design them around ships, water and berths, then cut the carbon bill wherever the network allows, and compete on the surcharge that results. A scheme that taxes legs rather than trades, and spends the proceeds elsewhere, invited exactly that.
If Brussels wants carbon cut, rather than collected, the next revision should worry less about Felixstowe and way more about where the money goes.
You can contact the writer at [email protected]