
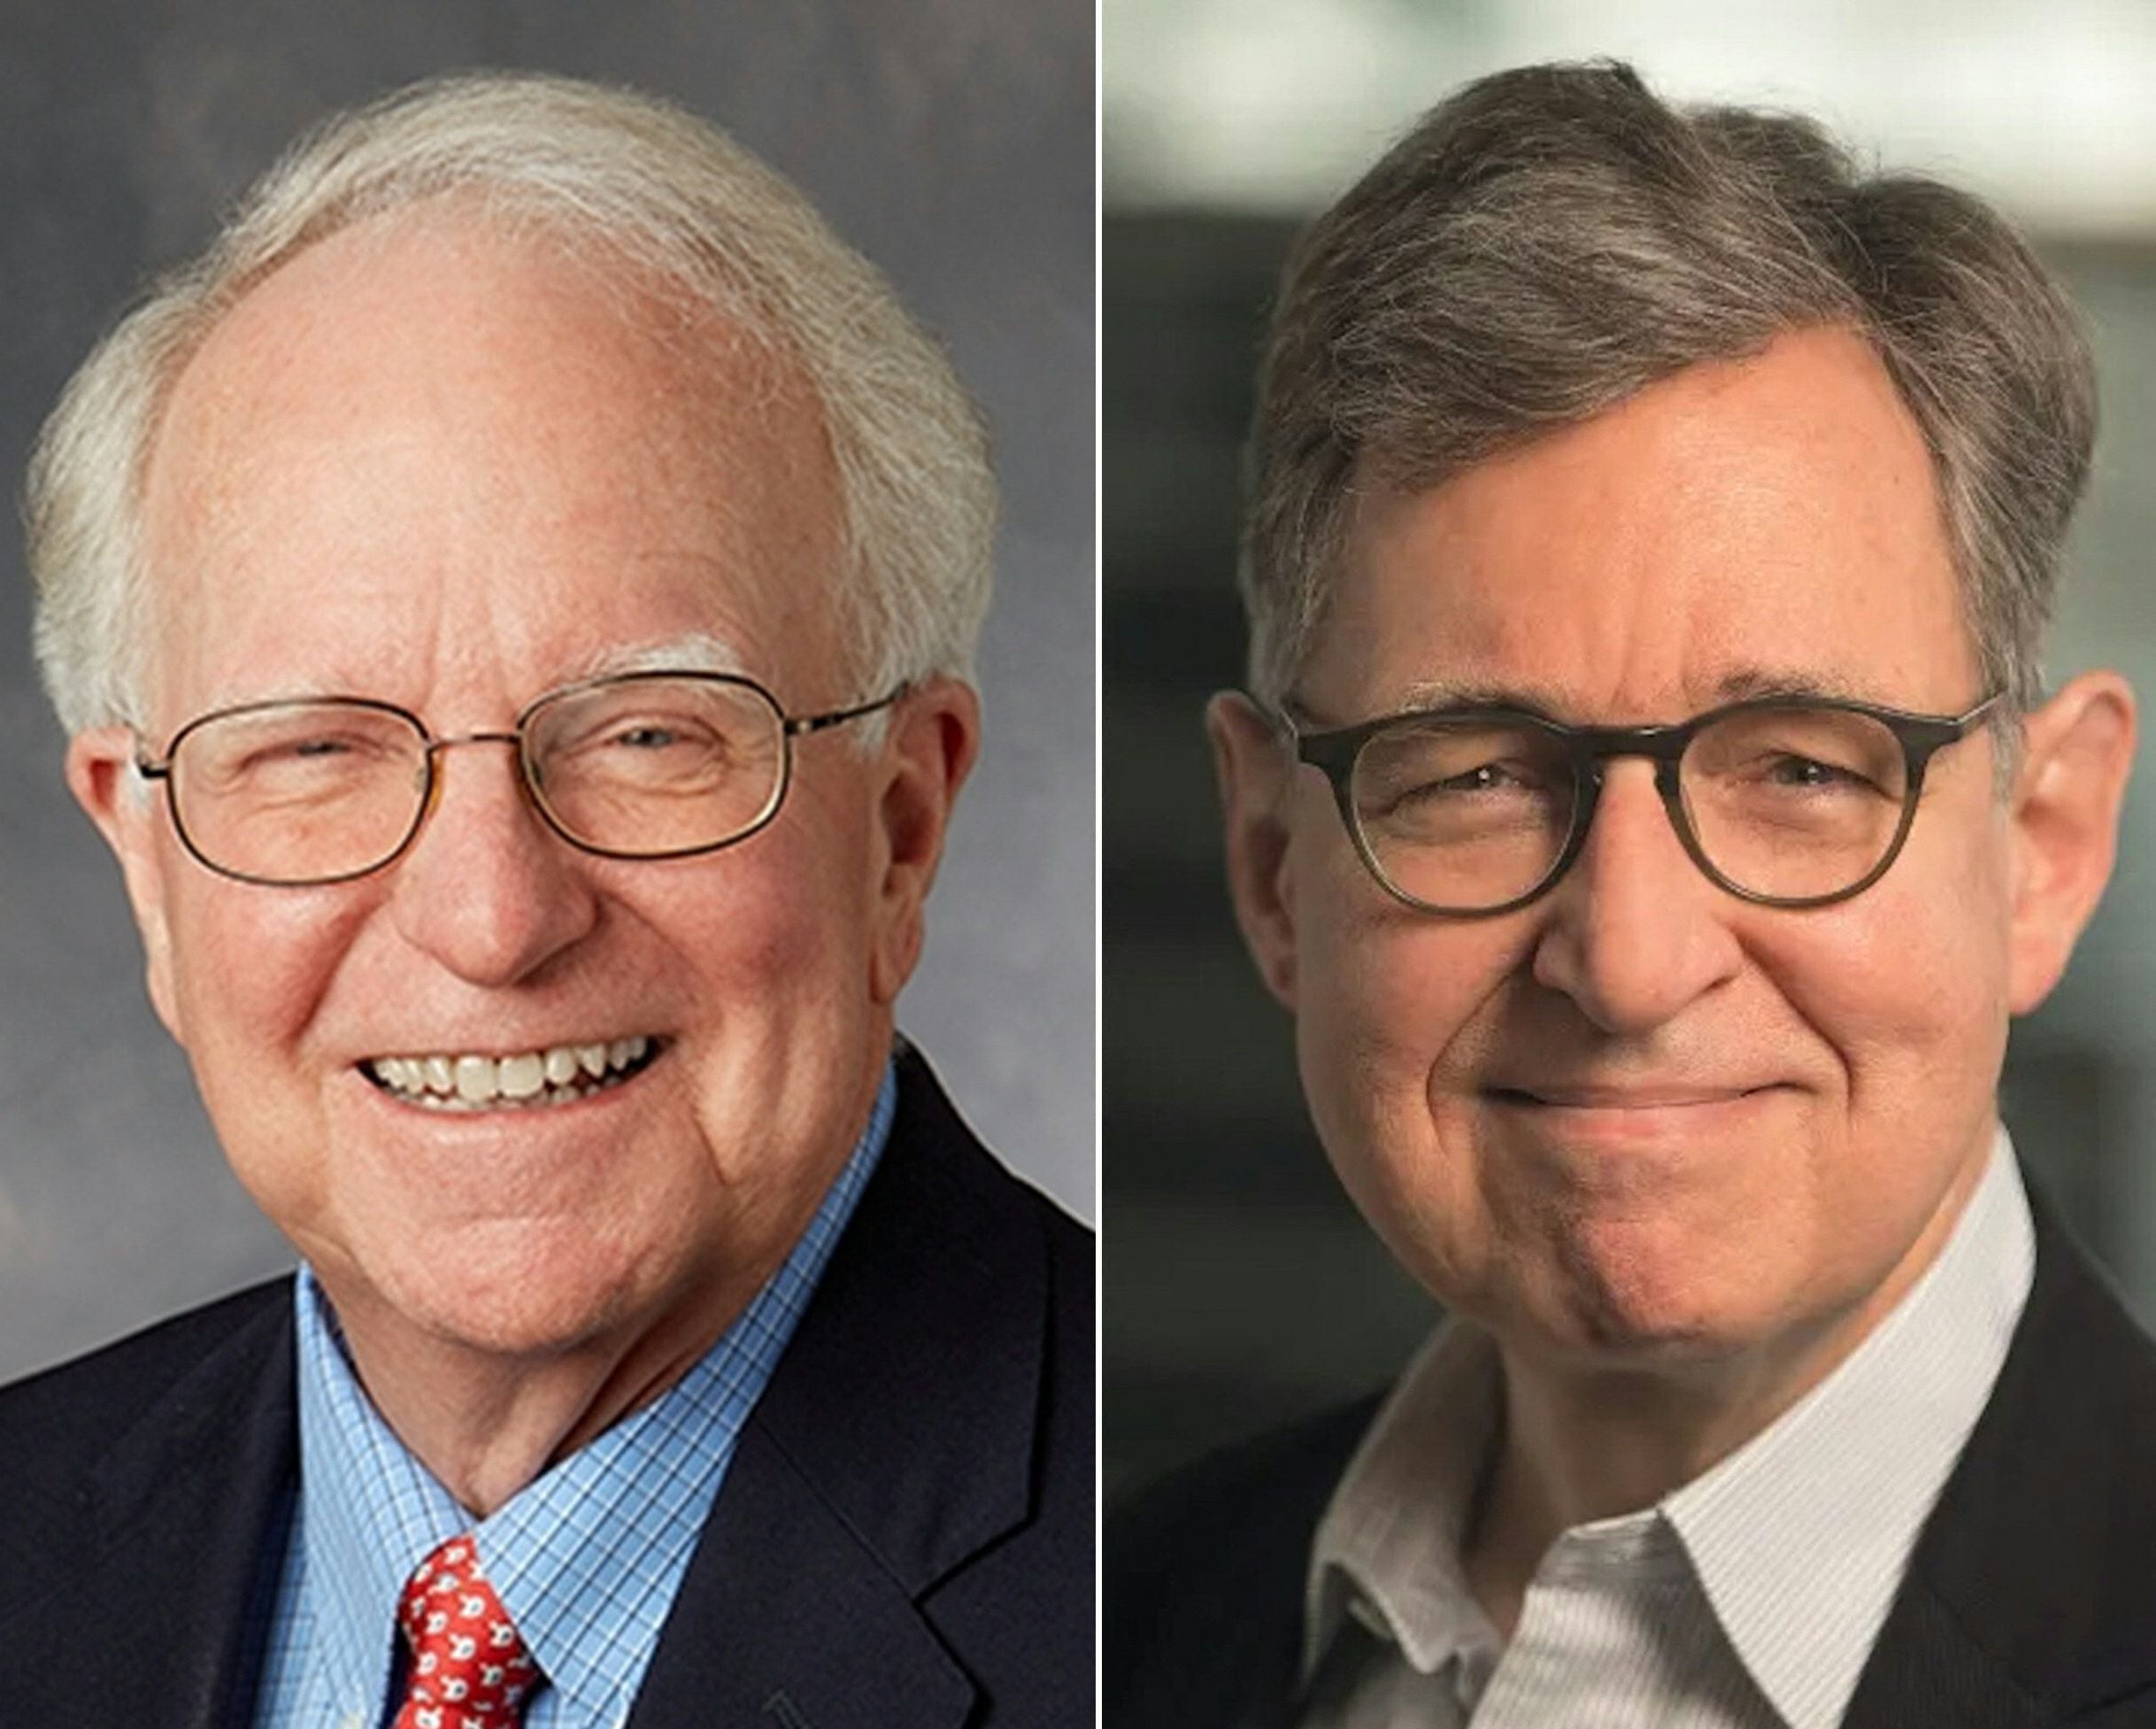
This year’s Nobel Prize in Economics was awarded to an American duo – Prof Robert Hall of Stanford University and Prof Michael Woodford of Columbia University – for their work on the “microeconomic foundations of macroeconomic stabilisation”.
Their research emphasised that keeping the economy on a steady path requires understanding how ordinary businesses and consumers make decisions at an individual level rather than treating them as a homogenous whole. The insights provided by their work could help us understand the potential trajectory of the Gulf economies as they continue to diversify away from oil.
In fact, the energy policies pursued by Arab oil-exporting countries during the 1970s contributed to the genesis of Prof Hall and Prof Woodford’s work, but the story begins much earlier.
Before the interwar period of the early 20th century, the kind of macroeconomic policy that is pursued by governments around the world today to stabilise their economies was essentially absent. Policymakers perceived the role of economic authorities very narrowly: balance the state budget and ensure liquidity in the financial system by managing the money supply and overseeing banks.
A key reason for this limited, self-imposed mandate was the lack of macroeconomic data, such as gross domestic product, consumer price inflation and unemployment figures. In other words, even if governments had a theory of how to intervene in the economy to soften the boom-and-bust cycle, they lacked the information needed to put it into practice.
Things changed between the First and Second World Wars for two reasons. On the one hand, the deepest economic crisis in modern history struck in 1929, making it essential for scholars and policymakers to develop methods of stabilising the economy. On the other hand, governments began collecting macroeconomic data systematically, equipping themselves with the tools needed for active macroeconomic management.
This process accelerated during the 1960s and 1970s, as the substantial expansion in data availability was complemented by advances in computing technology that enabled sophisticated statistical analysis. As a result, on the eve of the first oil shock in 1973, economic authorities around the world were well-versed in collecting macroeconomic data, as well as using fiscal and monetary instruments to smooth the economy’s peaks and troughs.
Crucially, policymakers relied on historical statistical relationships to guide their interventions. One influential example was the Phillips Curve, which linked higher inflation to lower unemployment.
Suppose historical data showed unemployment averaging 6 per cent when inflation was 2 per cent, but only 4 per cent when inflation was 4 per cent. Accordingly, when unemployment was actually 6 per cent and this was considered undesirably high, policymakers might loosen monetary policy through interest rate cuts to push inflation towards 4 per cent, expecting unemployment to fall towards 4 per cent as well. This approach assumed that the historical relationship would remain reliable when policymakers deliberately tried to exploit it.
However, the oil crisis of the 1970s exposed the inadequacies of this approach and set the stage for Prof Hall and Prof Woodford to contribute to a paradigm shift in economics. The tipping point was the phenomenon of “stagflation”: inflation and unemployment rising simultaneously, in direct contradiction to the conventional interpretation of the Phillips Curve. This left economic authorities in oil-importing countries bereft of ideas.
Prof Hall and Prof Woodford were part of a new cohort of economists who went back to basics. Rather than taking historical relationships between macroeconomic variables at face value, they recognised that each macroeconomic variable represents an aggregation of millions of microeconomic decisions.
For example, aggregate consumption across an economy is the sum of individual households’ consumption decisions. Accordingly, to understand how a macroeconomic variable behaves and how it relates to other macroeconomic variables, we must first understand the relationships between the underlying microeconomic variables from which these aggregate measures are derived.
Unemployment provides a good illustration. Economists must not treat economy-wide joblessness as the starting point for their statistical analysis. Instead, they must understand how individual members of the labour force and businesses make employment decisions and then build their analysis from the ground up.
The result of this novel way of thinking was a new generation of economic models with two features that their predecessors lacked.
First, they helped explain the phenomenon of stagflation and provided clear reasons for its occurrence, including the role of the energy shocks of the 1970s. Second, they offered governments a new set of tools for stabilising the economy. As the global financial crisis of 2008 demonstrated, the problem was by no means solved. Nevertheless, Prof Hall, Prof Woodford, their contemporaries and their successors have continued to advance our understanding of these issues.
In the context of the Gulf economies, the legacy of Prof Hall and Prof Woodford can be seen clearly in several aspects of macroeconomic policy.
The region’s success will ultimately depend on translating ambitious national strategies into millions of individual decisions that collectively sustain prosperity beyond oil
One of the most salient is the challenge of maintaining a sustainably high rate of economic growth. There is growing recognition that aggregate economic expansion depends on innovation at the level of small and medium-sized enterprises. Gulf governments understand that they must work from the bottom up rather than rely on fleeting relationships between observed economic growth rates and other macroeconomic variables.
In this regard, the subsequent work of other Nobel laureates – such as Paul Romer, Peter Howitt and Philippe Aghion – has been instrumental in shaping the region’s growth-enhancing policies, including subsidies for research and development and support for venture capital.
Another illustration of the influence of Prof Hall and Prof Woodford’s work is the Gulf currencies’ pegs to the US dollar (with the exception of the Kuwaiti dinar). These arrangements reflect the belief that investors and consumers are forward-looking decision-makers who value the certainty afforded by fixed exchange rates. They might be far more reluctant to spend and invest if Gulf currencies were to adopt a free-floating regime that exposed them to exchange-rate risk.
For the regional economies, the enduring lesson of Prof Hall and Prof Woodford’s work is that effective macroeconomic policy begins with understanding how households and businesses make decisions. As diversification progresses, policymakers will do well to ensure that their reforms encourage people to invest, innovate and create jobs while providing a credible framework for economic stability.
The region’s success will ultimately depend on translating ambitious national strategies into millions of individual decisions that collectively sustain prosperity beyond oil.