The KOSPI could climb to 7,600 by the end of this year and as high as 9,300 next year, according to a new outlook that argues share prices have fallen far more than corporate earnings forecasts justify.
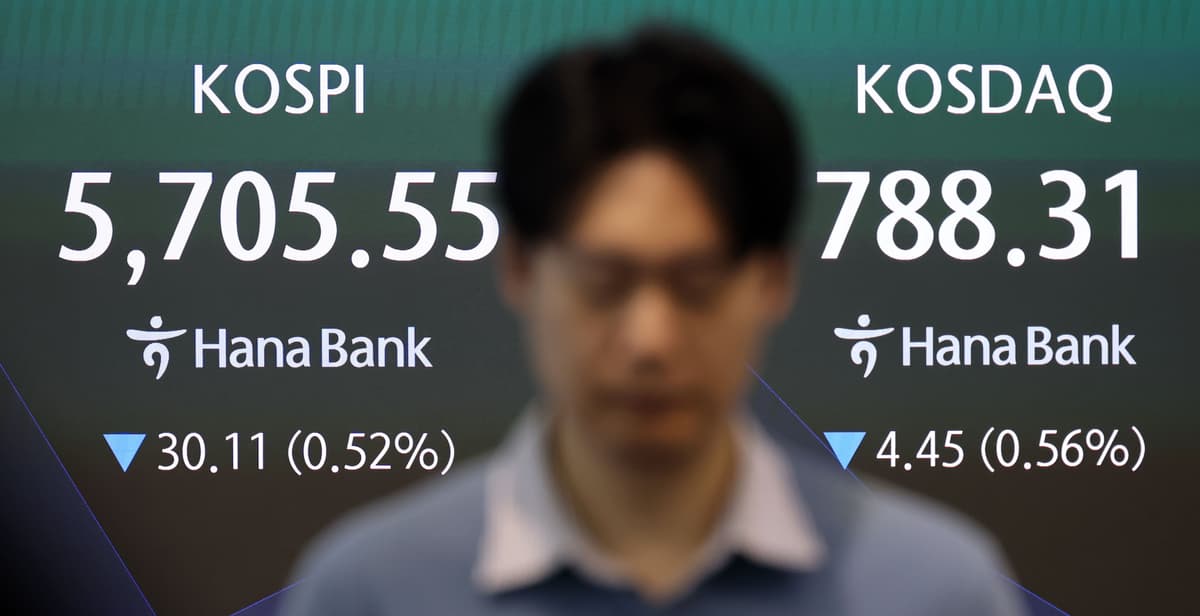
The benchmark index opened at 5,670.11 on the 22nd, down 65.55 points, or 1.14%, from the previous session, according to the Korea Exchange. Losses deepened in the afternoon, with the index falling below the 5,600 level for a decline of more than 3%.
Hanwha Investment & Securities recommended buying below the 6,000 level. In a 2027 equity outlook report released the same day, analyst Ha Jang-kwon set a KOSPI target of 8,500 for next year, with an expected trading range of 6,000 to 9,300. The 9,300 figure represents the upper bound of that range and is separate from the baseline target of 8,500.
On a quarterly basis, the brokerage projected the index at 7,600 in the fourth quarter of this year, rising to 7,700 in the first quarter of next year before a temporary pullback to 7,550 in the second quarter. From there, it mapped a path to 7,900 in the third quarter and 8,500 in the fourth. The forecast rests on an expected 22% increase in book value per share (BPS) next year. "Earnings expectations have stayed where they were, but prices collapsed first," Ha said. "Most of the gains will be concentrated in the fourth quarter of this year and the first quarter of next year, when a memory re-rating begins on the back of year-end long-term agreements (LTAs) and 2027 high-bandwidth memory (HBM) price negotiations."
Hanwha Investment & Securities said the KOSPI's forward 12-month return on equity (ROE) stands at 25.5%, an all-time high, while its forward 12-month price-to-book ratio (PBR) was just 1.08 times as of the 16th of this month. That is about half the roughly two times implied by the historical relationship between ROE and PBR. The forward 12-month price-to-earnings ratio (PER) is also in the four-times range, the lowest since 2010.
The bullish case, however, depends on corporate profitability holding up. Market consensus for the KOSPI's forward 12-month ROE at the end of next year rose to 22.7% as of the 15th of this month from 18.2% in March. Hanwha Investment & Securities pointed to expectations that the trough in profitability will be higher than in past cycles even if business conditions cool, while noting that the figure is a projection based on market estimates.
The brokerage advised weighting portfolios toward growth stocks such as semiconductors and information technology hardware through the first quarter of next year, then broadening into value stocks from the second quarter. In a phase of easing upward pressure on interest rates and a stronger won, it expects sectors including transportation, hotels and leisure, steel, banks and utilities to become relatively more attractive.