
Shares of refrigerated carrier Marten Transport were down 7% in midday trading on Friday, following a disappointing third-quarter report. Despite improving supply-demand fundamentals, a runup in fuel and health insurance costs, among other items, were a drag in the period.
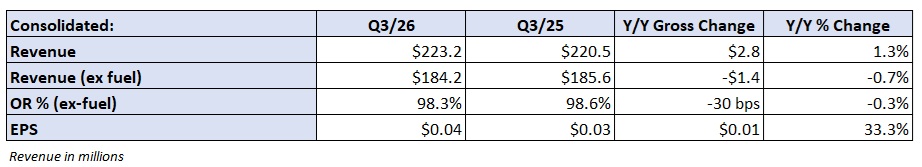
Mondovi, Wisconsin-based Marten (NASDAQ: MRTN) reported net income of $2.9 million, or 4 cents per share, for the third quarter. The result was a penny higher than the year-ago quarter but 2 cents light of the consensus estimate.
The company said higher fuel and wages and benefits costs, including driver pay increases, were only partially offset by an increase in gains on equipment sales. The net impact was $3.7-million hit to net income, or 4.5 cents per share.
Consolidated revenue of $223 million was 1% higher year over year. The 2025 sale of its intermodal unit to Hub Group (NASDAQ: HUBG) presented a $9.9-million revenue headwind during the quarter.
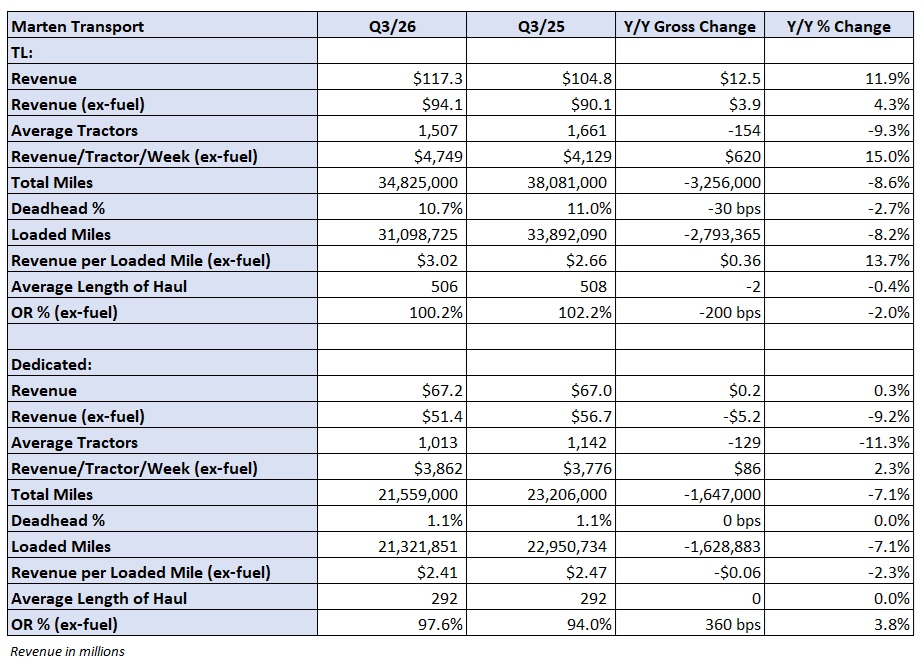
One-way truckload revenue increased 12% y/y to $117 million. Excluding fuel surcharges, revenue was up 4% y/y as revenue per tractor per week (ex-fuel) increased 15% on a 9% smaller fleet.
Marten has been managing truck counts to improve asset utilization. Deadhead was down 30 basis points y/y to 10.7%. Revenue per loaded mile (ex-fuel) increased 14% y/y to $3.02. The unit was unprofitable at a 100.2% operating ratio (ex-fuel), 200 bps better y/y, but 280 bps worse sequentially.
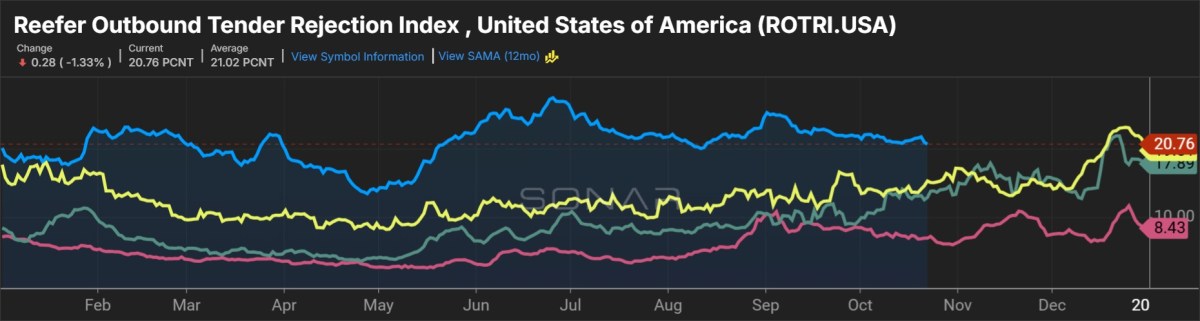
The dedicated segment reported a 9% y/y decline in revenue (ex-fuel) as an 11% decline in the truck count was only partially offset by a 2% increase in revenue per tractor (ex-fuel). Revenue per loaded mile (ex-fuel) was down 2% y/y to $2.41. The unit logged a 97.6% OR (ex-fuel), 360 bps worse y/y and 220 bps worse sequentially.
(Marten does not host a quarterly call.)
“The truckload freight market has sharply tightened since earlier this year as renewed and enhanced enforcement of federal and state law is removing a meaningful amount of noncompliant and unqualified driver capacity from the marketplace,” said Randy Marten, chairman and CEO, in a news release. “We are securing higher pricing from our customers for our premium services while enhancing freight quality across our network within these early stages of the freight market upcycle.”
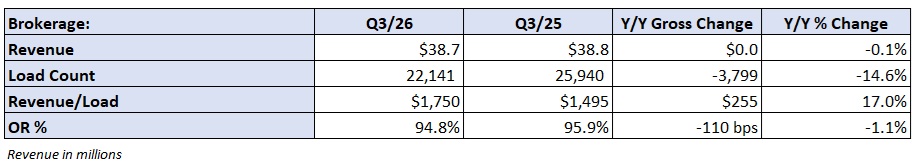
Brokerage revenue was flat y/y at $39 million as a 15% decline in shipments was offset by a 17% increase in revenue per load. The unit’s OR improved 110 bps to 94.8%, flat with the 2026 second quarter.
Cash flow from operations was $83 million in the first nine months of 2026, a 5% y/y decline. The company maintained a debt-free balance sheet in the period.
The average age of its tractor fleet was 2.5 years compared to 2.2 years in the year-ago quarter.
Shares of MRTN are down 37% since a mid-June peak.
Why it matters? Marten Transport is viewed as a “refrigerated pure play.” It is the only public carrier in the reefer market and its quarterly results serve as a bellwether for the industry.
More FreightWaves articles by Todd Maiden:
- Knight-Swift again eyes big rate increases as new bid season nears
- Heartland Express sees earnings turnaround in Q3
- Werner Enterprises issues Q3 profit warning
The post Cost pressures sink Marten Transport’s Q3 appeared first on FreightWaves.