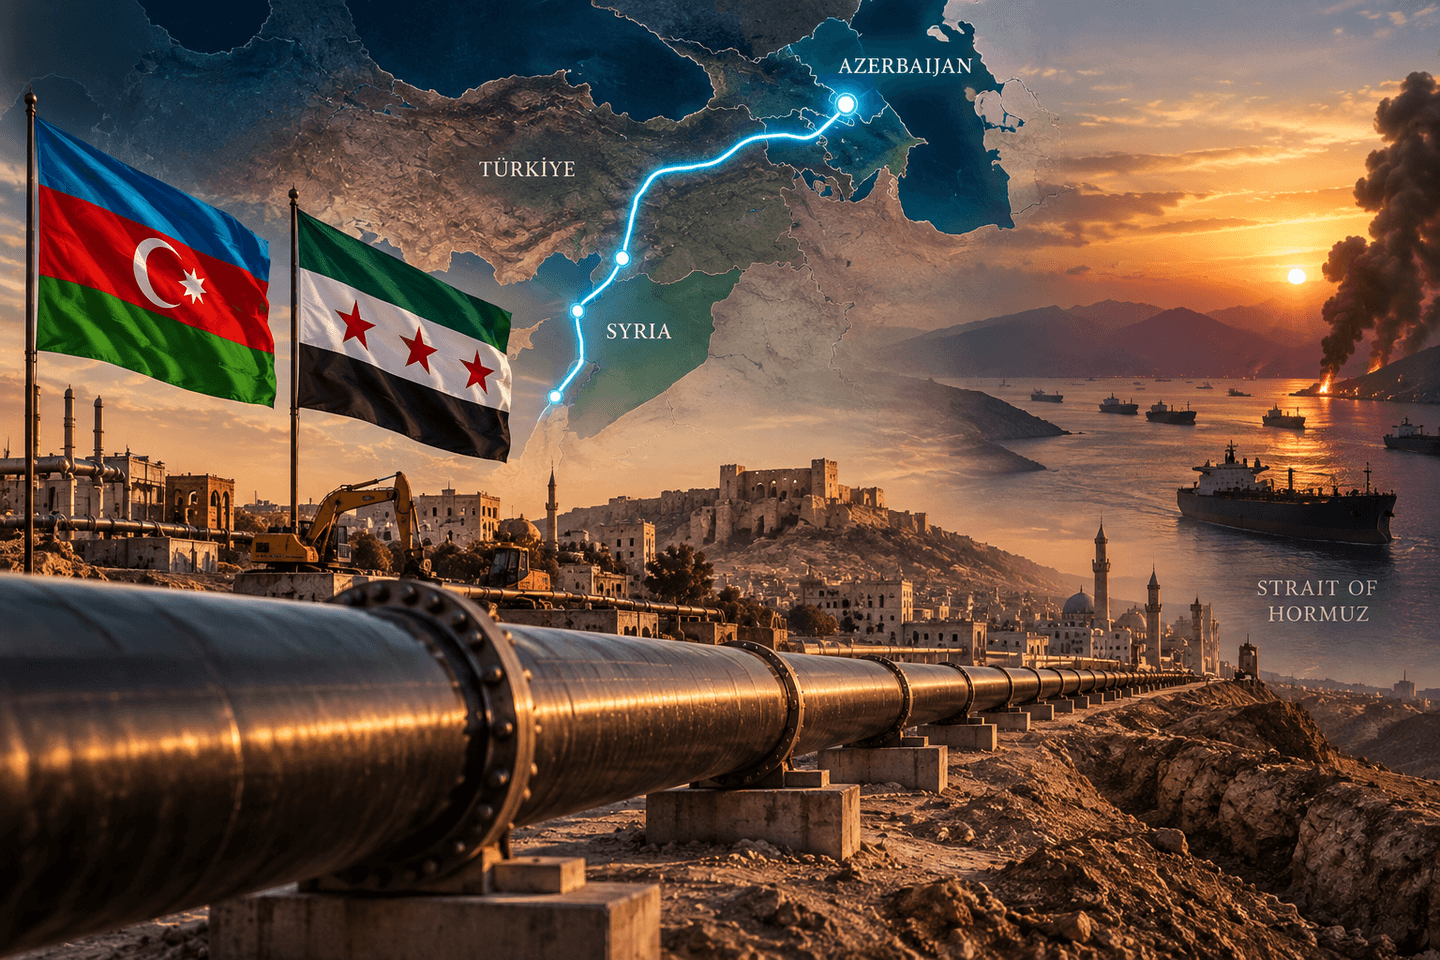
Energy security has come to be defined by access. Following the American and Israeli strikes on Iran on February 28th, the Strait of Hormuz, which regularly accommodates over a fifth of all global oil shipments, has been closed or greatly restricted. The effect has been described by the International Energy Agency as the biggest-ever disruption to oil supply since the formation of the oil market. Strikes against energy facilities in the Gulf region have continued, with strikes against Qatar's Ras Laffan facility on March 18th leading to a reduction in the state's LNG production capacity of some 17%. In early September, crude prices touched $109 per barrel on renewed strikes against shipping traffic.
In view of these considerations, a 186km-long pipeline through the Syrian countryside should garner more recognition than it has to date. On September 29th, the Syrian state petroleum firm and Qatar’s UCC Holding launched the second section of Phase II of the Arab Gas Pipeline, a 36-inch pipeline stretching from Homs to Aleppo. It forms a chain of about 566km linking the Jordanian border to the Turkish border and is able to transport gas in both directions. At the northern end, there is a resource that was not available when planning the project: Azerbaijani Caspian gas.
Construction of the Arab Gas Pipeline began many years ago to transport gas from Egypt to the Levant countries. However, the 64 km-long Kilis-Aleppo pipeline, which forms the northern part of this gas pipeline, started operation in 2011 before being shut down following the outbreak of the Syrian civil war. Rehabilitation of the pipeline occurred in 2025, and the pipeline was connected back to the electricity grid of Turkey. On August 2nd of that same year, SOCAR announced that it would be exporting 1.2 billion cubic meters of gas annually via the pipeline.
With the construction of the new line, the pipeline becomes a network. After its completion, within 22 months, Homs-Aleppo will be capable of transporting 11 million cubic meters per day, with provision for doubling the capacity to 22 million, and gas will flow from the Turkish border to Homs, the Jordanian border and even further. Initially, gas will flow between the two cities using the existing domestic pipeline network in Syria.
What changed in the Gulf?
Egypt, which was an original supplier of gas via this pipeline, stopped supplies to Syria and Lebanon as early as March 1st due to rising local demand in connection with the Hormuz crisis, as a vivid example of how vulnerable traditional suppliers were. Jordan managed to reach an agreement for delivering 4 million cubic metres a day via the southern part of this pipeline. Europe, which gets 12% to 14% of its liquefied gas from Qatar via Hormuz, has faced the same vulnerabilities but as a consumer.
After halting their attacks for nine months, the Houthis started attacking ships on July 22nd. They attacked at least four tankers, blocked the navy of Saudi Arabia, and, in September, seized the Yemeni port of Mokha and the islands in the Bab el-Mandeb strait. The forces that are supported by Saudi Arabia are fighting back. Even the bypass solutions available in the Gulf region, like the pipeline of Saudi Arabia connecting East-West to the Red Sea, are strained. This is why other ways that can circumvent these two waters are valued more than ever before.
A consortium consisting of UCC Holding of Qatar, Kalyon and Cengiz of Turkey, and Power International Holding of the US entered into a $7 billion deal with the Syrian Ministry of Energy last year to construct eight gas and solar power plants. They hope to meet more than half the electrical needs of the country, which has had its electrical grid destroyed by years of warfare. Pipes without power plants are pipes; power plants without gas are just monuments. The two are interdependent.
Azerbaijani molecules, Turkish transit and building, Qatari money, and American investment are operating in the same project in a state that until late 2024 had been an international pariah. It is an unlikely alliance but an interesting one indeed. The Syrian interim government does not have much capital itself; its allies have the capital, but lack the route.
The strategy of Iran has always depended on one thing – that it would be able to pose a threat to those supply routes for energy that go into the world. War has proven that theory false, and therefore created other possibilities more attractive. Each cubic meter of oil that moves overland from the Caspian Sea to the Levant cannot be threatened by mines and missiles of Tehran.
It would be inaccurate to claim that this is a case of Azerbaijan isolating itself from Iran. Azerbaijan continues to be one of the important partners of Iran in terms of providing electricity and being a transit hub; at the end of September, Iran's national electricity company requested additional supplies of electricity before winter from Azerbaijan, with both parties promising more speedy development of the North-South route. The correct way of expressing the matter is that of leverage. Azerbaijan is positioning itself as a transit country for energy supplies to different regions: Europe via the Southern Gas Corridor, which Azerbaijan promised to increase its gas supplies to the level of 20bn cubic metres a year by 2027, and now the Levant region.
Since the Qatari grant ended in August, Syria has been responsible for the total costs of importing Azerbaijani gas, which has become difficult to afford since the country’s coffers have become nearly empty. Syrian energy experts argue that the country may actually turn out to be just a transit route instead of a center as intended by its leaders due to its dependence on foreign gas, foreign money, and foreign companies. Security is still a problem; the lifting of sanctions remains unfinished, and there is also a war on its borders.
Nevertheless, there are certain things which have become clear. The war that blocked the world’s key energy bottleneck forced governments to develop alternative pipelines that would not use this bottleneck.