
Hurricane Isaias, which killed four people and left hundreds of thousands without power across the Southeast over the weekend, is the first real test of Florida’s troubled home insurance market since Hurricane Milton struck in October 2024.
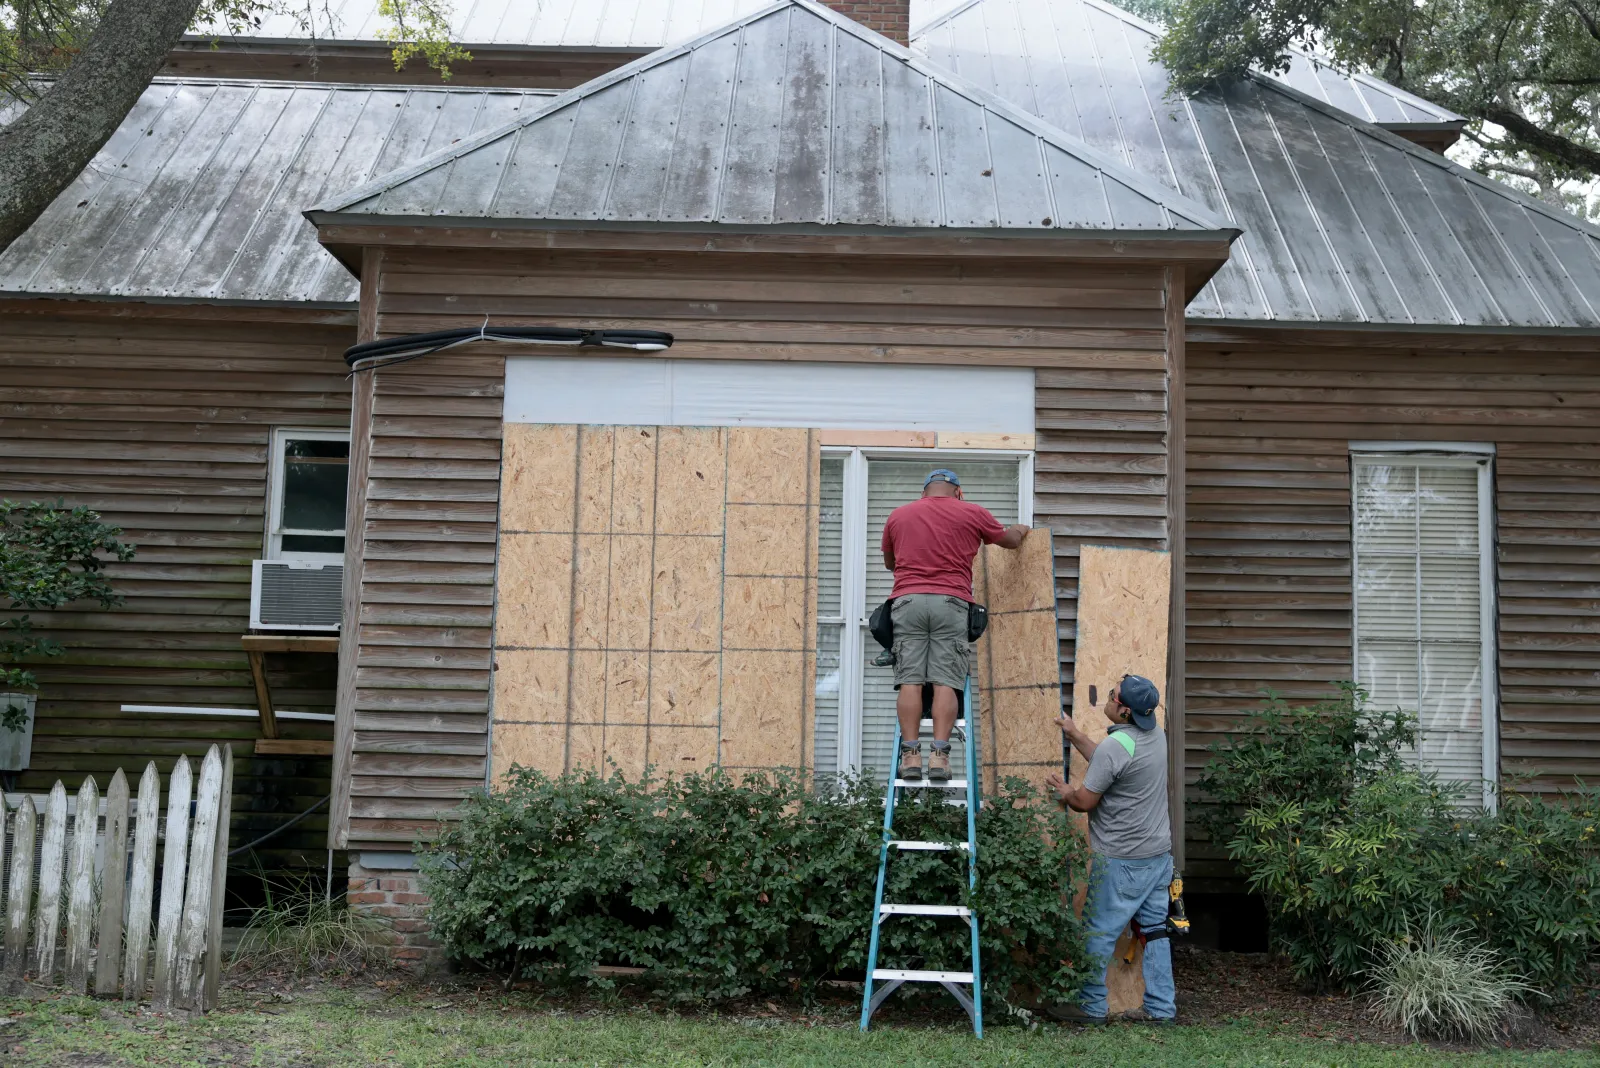
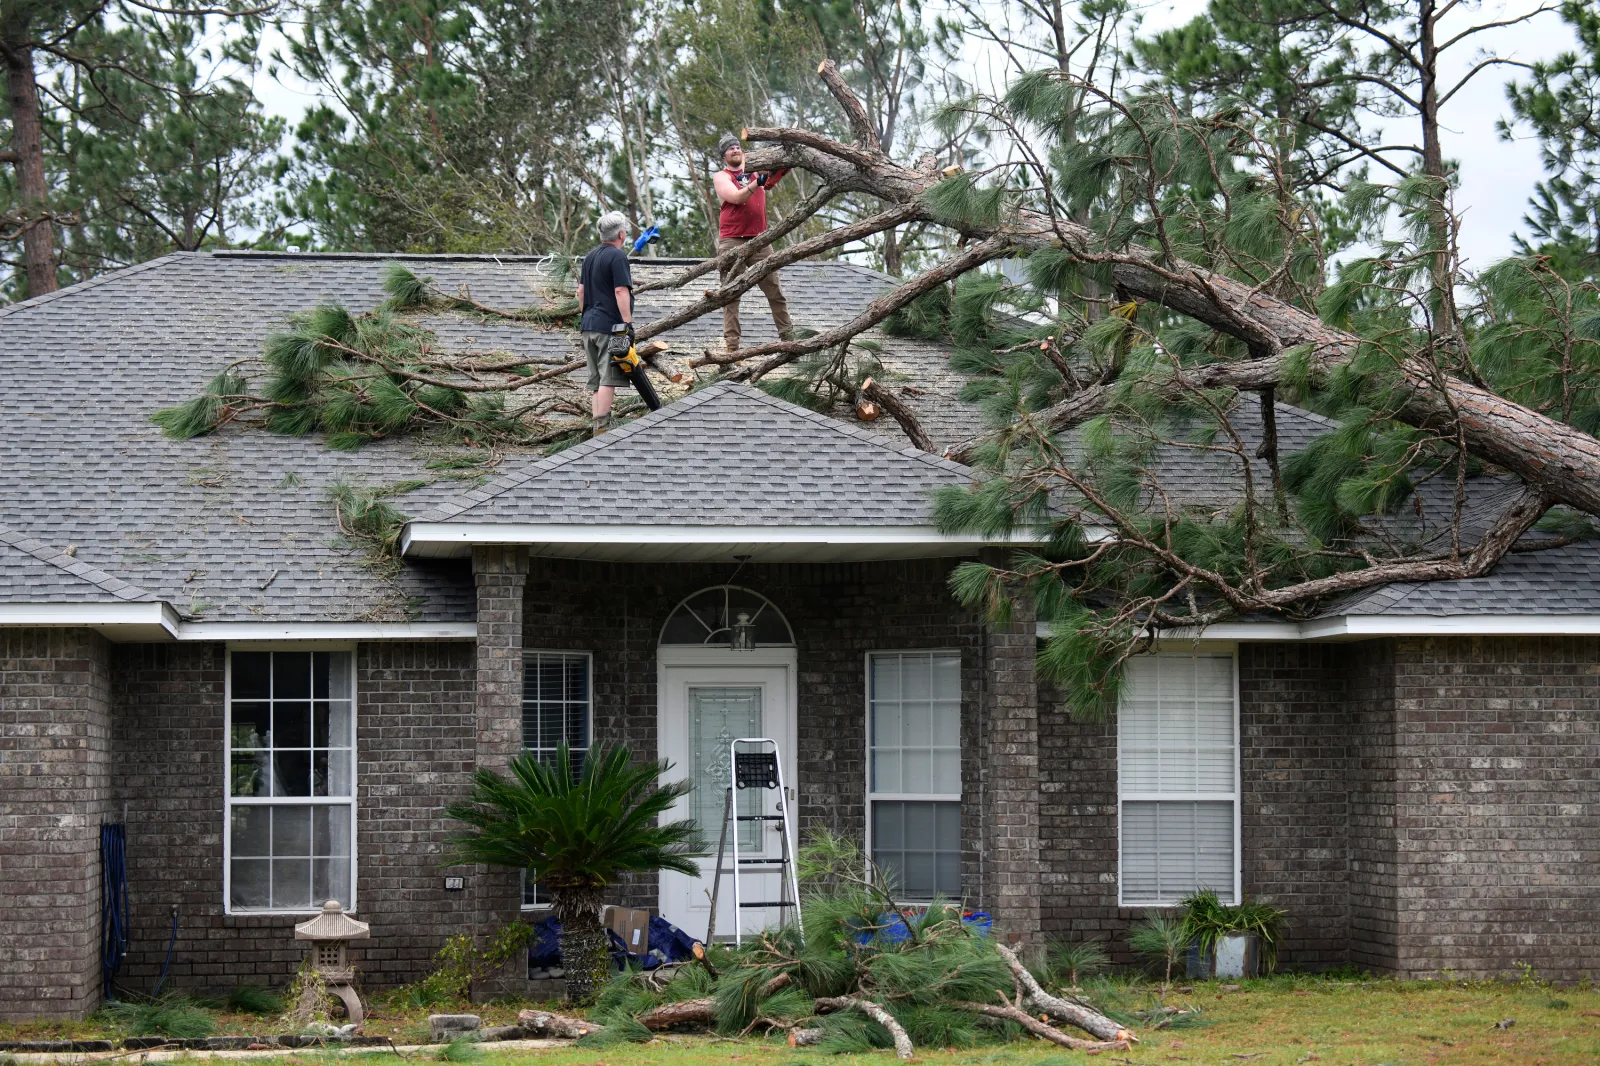
After briefly reaching Category 3 strength on Friday, Isaias made landfall near Destin, Florida, as a Category 2 hurricane that night, bringing heavy rain and powerful winds to the Panhandle before moving north. The storm downed trees and power lines and killed four people, two in Escambia County, Florida, and two in Alabama.
It was the first Atlantic hurricane of the season and the first to strike the continental U.S. since Milton battered Florida in 2024. That storm, which made landfall as a Category 3 hurricane, caused an estimated $34.3 billion in damage in the U.S. This was "almost exclusively in Florida," according to NOAA’s National Centers for Environmental Information.
...
Since then, Florida’s home insurance sector, which endured an exodus of private carriers and years of steep premium increases, has been gradually stabilizing, according to experts and officials.
But that recovery could now be tested by Isaias and any further storms that strike before the Atlantic hurricane season ends.
How Isaias Compares to Milton
Milton, one of the strongest Atlantic hurricanes on record, slammed into Florida’s western coast near Sarasota in the fall of 2024, just two weeks after Hurricane Helene wreaked havoc in the state.
In the immediate aftermath, real estate analytics firm CoreLogic, now known as Cotality, estimated that Milton caused between $21 billion and $34 billion in total wind and flood damage, including losses to uninsured properties. But it estimated insured losses at a lower $17 billion to $28 billion.
That meant that many homeowners in Florida found themselves having to cover the cost of rebuilding their properties on their own.
As of December 2025, the Florida Office of Insurance Regulation (FLOIR) reported a total of $5.6 billion estimated insured losses linked to Milton. Of a total of over 300,000 claims made since then, over 114,000 were closed without payment and over 8,000 remained open without payment. Many of these closed without payment were not paid because the homeowners’ policies did not cover flood damage.
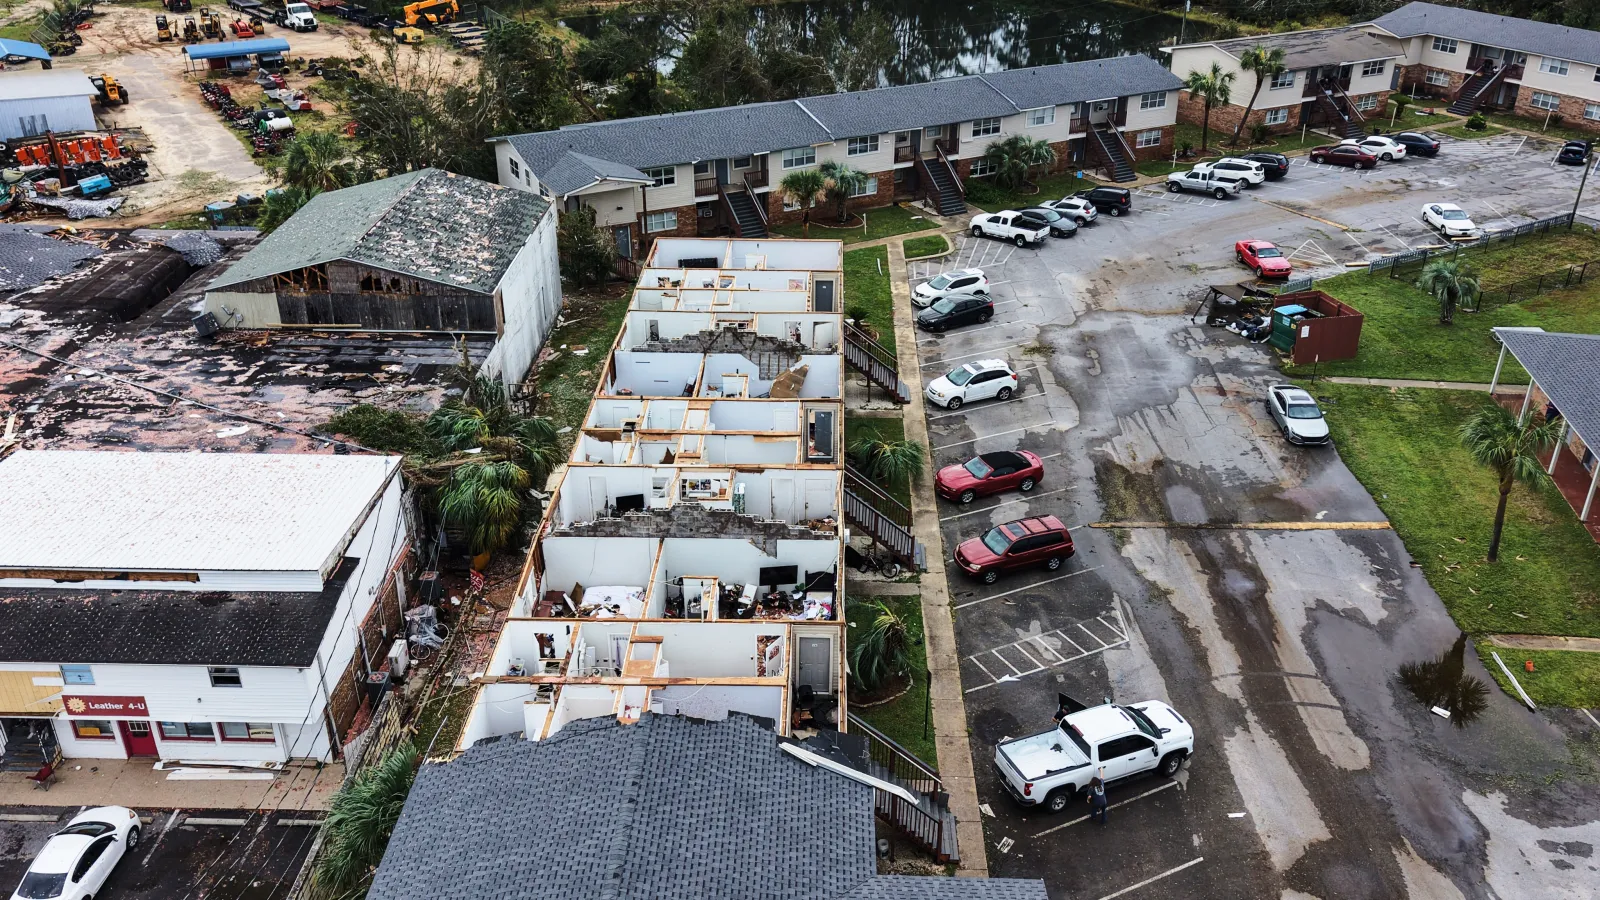
The damage caused by Isaias on Florida’s Panhandle over the weekend is still to be fully assessed. A Cotality assessment found that about 353,000 homes in Escambia, Santa Rosa, Okaloosa and Walton counties were at moderate or greater risk of wind damage, representing about $115.8 billion in reconstruction cost value.
...
On Friday, researchers estimated that 46,000 homes in Destin only were at moderate or greater risk of storm surge damage, representing about $15.4 billion in reconstruction cost value. About 153,000 homes in the same metro faced moderate or greater hurricane wind risk, with about $49.7 billion in reconstruction cost value.
Overall, Isaias seems unlikely to rival Milton in financial terms, with pre-landfall estimates for Isaias putting insured losses in the mid-single-digit billions. Newsweek contacted FLOIR and Cotality for comment by email on Monday morning and awaits responses.
What Has Changed Since Milton
Between 2019 and 2022, Florida was swept by a home insurance crisis as premiums soared and insurers struggled with a combination of hurricane risk, rising reinsurance costs, litigation and fraud.
By 2022, insurers were failing, premiums were soaring and homeowners were finding it increasingly difficult to secure coverage or afford the one available. Six Florida insurers became insolvent that year alone, while others stopped writing or renewing policies.
Lawmakers in the state decided to intervene with a sweeping tort reform that experts and officials say has since helped stabilize the market, attracting new carriers and slowing the pace of premium growth.
"Florida’s insurance market has shown vast improvement since legislative reform addressed the factors causing the state’s man-made risk crisis: legal system abuse and assignment of benefits claim fraud," Mark Friedlander of the Insurance Information Institute (Triple-I) told Newsweek.
"New lawsuit filings have declined 50 percent since 2020, reducing legal defense expenses for insurers. This has led to statewide rate reductions. During the first half of 2026, average home insurance premiums decreased in 51 of 67 Florida counties."
Additionally, the state’s insurer of last resort, Citizens Property Insurance Corp., which had ballooned in size beyond sustainable levels during the pandemic years, "has reduced its risk exposure by more than 1 million customers via depopulation as a stabilized private market has taken on this risk," Friedlander said.
...
"Citizens has reached a historic low of less than 300,000 active policies, with market share declining from 15 percent to 2 percent. More than 20 new insurers have entered Florida, and existing national and regional insurers are growing their market share across the state," he added.
But premiums have continued to increase in the state, even though at a slower pace than before, and Florida homeowners still pay the highest price for coverage in the nation. Between 2021 and 2025, Florida homeowners’ insurance premiums rose 75 percent, nearly double the national average. This is according to a report from national nonprofit group the Coalition for an Insurable Future.
The average home insurance premium in the Sunshine State is currently $8,471 per year for a policy with $300,000 in dwelling coverage, $300,000 in liability, a $1,000 deductible and a 2 percent hurricane deductible, Insurance.com reported.
Insurify predicts a 2 percent increase from 2025 by the end of 2026.
Is Isaias Finding Florida Better Prepared?
Billions in losses could reverse the softening in premium growth that the state has been enjoying over the past couple of years, John Sence told Insurance Business. He is chief sales officer at SageSure, a Managing General Underwriter (MGU) and third-party administrator specializing in catastrophe-exposed, high-risk property insurance markets.
"It could, particularly if losses are severe and concentrated in a region," Sence said. "The impact depends on the size of the losses, who absorbs them, and how capital providers respond afterward."
Newsweek contacted Sence for comment by email on Monday morning and is awaiting a reply.
But Isaias will be key to exposing how much progress Florida has made to fix its flood insurance gap over the past two years.
Despite signs of improvement, the state’s home insurance sector remains severely strained and expensive—so much so that many cannot afford to pay for flood coverage, which is not included in standard policies, or choose to do without it. Many mistakenly believe their standard policy covers flooding.
Friedlander said the average flood insurance premium in Florida is about $894 per year. These are available through the National Flood Insurance Program (NFIP) or private insurers. The average cost of flood insurance in Florida is $938 per year for a policy from NFIP, according to NerdWallet.
The existing flood insurance gap is a nationwide problem, rather than just a Florida one. A recent report on flood risk by the U.S. Government Accountability Office found that 86 percent of high-risk properties don’t have flood insurance.
But, for a state as vulnerable to flooding as Florida, this gap is an issue that could become increasingly harder to ignore. Experts warn this year’s El Niño could become "very strong," increasing flood risk from the Southwest to the Gulf Coast and Florida.
Newsweek’s reporters and editors used Martyn, our AI assistant, to produce this story. Learn more about Martyn here.
Contact Newsweek editors on this story: Ben Kelly and James Debens