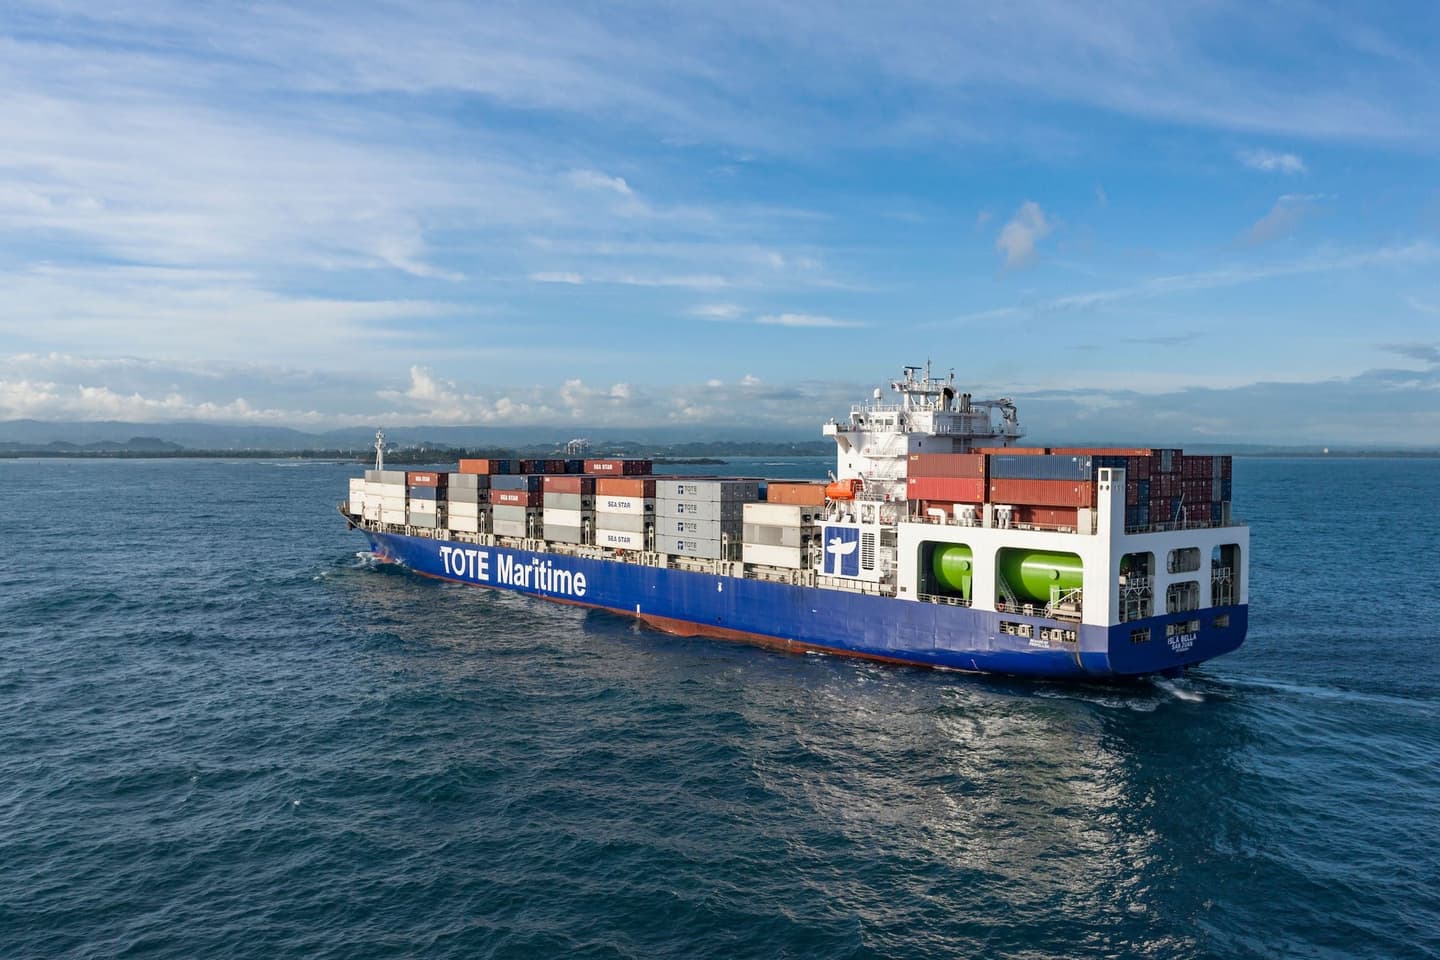
For a decade, LNG has been sold to shipowners as the sensible bridge fuel. Cleaner than heavy fuel oil, widely available and backed by mature engine technology, it has won the newbuilding argument comprehensively.
By Paul Morgan (gCaptain) – The numbers bear that out. SEA-LNG’s 2026 mid-year market review puts the LNG-fuelled fleet, in service and on order, at more than 1,550 ships. When the coalition was founded in 2016 the figure was 81.
Ordering shows no sign of easing. DNV data quoted by SEA-LNG shows 73 LNG dual-fuel vessels ordered in the first half of 2026, around 90% of all alternative-fuel orders. August alone added 46 more, driven by container ships and car carriers.
Yet the fuel carries a weakness that the industry has spent years talking around. Not all of the methane that enters the cylinder is burned. Some passes straight through to the funnel, and methane is a far more potent greenhouse gas than CO2 over any meaningful timescale.
Until recently, that slip was largely a reputational issue. As of this year it is a line on the invoice. Since 1 January 2026, the EU Emissions Trading System has covered methane and nitrous oxide from ships, not just CO2. The same date brought the end of the phase-in, with operators now surrendering allowances for 100% of their verified in-scope emissions.
FuelEU Maritime already counts methane slip in its greenhouse gas intensity calculation. Its default value for an uncertified engine is 3.1% of fuel consumed. That number now matters a great deal, because it is multiplied across every tonne of LNG burned on EU-related voyages.
The awkward question is whether 3.1% reflects reality. The best available independent evidence suggests that, for the most common engine type, it does not.
The FUMES project, published in January 2024 by the International Council on Clean Transportation with Explicit and the Dutch research organisation TNO, measured methane in the exhaust plumes of 18 LNG-fuelled ships. Drones, helicopters and onboard stack measurements were all used.
For low-pressure dual-fuel four-stroke engines, the workhorse of the LNG fleet, average real-world slip came out at 6.4%. That is roughly double the EU’s 3.1% assumption and well above the IMO’s 3.5%.
Slip was worst at low engine loads, exactly where many ships spend a large share of their operating hours. The ICCT recommended that regulators raise the default for this engine class to at least 6%.
The other side of the ledger is equally telling. In May 2026, MSC Cruises became the first cruise line to secure independent verification and flag state recognition of measured methane slip for FuelEU purposes.
Bureau Veritas verified values of 1.67% on MSC World Europa and 1.48% on MSC Euribia, both well under the default. The campaign followed IMO Resolution MEPC.402(83), which sets the reference measurement method, along with the European Commission’s FuelEU guidelines.
Engine makers are moving in the same direction. Wärtsilä reports weighted average slip of about 0.9% for four-stroke engines fitted with its NextDF technology, and says slip from its dual-fuel engines has fallen 75% over 25 years.
Put those figures side by side and the lesson is plain. Methane slip is not a single number. It varies by engine design, by age, by load profile and by how a ship is actually operated.
A default factor smooths all of that into one convenient average. For the worst performers it understates the climate impact. For the best it overstates their compliance cost. Either way, it tells an owner very little about their own ships.
That is why measurement has to come before abatement. An operator cannot sensibly invest in a catalyst, or defend a measured value to a verifier, without first knowing what is actually leaving the stack.
The industry has been building that knowledge collectively. In September 2022, Safetytech Accelerator, set up by Lloyd’s Register, launched the Methane Abatement in Maritime Innovation Initiative, known as MAMII.
Its founding backers included Maran Gas Maritime, MSC, Carnival Corporation, Seaspan, Shell, Knutsen and Lloyd’s Register. The aim was to identify, test and champion technologies that measure and reduce methane from LNG-fuelled shipping.
Its first round of feasibility studies, reported in 2024, selected four companies from twenty applicants. Each attacked the exhaust problem differently.
CDTi Advanced Materials proposed passive oxidation catalysts, reporting 80% methane conversion at lower temperatures across a range of engine loads. Daphne Technology offered a plasma-catalysis unit fitted in the exhaust, with the study assuming 80% removal.
Plenesys took a different route altogether, using plasma torches to crack methane into hydrogen and solid carbon, with the hydrogen fed back to the engine. It reported a 78% cut in slip. Rotoboost proposed thermo-catalytic decomposition to make hydrogen on board as a drop-in blend with LNG.
A second round, reported in January 2025 with Chevron, Carnival, Shell and Seapeak, turned to fugitive methane, the leaks and venting that occur between the bunker manifold and the engine.
Xplorobot assessed handheld devices and an AI platform for leak quantification, Sorama scoped acoustic cameras that map sound to pinpoint leaks on an LNG carrier’s trunk deck, and Framergy studied a metal-organic framework material to capture vented methane.
The results were encouraging but sobering. Xplorobot’s assessment was a desktop exercise based on comparable onshore data, with accuracy of around 30% for larger leaks and about 50% for smaller ones. Sorama’s work scoped a six-month pilot rather than reporting one.
That gap between the laboratory and the engine room is where many promising ideas falter. A tool designed to sniff out a leaking valve flange is of no use in a hot, fast-moving exhaust plume. A stack analyser, however accurate, cannot tell an engineer which joint is weeping in the gas valve unit room.
Each emission source needs its own instrument, and each instrument has to survive the realities of a working ship. Space is tight, gas-hazardous areas impose strict equipment rules, and anything added to the exhaust line affects back-pressure on the engine.
Fuel chemistry adds another trap. Research from Finland’s VTT, published in 2021, found that methane oxidation catalysts on lean-burn LNG engines are very sensitive to sulphur poisoning. Efficiency fell over time and only daily regeneration restored it.
That is not an argument against catalysts. It is an argument for proving them at sea, under real loads, over real operating hours, before calling the problem solved.
Some of that proof is now arriving. In Japan, a NEDO-funded project involving Kanadevia, Yanmar Power Technology and Mitsui O.S.K. Lines fitted a methane oxidation catalyst combined with exhaust gas recirculation to the Panamax bulk carrier Reimei.
Sea trials began in May 2025. At around 75% engine load the system cut methane slip by 98%, a result verified by ClassNK. Land tests in December 2023 had already recorded 93.8% at full load.
The partners are careful to note that trials continue through 2026 to test durability and long-term performance, with commercial availability targeted from 2027.
MAMII’s first members’ event in Brussels, in late November 2025, struck a similar note. Participants heard that several engine types had already cut slip by 60% to 70% in recent years, and that aftertreatment could deliver a further 80% to 90%.
Shell’s in-house methane catalyst was due to begin shipboard trials in December 2025, the third aftertreatment trial among MAMII members. Early results across the member trials were described as positive, with commercial readiness possible as soon as 2027.
Class involvement has been a common thread in the projects that have progressed. ClassNK verified the Japanese results. Bureau Veritas underpinned the MSC certification. Lloyd’s Register sits at the heart of MAMII itself.
For technology developers, that is the practical lesson. Engaging class societies and engine builders from the outset, rather than after the prototype is built, smooths the path to approval and to an owner’s purchase order.
Several gaps remain. Too few onboard pilots use common measurement methods, which makes their results hard to compare. Too little verified real-world data reaches the public domain.
Fugitive emissions from bunkering, cargo handling and floating regasification have received far less attention than the funnel. And the cost of early trials still falls mostly on a small group of pioneering owners and developers.
The regulatory calendar adds urgency. The IMO’s Marine Environment Protection Committee meets for MEPC 85 from 30 November to 3 December 2026. The resumed extraordinary session that will decide on adopting the Net-Zero Framework is scheduled for 4 December.
Whatever emerges from London, the direction is set. Europe is already pricing methane, and the global framework under negotiation is built on well-to-wake greenhouse gas intensity.
For owners of LNG tonnage, that changes the calculation. A ship that can prove low slip earns a lower compliance bill. One that cannot will carry the default, or worse if defaults are revised upwards as the ICCT has urged.
LNG won its place in the orderbook on the promise of lower emissions. Keeping that place now depends on proving it, measured at the stack, verified by a third party and demonstrated at sea.

Subscribe for Daily Maritime Insights
Sign up for gCaptain’s newsletter and never miss an update