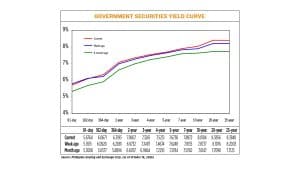
YIELDS on government securities (GS) climbed last week as the peso’s weakness, elevated inflation, and expectations of another rate hike from the Bangko Sentral ng Pilipinas (BSP) dampened market appetite.
GS yields, which move opposite to prices, went up 7.82 basis points (bps) on average week on week, based on PHP Bloomberg Valuation Service Reference Rates data as of Oct. 16 published on the Philippine Dealing System’s website.
At the short end of the curve, yields on the 91- and 182-day Treasury bills (T-bills) went down by 8.51 bps (to 5.6764%) and 2.49 bps (6.0671%) week on week, respectively. Meanwhile, the one-year T-bill rose 11.12 bps to yield 6.3193%.
At the belly, yields were higher week on week across all tenors. Rates of the two-, three-, four-, five-, and seven-year Treasury bonds (T-bonds) rose by 8.75 bps (to 7.0607%), 7.64 bps (7.3261%), 5.57 bps (7.5231%), 4.9 bps (7.6738%), and 7.37 bps (7.8872%).
Rates at the long end also surged week on week. Yields on the 10-, 20- and 25-year notes climbed by 14.47 bps (to 8.0184%), 18.8 bps (8.3856%), and 18.45 bps (8.3848%), respectively.
GS volume traded reached P19.94 billion, lower than the P27.98 billion recorded the week prior.
“Philippine GS yields remained under upward pressure during the week, particularly in the short- to intermediate-tenor segment, as continued peso weakness and elevated oil prices reinforced expectations of further BSP tightening,” a bond trader said. “Investors also remained cautious about extending duration.”
“The market is increasingly pricing in another 25-bp hike, potentially as early as the October meeting, bringing the policy rate to 5.25%.”
On Thursday, the peso slid to the P63 level against the US dollar for the first time in history, closing at a new all-time low of P63.06. It also posted a fresh record intraday trough of P63.23 on Friday.
Meanwhile, the BSP is widely expected to deliver a fourth straight hike this week amid heightened inflation pressures, with further upside risks to prices threatening to de-anchor expectations, analysts said.
A BusinessWorld poll conducted last week showed 20 of 22 economists expect the Monetary Board to raise the target reverse repurchase rate by 25 bps for a fourth consecutive meeting to 5.25% at its meeting on Thursday.
This would match the benchmark rate set in June 2025 and will be the highest in one-and-a-half years or since 5.5% in April 2025.
The BSP has already hiked key borrowing costs by a total of 75 bps since April.
Philippine headline inflation accelerated to a three-and-a-half year high of 7.2% in September after the prices of fuel, food, housing and utilities surged.
This was faster than the 6.1% in August and 1.7% in September 2025 and matched this year’s peak first recorded in April.
September also marked the seventh consecutive month that inflation exceeded the central bank’s 3% target. This brought the year-to-date average to 5.4%.
“The Philippine bond market is not entirely decoupled from the US, but domestic factors are increasingly driving local yields. While US Treasuries have recently benefited from weaker US employment data and reduced expectations of an immediate Federal Reserve hike, Philippine bonds remain pressured by inflation and peso weakness,” the bond trader said.
Jonathan L. Ravelas, a senior adviser at Reyes Tacandong & Co., said that higher inflation in both the Philippines and the US is pushing up GS yields.
US consumer prices accelerated in September as the cost of gasoline surged, Reuters reported. The consumer price index (CPI) report from the Labor Department on Wednesday showed a broadening of price pressures beyond energy, raising concerns among economists that underlying inflation could be getting sticky.
The CPI rose 0.6% last month after climbing 0.4% in August, the Labor Department’s Bureau of Labor Statistics said, in line with economists’ expectations. In the 12 months through September, the CPI advanced 3.7% after rising 3.4% in August.
Excluding the volatile food and energy components, the CPI rose 0.3% in September, matching the gain in August. Economists polled by Reuters had forecast the so-called core CPI would increase 0.2%.
Financial markets now see the Federal Reserve’s interest rate decision at its Oct. 27-28 meeting as a closer call than before the data was released.
The Fed in September raised its overnight benchmark interest rate by 25 bps to the 3.75%-4% range, its first hike in three years, and flagged further increases in borrowing costs in the months ahead.
For this week, Mr. Ravelas said GS yields may continue to move sideways to higher.
The bond trader said the market will focus on the BSP’s policy decision this week and its inflation outlook.
“The upcoming FOMC (Federal Open Market Committee) decision will still influence global yields and dollar movements,” the trader added. — Pierce Oel A. Montalvo with Reuters