Agentic commerce is forcing digital merchants to assess whether their technology infrastructure is suited to the coming era of shopping agents powered by artificial intelligence, a Fiserv executive said Tuesday.
Payments involving AI agents introduce new variables into legacy systems that sellers are now considering, Adit Gadgil, Fiserv’s head of global e-commerce and technology for merchant services, said in an interview at a financial technology conference.
“People are trying to fundamentally evaluate: will their legacy payment stack or commerce stack be fit for purpose, or do they need to build a separate, standalone payment stack to solve the needs of the future, which includes stablecoins, which includes agentic traffic?” Gadgil said.
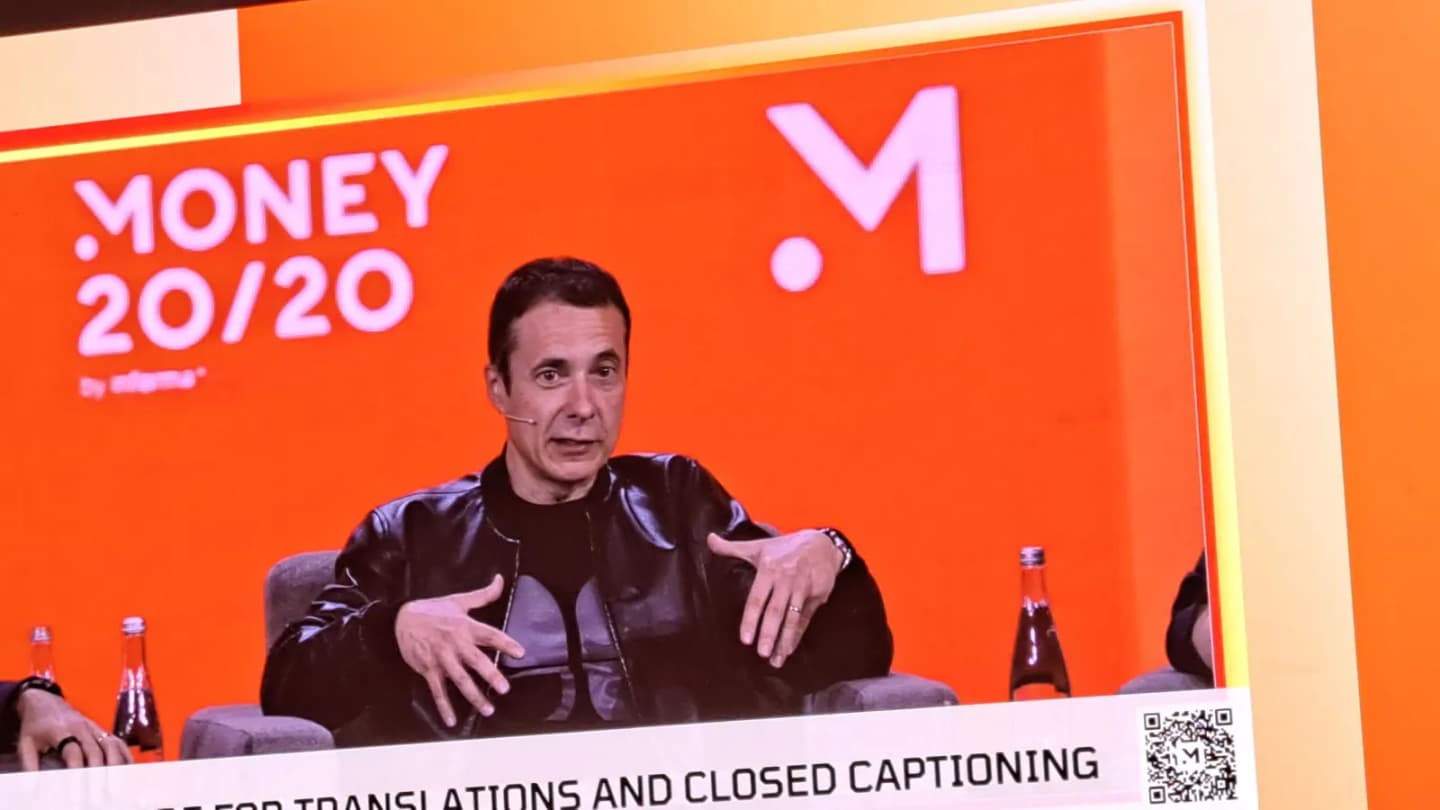
He spoke a day after Fiserv CEO Tsakis Georgakopoulos told an audience Monday at the conference that AI represents “a general-purpose technology because it impacts every part of the value chain and every industry and every business.”
“It is pretty unique compared to everything else we've seen, at least in our lives,” the CEO added during a Monday panel discussion at the Money20/20 financial technology conference with Rodrigo Kede Lima, president of Microsoft Frontier, the software giant’s AI transformation business. “That creates both problems and opportunities for every industry and every customer segment.”
Earlier this year, Milwaukee-based Fiserv announced “a strategic collaboration” with Microsoft to embed AI solutions into Fiserv’s platforms. Fiserv also uses Microsoft’s AI tools for productivity gains among employees.
Consumers have taken to AI chat tools for product discovery, Georgakopoulos noted, “but the complexity is the last mile.”
“Discovery is great,” he said. “How do you actually click that last button, the checkout button, and will that ever become agentic?”
Gadgil said that, as part of the transition to agentic commerce, merchants will also need to accommodate new “machine readable” digital markets where agents will interact with each other – a change that could render some parts of current systems irrelevant.
“Whether we'll be in this situation, where the (online) surface matters so much, is debatable,” Gadgil said. “That doesn't mean it’s going to disappear, but maybe a percentage of it is going to become irrelevant.”
He added that these new “surfaces” will become “a marketplace for agents to work with each other. If you do not have your market agents showing up at these marketplaces, you may not have the opportunity to do business,” Gadgil said.
Agentic payments may drive between $3 trillion and $5 trillion in global consumer commerce by 2030, according to the consulting firm McKinsey.
In terms of current technology addressing agentic traffic, online sellers haven’t yet experienced a fundamental change in how their businesses operate because most agentic commerce still involves humans permitting transactions after the agent finds products.
“My opinion on this is that agentic today is essentially another channel,” Gadgil said. “From a payment stack perspective, as long as there's a human in the loop on the authorization, actually you don't really need to change that much” after ensuring where the traffic is from and that no fraud is involved.
Larger changes lie farther in the future, when agents begin transacting autonomously, under rules specified by humans.
This shift will involve adding extra steps within the payments flow, to generate at least two receipts to verify an agent’s actions, he said. The first will be at the intent layer, to prove someone authorized the agent to undertake a specific transaction, with the second detailing all the information about the payment.
Fiserv is working to ensure its merchant clients understand these different aspects of verifying consumer intent and the payment level within agentic commerce, Gadgil said.
“They should be careful with the risk they're taking, and it's not just on the merchant side,” he said, noting that issuers, acquirers and card networks will also require detailed data about agentic transactions.
“Whether it’s the network or the issuer, they’re all going to be asking these questions, asking for more information, because at the end of the day, no one wants to be sitting there with the liability that comes with it,” Gadgil said.