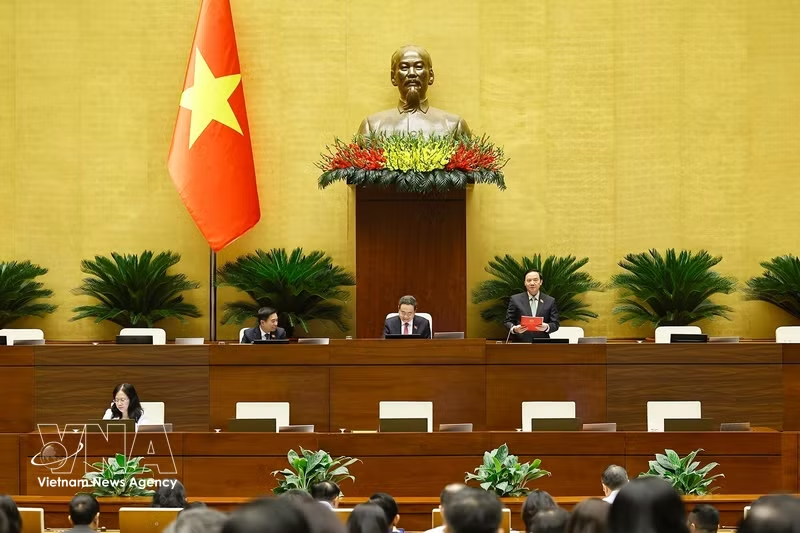
Hanoi (VNA) - Deputies to the 16th National Assembly heard presentations and verification reports on four draft laws concerning issues in finance, budget and investment October 23 morning as part of the second sitting.
The bills included the consolidated Law on the State Budget; the revised Law on Bidding; a law amending and supplementing a number of articles of the Law on Investment; and a law amending and supplementing a number of articles of the Law on Corporate Income Tax, the Law on Non-Agricultural Land Use Tax and the Law on Personal Income Tax.
Presenting the Government’s submission on the draft consolidated Law on the State Budget, Finance Minister Ngo Van Tuan said the draft law is based on the structure and layout of the 2025 Law on the State Budget.
The draft comprises 10 chapters and 103 articles.
The amendments and improvements include provisions on the application of laws to the management and use of state-invested capital in enterprises, the use of local budget deficits for investment, the use of budget reserves for projects outside approved lists, and five-year public investment expenditure ceilings.
The draft integrates annual public investment plans into annual public investment expenditure estimates.
New provisions include definitions of five-year financial plans, public investment tasks and investment preparation tasks, as well as requirements for evaluating public investment effectiveness. The draft also adds responsibilities and powers for the Government in preparing and submitting to the National Assembly Standing Committee a resolution on procedures for reviewing and deciding on the national five-year financial plan, the state budget estimate, the central budget allocation plan and approval of annual state budget settlements.
Phan Van Mai, Chairman of the National Assembly’s Committee on Economic and Financial Affairs, said most committee members supported incorporating into the law the criteria, sequence and procedures for matters falling under the National Assembly’s authority.
The committee called for a comprehensive review of matters assigned to the Government for detailed regulation.
Meanwhile, the draft revised Law on Bidding comprises eight chapters and 59 articles. It amends and supplements numerous provisions to ensure the feasibility, coherence and consistency of the legal framework on bidding; improve the quality and efficiency of bidding activities; simplify procedures and shorten project implementation time; and strengthen decentralisation and delegation of authority in the selection of contractors and investors.
Specifically, the draft adds provisions on policies and fundamental principles governing bidding.
The draft simplifies or removes unnecessary intermediate provisions and procedures. It also streamlines contractor selection methods and improves regulations on prohibited acts in contractor and investor selection.
While agreeing on the need to revise the Law on Bidding, the Committee for Economic and Financial Affairs called for a consistent approach of “caution and certainty, doing each step well… and not pursuing quantity”, alongside substantive assessments of the impacts, costs, benefits and risks of major policies.
At the morning sitting on October 23, the National Assembly also heard the submission and verification report on the draft law amending and supplementing a number of articles of the Law on Investment.
The draft improves provisions on sectors and business lines and market access conditions for foreign investors. It also revises investment incentives and support policies. Provisions on special mechanisms to attract local investment are also added.
The draft introduces four new forms of investment support. Provisions on special investment incentives and support are also amended and supplemented in four areas: eligible beneficiaries; principles for applying special incentives and support; special investment support policies; and a mechanism allowing the Government to decide on exceptional incentive and support packages within its authority, linked to the fulfilment of criteria, conditions and commitments.
The draft also improves investment procedures to further enhance the business and investment environment and strengthens provisions on the effectiveness of state management of the foreign-invested economy.
According to the NA Committee on Economic and Financial Affairs’ verification report, while broadly supporting expanded market access in line with the policy of developing the foreign-invested economy, it held that careful consideration is needed before authorising the Government to “consider and decide on the relaxation of market access conditions” stipulated in laws and resolutions of the National Assembly, ordinances and resolutions of the National Assembly Standing Committee, and international treaties to which Vietnam is a party.
It added that any relaxation of market access conditions should follow an appropriate roadmap and be based on a comprehensive impact assessment.
The draft law amending and supplementing a number of articles of the Law on Corporate Income Tax, the Law on Non-Agricultural Land Use Tax and the Law on Personal Income Tax focuses on institutionalising the Party’s guidelines on corporate income tax and non-agricultural land use tax incentives for domestic educational institutions.
The draft amends Clause 5, Article 15 of the Law on Corporate Income Tax. It stipulates that public science and technology organisations, public educational institutions and non-profit private educational institutions are exempt from tax in accordance with Government regulations. The identification of public educational institutions and non-profit private educational institutions is to comply with laws on education, vocational education and higher education.
The draft also adds provisions on exemptions from corporate income tax and personal income tax for income earned by businesses and individuals from providing meals to educational and medical examination and treatment establishments; exemptions from non-agricultural land use tax for educational institutions; and exemptions from non-agricultural land use tax for ethnic minority people.
Notably, the draft introduces a tax rate for abandoned land, land that has not been put into use and land whose use has been delayed. It stipulates that such land would be subject to a tax rate of 0.2%, with no quota applied. The classification of abandoned land, land not put into use and land whose use has been delayed would be governed by land legislation.
The NA Committee on Economic and Financial Affairs broadly supported the Government’s proposal to add a tax rate for abandoned land, land not put into use and land whose use has been delayed. However, it said that when compared with the current Law on Non-Agricultural Land Use Tax and the draft revised Land Law, the proposed provisions remained inconsistent and lacked a clear legal basis for implementation.
Specifically, the current law already imposes a 0.15% tax rate on unused land in accordance with regulations, which in essence covers land not put into use or whose use has been delayed. The Government’s proposal could therefore lead to the same plot of land being subject to two different tax rates.
The committee also noted that the same project land that remains unused or is put into use late could be subject both to increased land-use fees or land rental payments under the draft revised Land Law and to non-agricultural land use tax at a rate of 0.2% under the draft law, resulting in overlapping financial obligations for the same act.
The committee therefore called on the drafting agency to clarify the relationship between the proposed 0.2% tax rate and payments required under land legislation, ensuring that financial obligations are not duplicated while not reducing the obligations of cases currently subject to the 0.15% tax rate. It also urged an assessment of the impacts on the state budget, taxpayers and implementation capacity./.