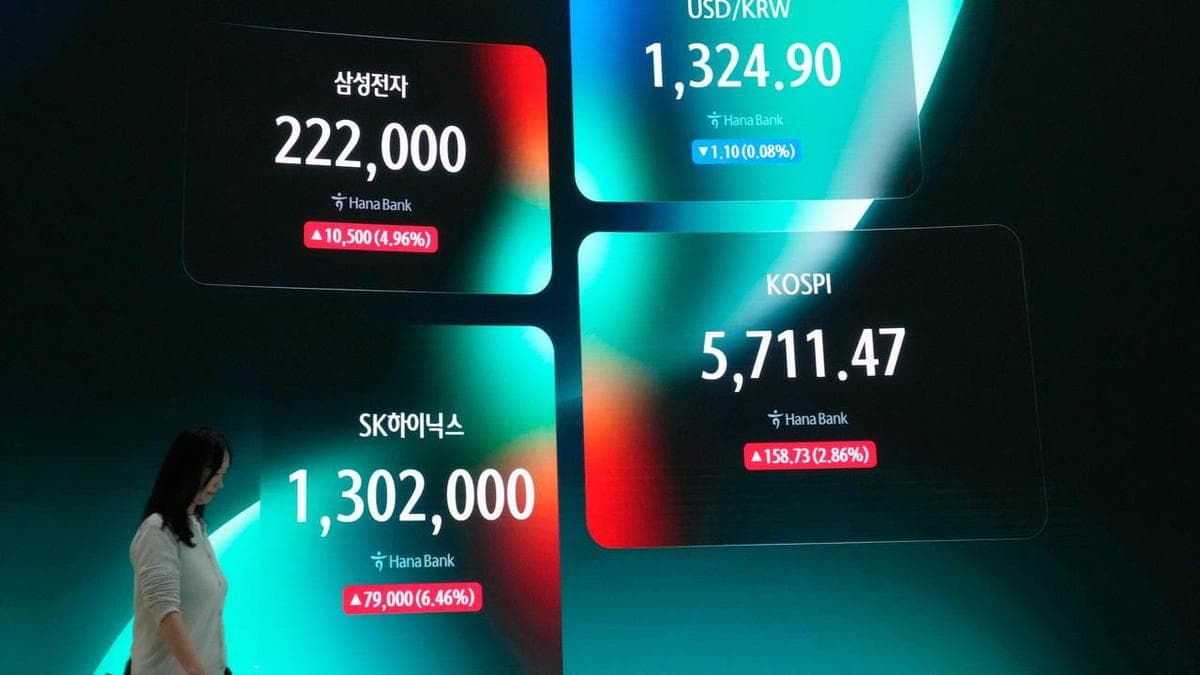
Global stocks have nudged up as early signs from the earnings season point to strong profits for global firms and shored up sentiment in the face of nagging worry about the strength of the AI trade and turbulence in government bonds.
World markets have had a rocky ride in October as a sharp sell-off in AI-related shares has soured sentiment towards the tech sector, while France's bond market has come under pressure as violent protests add to its political woes.
European markets were broadly higher in early trade on Wednesday, while US stock futures pointed to a positive open for Wall Street shares ahead of earnings reports from the likes of Meta and Tesla.
With 13 per cent of S&P 500 companies reporting, 86 per cent have beaten earnings estimates, according to LSEG data.
"What we've seen over 2026 so far is effectively that markets have positively responded to strong earnings," said Neil Fisher, an investment specialist at St James's Place in London.
"Where they have not always responded positively to stronger earnings, especially on the AI side of things, is when further capex (capital expenditure) and further spending on AI gets put on the table."
In Asia, MSCI's broadest index of Asia-Pacific shares outside Japan rallied about one per cent, led by a more than three per cent gain in Korea, while Japan's Nikkei 225 rose almost one per cent.
Australian data centre operator NextDC shed nearly half of its market capitalisation on Wednesday after sharply cutting revenue forecasts for the year ahead and putting future developments on hold, extending the burst of negative sentiment towards global AI stocks.
In contrast, shares in South Korean artificial intelligence infrastructure company Elice Group surged almost 30 per cent, rebounding from a slump in its market debut on Tuesday.
Shares in companies in Japan and Taiwan that are suppliers to Tesla and SpaceX advanced after Elon Musk said on Tuesday that a merger of the two companies would be "a good idea" and that they had formed special committees to discuss a union.
France, at the heart of recent turmoil in European bond markets, remains in the spotlight.
Its bond yields rose again as investors took stock of the widespread protests across France that are putting pressure on a government that was already struggling to shore up its finances.
French 10-year bond yields have risen more than 16 basis points this week to just shy of the five per cent mark.
That is by far the most among the bonds of the world's largest economies, which have risen by an average of just more than 5 bps, according to LSEG data.
A rebound in the oil price back above $US110 a barrel, after a short-lived drop the previous day, added to the negative sentiment across bond markets with US Treasury yields also rising in London trade.
In currency markets, the dollar index, which measures the currency against six peers, was steady at 101.79, while the French jitters kept the euro on the defensive. The single currency was down about 0.2 per cent at $US1.122.
The yen was flat against the dollar at 158.15 after government data released on Wednesday showed Japan's exports in September rose 16.7 per cent from a year earlier, missing estimates.
Strong demand for semiconductors and AI-related products offset weakness in other sectors.
Elsewhere, data showed UK inflation rose by 3.5 per cent, Britain's government borrowed more than expected again in September and public debt surpassed Stg3 trillion ($USA5.7 trillion), underscoring finance minister John Healey's challenge in his first budget next week.