Productivity doesn’t just depend on our tax competitiveness and how much capital investment we have. It also depends on that investment going to the most profitable uses possible.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
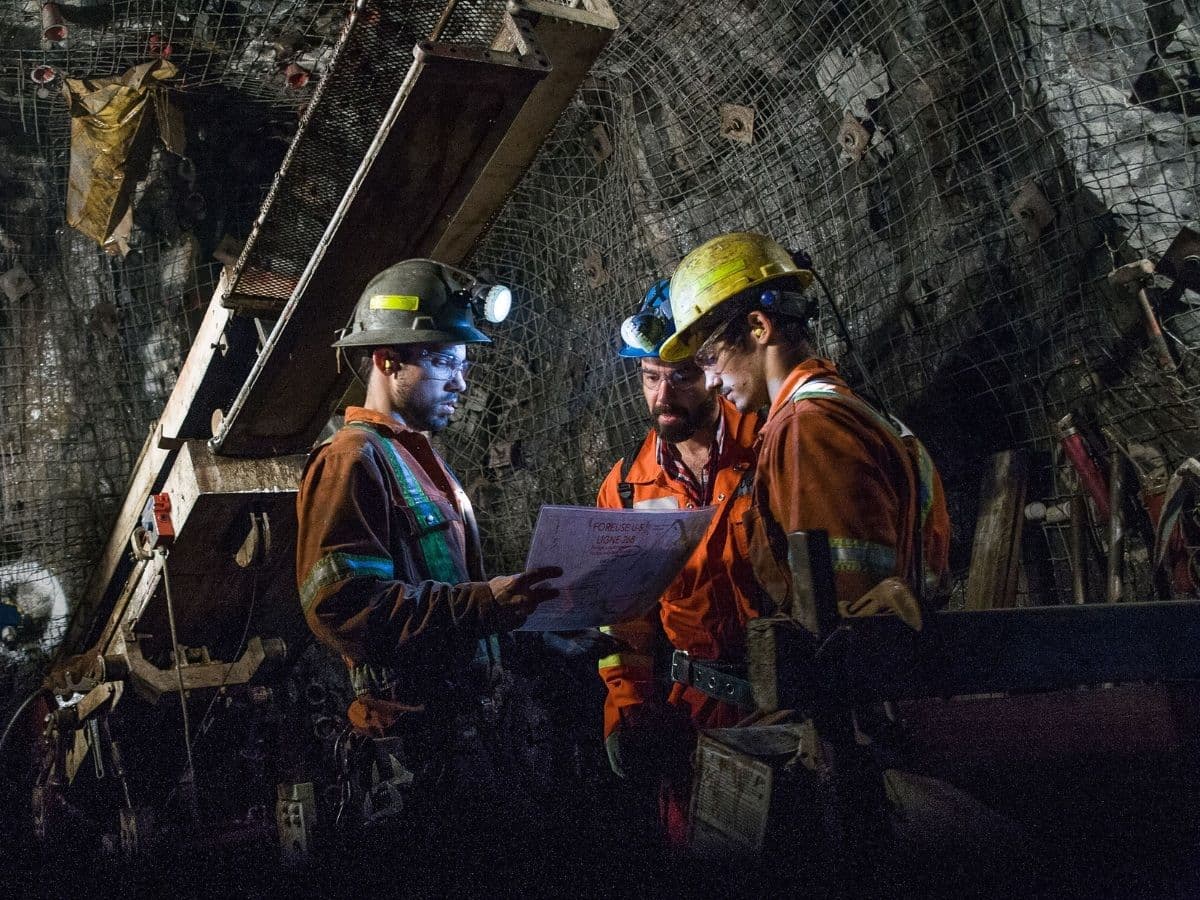
Canada’s mining tax system certainly supports capital investment, and it’s also internationally competitive. But it fails the productivity test by supporting sub-optimal projects that would not be carried out if business decisions were based solely on economic criteria. In sum, our mining tax system is distortionary, inefficient, overly complex and needs to be overhauled.
This is the conclusion Philip Bazel and I reach in our new review of provincial mining taxes, just published by the School of Public Policy, University of Calgary. Mining investment in Canada disappointed over the last decade but that was due to regulation, not taxation. As of 2024, it took 20 years from discovery of a mineral deposit to start up production. In Australia, with its better regulatory system, the lag was only 14 years. The Carney government is on the right track in trying to reduce regulatory delay — although legislative reform would be better than the government picking and fast-tracking winners.
Get the latest headlines, breaking news and columns.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Top Stories will soon be in your inbox.
We encountered an issue signing you up. Please try again
On the other hand, federal and provincial governments are going overboard on unneeded tax preferences and subsidies to spur mining investment. Our new paper measures effective tax rates on new mining investment by province for the most abundant products, both critical (copper, lithium, nickel and zinc) and non-critical (iron ore and gold).
Overall, we conclude that Canada’s mining tax structure is already internationally competitive, with effective tax rates on new investment well below those in most major mining producers, including Australia, Chile, China, Peru and the United States. Several tax preferences account for our competitiveness: the ability to deduct exploration and development charges from a company’s profits before a new mine earns income; fast write-offs for exploration, development and processing costs; and investment tax credits for exploration.
For example, the effective tax rate for iron-ore investments is 9.4 per cent in Ontario, far less than in the three largest producing countries: in Western Australia it’s 21.5 per cent, in Brazil 17.1 per cent and in China 16.1 per cent. The same story holds for copper. B.C.’s effective tax rate is 7.6 per cent, compared to 26.7 per cent in Chile, 21.4 per cent in New South Wales, Australia, and 19.8 per cent in Peru.
Effective tax rates vary a lot by province. Averaged across provinces, the effective tax rate is 10.2 per cent for critical minerals,13.3 per cent for non-critical. Quebec taxes mining projects most heavily — at 19.2 per cent for critical minerals and 14.6 per cent for non-critical — primarily because of a progressive mining profit tax that tops out at 28 per cent. Ontario has the lowest effective tax rate at 7.1 per cent for critical and 9.9 per cent for non-critical minerals, in part due to low tax rates on mining profits and concessionary corporate taxation.
Although Canada’s current system of mining taxation is competitive, it’s poorly designed, heavily favouring development and exploration, especially in critical minerals. Exploration is effectively subsidized by expensing — i.e., immediate write-offs — and investment tax credits both federally and in B.C., Saskatchewan, Manitoba and Quebec. Many companies end up no longer paying taxes, which blunts the effectiveness of incentives.
The critical-mineral incentive for exploration costs is a perfect example of governments going overboard with complex, inefficient incentives. When new deposits are discovered, they can be a mix of critical and non-critical ores. If the majority are critical, the tax credit can be claimed. But if it turns out later that most of the deposit is in fact non-critical minerals, the credit is lost.
Also, unlike the general-exploration tax credit, the critical-mineral credit flows through to investors, who claim it instead. The tax benefits can be so substantial that investors pay less attention to the quality of investments. Vijay Jog of Carleton University has shown that, in the absence of tax benefits, flow-through shares earn only marginal economic returns, with many money-losing projects being funded.
Finally, though mining is a non-renewable resource — what is sold off today is not available for future generations — the federal government not only provides excessive tax support but also throws subsidies at mining projects through the First and Last Mile Fund ($1.5 billion) and the Critical Minerals Mining Fund ($2 billion). The Canada Infrastructure Fund and Export Development Fund add low-cost credit to the mix, as well. A government whose watchword in other areas is sustainability and conservation is pushing hard for the rapid exploitation of a valuable part of our non-renewable mineral store.
A much better approach would be to curb incentives, eliminate the distortionary critical-mineral incentive and convert current provincial mining profit taxes into B.C.-like rent taxes, with capital expensing and a carry-forward of unused deductions at an interest rate. Our mining taxes would remain internationally competitive, but would be far simpler and less distortionary.
We also need to remember that tax incentives, subsidies and low-cost credit come with a price tag, typically involving bigger deficits and higher future taxes. Over-extraction of marginal non-renewable mineral resources today, combined with more tax being moved to future years, means that, once again, younger Canadians pay.
This article is based on Philip Bazel and Jack Mintz: “Canada’s Mining Tax System Needs to be Efficient and Simple,” published by the School of Public Policy, University of Calgary.

Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.