Nigeria’s economic recovery has yet to deliver shared prosperity because stabilising the currency market and slowing inflation do not automatically reverse past price increases, reduce businesses’ production costs or create enough productive jobs. The missing link is the transmission of macroeconomic gains into business expansion, rising real incomes and improved living standards.
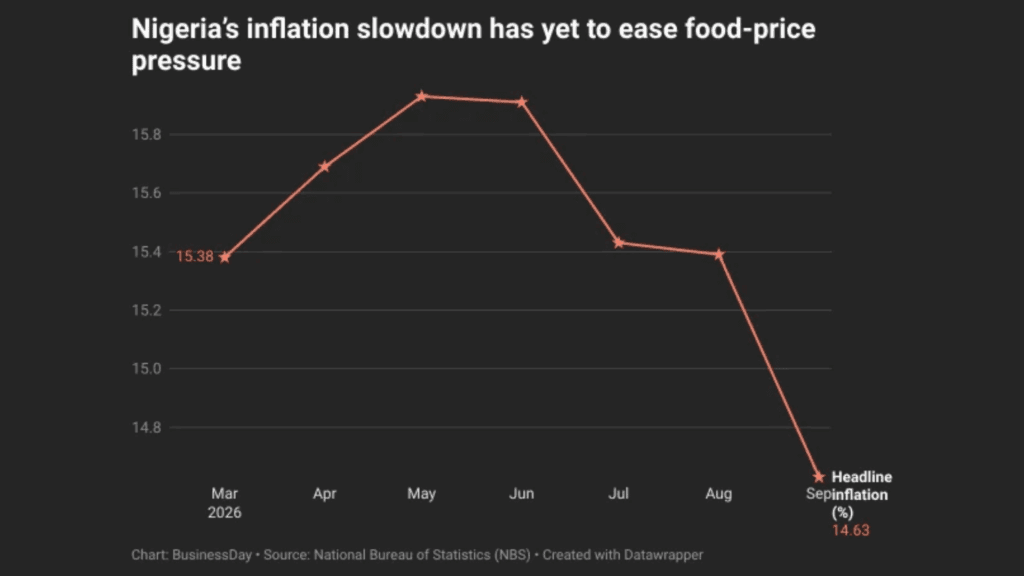
Although headline inflation fell to 14.63 percent in September 2026 and external reserves reached about $55 billion, food inflation remained elevated. Prices may be rising more slowly, but that does not mean households are paying less for food or have recovered the purchasing power lost during the inflation surge. The challenge is to turn improving economic indicators into tangible gains for Nigerians.
That was the central tension in Taiwo Oyedele, Nigeria’s finance minister, presentation at Chatham House in London on October 21, where he discussed Nigeria’s reform journey and prospects for inclusive growth. His message was that macroeconomic stability should lay the foundation for investment, job creation and rising incomes, rather than become the final measure of economic success.
Read also: 2027: Tinubu blames opposition for hunger, poverty, promises prosperity, economic recovery
Lower inflation does not mean lower prices
Nigeria’s headline inflation fell to 14.63 percent in September 2026 from 15.39 percent in August and 20.98 percent a year earlier, according to the National Bureau of Statistics. This is meaningful progress in slowing the pace of price increases. But inflation measures how quickly prices rise, not whether they have returned to previous levels.
Households are still paying prices shaped by the inflation surge of earlier years. Unless incomes catch up, slower inflation may ease the rate at which purchasing power deteriorates without restoring what families have already lost.
Food illustrates the difficulty. Annual food inflation stood at 19.59 percent in September, even though the monthly food index fell by 1.55 percent, according to figures reported by Voice of Nigeria. The monthly decline offers some relief, but it does not establish that food has become affordable for households whose earnings have struggled to keep pace with rising costs.
This distinction matters for the reform debate. An economy can show improving inflation figures while households continue to cut spending, substitute cheaper products or postpone essential purchases. The rate of price increases may be falling, but the burden of the accumulated price shock remains.
Why investment may not be enough
Oyedele’s emphasis on attracting capital points to the next stage of reform. Investors need credible policies, predictable regulation and confidence that they can earn returns without arbitrary changes to the rules. Stronger external reserves and greater exchange-rate stability can support that confidence by reducing some of the uncertainty surrounding business decisions.
But investment does not automatically produce inclusive growth. Its benefits depend on where capital goes and whether businesses can convert it into higher output, productivity and employment.
Read also: Cardoso highlights Nigeria’s reform gains as IMF leaders debate global economic resilience
Nigerian firms continue to face structural constraints, including unreliable electricity, transport bottlenecks and expensive financing. These pressures can raise the cost of production, weaken competitiveness and limit businesses’ capacity to expand. Even when investor confidence improves, the effect on jobs and household incomes may be modest if firms cannot produce more efficiently or access the finance and infrastructure needed to grow.
The quality of investment therefore matters as much as its volume. Capital that expands manufacturing, modernises agriculture and helps businesses scale can create stronger domestic linkages than investment that generates limited employment or depends heavily on imported inputs. The objective should not simply be to attract money, but to direct it towards activities that raise productivity and create sustainable jobs.
Growth must translate into earnings
The International Monetary Fund’s October 2026 outlook, as reported by BusinessDay, projected Nigeria’s economy to grow by 4.2 percent in 2026 and 4.3 percent in 2027. Continued expansion would support the recovery, but GDP growth alone cannot show whether the benefits are reaching households.
The composition of growth matters. If output expands without sufficient growth in productive employment, many Nigerians may see little improvement in their earnings. If wages rise more slowly than the cost of living, workers can become poorer in real terms even as the economy grows.
This is why the next phase of reform requires a broader measure of success. Inflation, reserves and GDP growth remain important, but they should be assessed alongside real wages, employment, poverty, food affordability and access to essential services. These indicators would help establish whether macroeconomic progress is improving living standards rather than merely strengthening the headline numbers.
The government also needs to protect vulnerable households during the transition. Targeted support can help families absorb the costs of adjustment, but transfers alone cannot substitute for an economy that creates productive jobs and enables earnings to grow sustainably. Durable relief depends on stronger productivity, more competitive businesses and a labour market capable of generating reliable incomes.
Read also: Hidden Economy: How Nigerian clubs nurture players, miss out on transfer fees
Stability is the beginning, not the result
Oyedele’s argument that stability is a foundation rather than a destination captures the central test facing Nigeria. Lower inflation and stronger reserves can create conditions for recovery, but they cannot guarantee that investment will expand production, that growth will generate enough jobs or that household incomes will recover lost purchasing power.
Those outcomes depend on whether the government can remove the constraints holding businesses back, encourage investment in productive sectors and make employment and income growth central measures of reform performance.
Nigeria’s reform case will ultimately be judged not only by the stability it restores, but by what that stability makes possible. Until businesses can expand more competitively, workers can find productive jobs and incomes can buy more of what households need, macroeconomic progress will remain incomplete.
The decisive question is no longer whether Nigeria can improve its economic indicators. It is whether those improvements can reach the people whose living standards reform is supposed to raise.
Related News

Oluwatobi Ojabello, PhD, is a dynamic and multi-dimensional Assistant Editor for Economy and Markets with over two years of professional journalism experience. He delivers authoritative, data-driven coverage of fiscal policy, financial institutions and capital markets, using clear analysis to explain Nigeria’s most complex economic developments. His work focuses on macroeconomic policy, financial stability and corporate performance, turning technical issues into accessible narratives that inform both experts and everyday readers.

