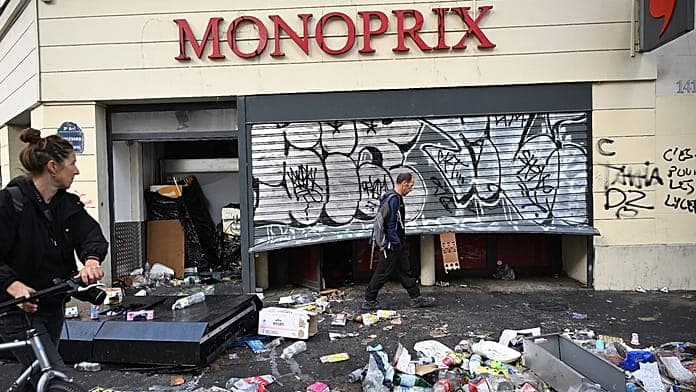
The eurozone’s second-largest economy saw its bond yields rise further on Monday, following violent street demonstrations in the country over the weekend.
France’s 10-year government bond yield hovered around 4.9% on Monday, near its highest level in more than two decades, as investors demanded a higher premium for holding French debt. Protesters are demanding action on the rising cost of living and declining public services, including education.
The unrest adds to pressure on the government as it battles to get its 2027 budget through a deeply divided National Assembly, the lower house of France’s parliament.
The immediate challenge is to pass a credible budget that reassures investors ahead of the presidential election in spring 2027. But restoring confidence will also depend on whether the next administration can commit to improving public finances over several years.
What is fuelling investors’ concerns?
France is nursing one of the highest public debt ratios in the EU, at 119% of GDP, according to the latest reading from INSEE, the national statistics office. This is coupled with a government forecast for a deficit of 5.4% of GDP in 2026. Public debt stood at €3.596 trillion at the end of June 2026.
The cost of servicing that debt has been rising sharply. The government forecasts public debt interest payments of €91 billion in 2027, up from €79.2 billion this year — an increase of almost €12 billion.
Accelerating inflation and low growth threaten to weaken tax revenues and raise the deficit and debt further.
The current fiscal situation therefore leaves little room for the government to meet protesters’ demands through another large spending package, along the lines of French President Emmanuel Macron’s “whatever it costs” approach when the pandemic hit the country.
The government faces pressure to reduce the deficit and commit to lasting savings to calm nerves on the bond market. If borrowing costs keep rising, France’s debt could become increasingly difficult to control.
And a spiralling crisis could also hit other major eurozone economies, such as Italy.
How France’s debt troubles could hit Italy
Modelling the impact of bond turmoil in France, with some contagion to other high-debt eurozone countries, Oxford Economics found that Italy would be particularly vulnerable because it combines slow growth, high debt and investment that is sensitive to tighter financial conditions.
A key yardstick for measuring market concerns is the gap between a country’s 10-year government bond yield and Germany’s equivalent. The current spread — the extra return investors want to hold French debt instead of German debt — has risen to around 145 basis points (bps). This is still slightly below the peak reached earlier this month, which was the highest since the eurozone debt crisis of 2011–2012.
Oxford Economics sets out a baseline and two adverse scenarios. Its baseline assumes that France’s spread stays below 200bps ahead of the April 2027 presidential election and narrows afterwards. It continues to view a French debt crisis as an unlikely but potentially damaging outcome, rather than its central forecast.
The two adverse scenarios combine higher borrowing costs with a hit to business and consumer confidence. In the moderate scenario, the French spread widens to 250bps from around 140bps when the report was published on 15 October. In the severe scenario, it reaches 400bps.
France and Italy would enter recession in 2027 under the severe scenario. Belgium would also see a jump in its borrowing costs, while Spain, Portugal and Greece would face higher bond yields but less economic damage, with none of the three economies contracting.
Crucially, the eurozone as a whole would avoid recession even under this severe scenario.
According to Andrew Kenningham, chief Europe economist at Capital Economics, a widening of France’s spread to 400bps is a “plausible adverse scenario, (…) which would be comparable to Italy’s spreads in 2012”.
Kenningham agreed that, in that case, there would certainly be a lot of pressure on other high-debt economies, including Italy.
“However, in contrast to the early 2010s, the ECB would be well placed to support countries other than France through its Transmission Protection Instrument,” he said.
With this instrument, the ECB can buy government bonds to help keep borrowing costs under control if the country meets certain conditions.
Kenningham also said that the risks to the banking sector and the risk of a property crash are much lower than in the 2010s.
“So things could get very bad but not as bad as in the 2010s.”
According to Oxford Economics, in its severe scenario, France’s 10-year bond yield would reach 7% in the second quarter of 2027, with the public deficit on track to surpass 6% of GDP. The consultancy warns that yields at such levels could trigger a liquidity crisis.
But expectations of ECB intervention to help France remain low. ECB President Christine Lagarde said last week that the means to stop the surge in French borrowing costs “must first be found in France”, through budget measures to reassure investors.
What France can do to regain investors’ confidence
According to Oxford Economics, the measures needed to calm markets could include gradual spending restraint over several years, accompanied by clear legislative commitments, especially on the retirement age.
But the consultancy warns that “the current minority government will not be able to credibly commit to sustained fiscal consolidation to soothe markets”. Much of the responsibility for carrying out any painful measures could therefore fall to the next administration.
In the meantime, Kenningham said investors are expecting the government to pass a budget that reduces next year’s deficit to around 5% of GDP, “so anything less than that could lead to further loss of confidence in the French bond market”.
Ahead of next spring’s presidential election, far-right leader Marine Le Pen is leading in the polls. In an interview with the Financial Times last week, she promised: “massive reductions in public spending, while reviving the economy”.
She presented her “counter-budget” on 6 October, targeting €140 billion in net savings by 2032 compared with 2026, a deficit below 3% of GDP by 2030 and a constitutional budget rule. Her party proposes cutting administrative and social security spending, immigration-related expenditure and France’s EU contribution.
But economists questioned the figures. Mathieu Plane, deputy director of analysis and forecasting at the French Economic Observatory (OFCE), told Le Monde that more than €80 billion of the proposed savings were questionable, poorly defined and difficult to implement.
In the meantime, France is facing the risk of a vicious circle in which higher borrowing costs force further spending cuts or tax rises, weakening growth and making its debt harder to control.
“France has been heading towards a debt crisis for many years and that moment is now getting closer,” Kenningham concluded.