
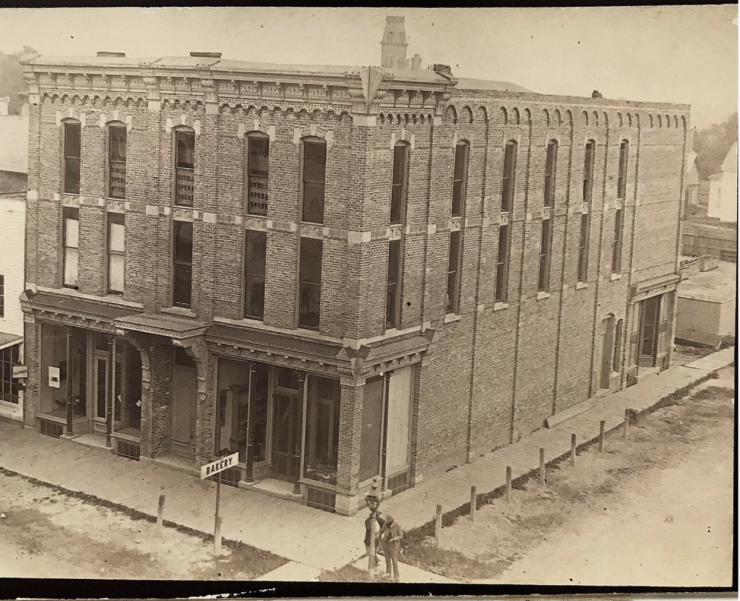
The Howell Opera House, a modest, three-story brick Victorian, was built in 1881 on the corner of Grand River Avenue and South Walnut Street in Howell, Michigan, a city of about 10,000 people outside Detroit. The opera house was a popular place but since 1924 the actual theater has been closed to the public. The ground floor was turned into retail space, its upper floors used for storage.
Processing Content
For several years now a local arts council has been raising funds to restore the building and reopen the theater and its horseshoe balcony, which comprise the second and third floors. The council received $2 million from the state for the restoration project, which is expected to cost up to $8 million or more (because, you know, inflation.) The first floor has been turned into an event space, which brings in some revenue I'm sure, but they obviously need millions more.
As part of that effort, Lake Trust Credit Union is donating an initial $250,000 through its nonprofit arm, Lake Trust Foundation. The bank said supporting the opera house dovetails with its own goal of supporting its local communities. Certainly there is a bottom-line calculus to Lake Trust's donation. It generates goodwill, it gets the bank's name out there. But even a cynical New York editor can see that there's more than just that involved.
Why do I bring this up? For one thing, I just think it's a cool project. Especially in an age of people being terminally online, having spaces such as the opera house for live events is going to be ever-more important. But I really bring it up because I think it highlights something bankers should always keep in mind.
Being involved in your community is just good business. We've written recently about the state of physical branches. While there's been some actual expansion recently, the overall trend is still down. S&P Global Market Intelligence reported total bank branches contracted by 0.2% over the past 12 months, and that is the smallest contraction since at least 2017.
What is the point of a bank? Is it about the money or the people it serves? Obviously it's both to varying degrees. But the relationship between a bank and its customers really is unlike the relationship between customers and any other business. When I buy an Apple laptop, I am engaging in a single transaction. When I buy clothes, or books, or even a car, those are all one-off transactions. I may never do another deal with those retailers. I'm certainly not obligated to. But when a customer puts their money in a bank, they are by the very nature of that transaction creating a relationship.
A bank that has nothing to do with its community or customers, that shutters its physical branch, is saying something about the value it puts on the people it serves. And, again, I understand there is a bottom-line calculus to closing or opening a bank branch, or to funding local programs. But having a physical presence in a community, supporting Little League teams and restoring historic buildings and funding scholarships, tells the people who are your customers in that town or city that you are one of them, that you are part of what they're building.
And when you add up all the Howells and Howellonians out there (I have no idea if they call themselves that, I just made that up), and all the things they are building in their communities and their lives — all the opera houses, and nail salons, and restaurants, and realtor offices, and vet clinics, dry cleaners and lawn services, and on and on and on, well, that is what the money is for in the first place. The money is a way to help us all distribute resources and use them to build things.
What is the point of a bank if not to support all that?

Managing Editor
Paul Vigna is the managing editor of American Banker. He is an author, journalist, editor and speaker, with a particular focus on capital markets and... Read full bio