South Africa will open its national payments system to non-bank operators, including telecommunications companies, fintechs and retailers, from mid-2027, a Reserve Bank official said on Friday, as part of a broad overhaul of the system.
The change would end the banks’ long dominance of payment processing in South Africa. Non-banks would be able to connect directly to the national payments infrastructure, which clears and settles payments across the country, instead of relying on banks as intermediaries.
The South African Reserve Bank hopes the reform will spur competition, lower costs, broaden access to digital financial services and encourage innovation in a sector increasingly challenged by fintechs and mobile money providers such as MTN.
Pradeep Maharaj, executive director of the Reserve Bank’s Payments Ecosystem Modernisation (PEM) programme, told a media briefing that rules governing payment activities and exemptions would be published by November. Non-bank participants are expected to go live around March 2027 after being licensed, allowing time for testing and systems integration ahead of a mid-year launch.
The framework, set out in the National Payment System Bill released for comment in September, will initially let non-banks carry out seven payment activities on their own, from issuing e-money and acquiring merchants to payment initiation, TechCentral reported from the briefing.
Maharaj insisted the banks are not the target. “Banks are doing a great job, and will continue to do so,” he said. “Our idea is simply to open access and to let entrepreneurs be able to serve sections of the economy that have been underserved by traditional banking.”
Key pillar
The reform is a key pillar of the PEM programme, which aims to reduce reliance on cash and speed up the adoption of affordable digital payments. The Reserve Bank also plans to modernise payment infrastructure, increase the use of fast-payment services such as PayShap and strengthen security and digital identity verification.
PayShap handles about 60 million transactions a month, against a target of 500 million a month by 2029, said Arif Ismail, head of the Reserve Bank’s national payment system department. Maharaj said the banks had built a world-class system but then gave themselves the power to set its rules, implemented it differently and imposed clashing limits.
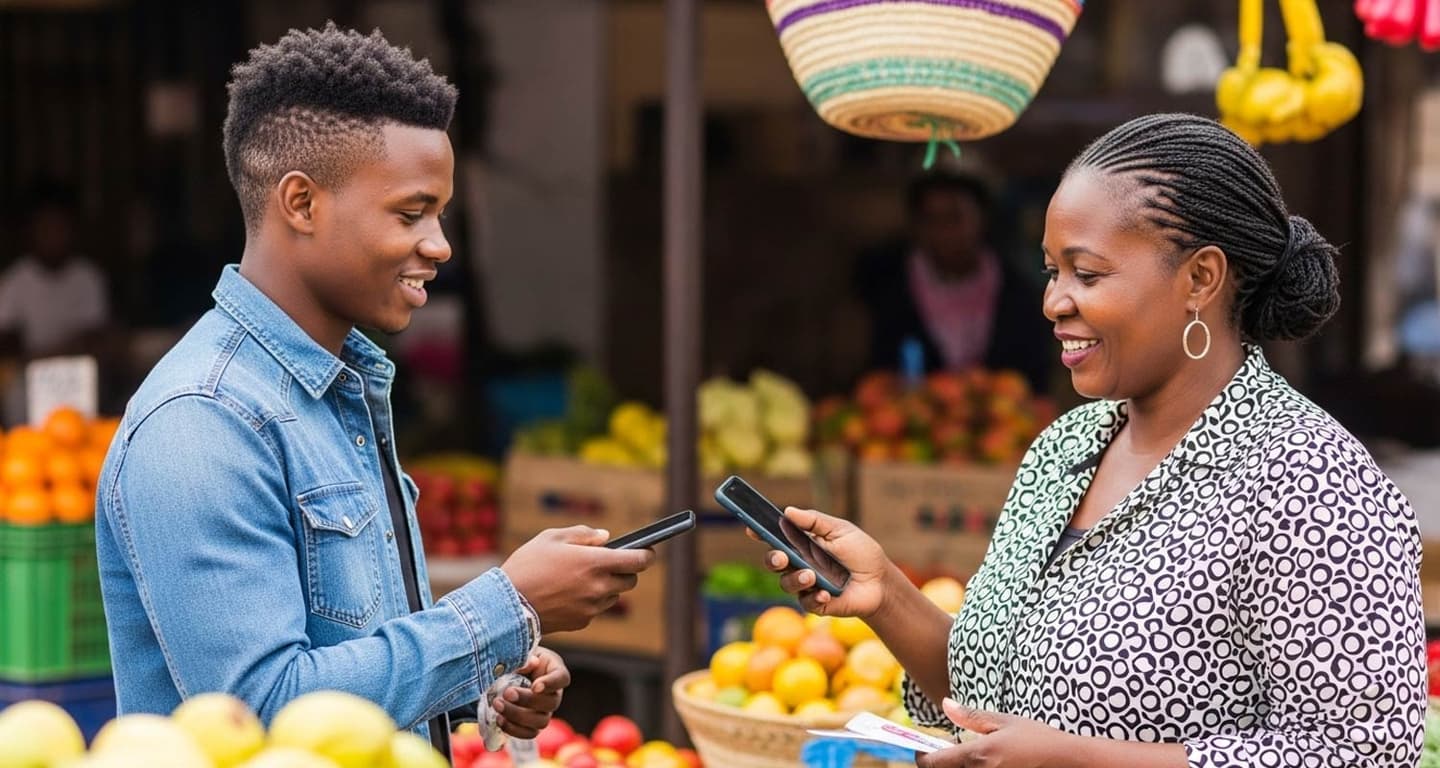
“It is not a uniform experience, that is the problem.” Transactions below a certain level should be free, he said, and a standardised QR+ payment code, due in November, should let even a car guard accept digital payments without fees.
Maharaj said the changes should lower transaction costs for small businesses and consumers and reduce dependence on cash, while giving unbanked and underserved consumers wider access to digital payments.
As part of the wider modernisation effort, the Reserve Bank has also proposed creating a national cash utility, a central bank-owned cash-handling company, and introducing “white-label” ATMs operated as shared infrastructure rather than by individual banks. The aim is to lower cash-handling costs and preserve access to cash, particularly in rural and underserved areas.
“We are asking banks to white-label all ATMs,” Maharaj said. The Reserve Bank wants every ATM to allow deposits, withdrawals and balance enquiries, with transactions below a certain amount free of charge. That would be a big change: about 9 200 of the country’s roughly 30 600 ATMs are run by independent deployers that don’t accept cash deposits, according to the Reserve Bank’s cost of cash study. The banks have proposed alternative models, and the Reserve Bank will respond in November.
A white-label ATM pilot will be launched in January, with the first batch of machines to be rolled out nationwide by the end of 2027, Maharaj said.
The cash utility is due to be established by March 2027. Maharaj said the Reserve Bank expects to migrate its own cash centres into the utility in 2027 and to begin incorporating industry-owned centres, such as those run by SBV and Fidelity, which the utility will buy. Unlike PayInc, the former BankservAfrica, in which the Reserve Bank holds a 50% stake, the cash utility will be wholly owned by the central bank, Maharaj said.
The Reserve Bank isn’t trying to build a cashless society, Maharaj said. “Cash is a public good and core to inclusivity.” Cash still accounts for 56% of consumer transactions by volume, and the cost of cash study puts its annual economic cost at R88.5-billion, about 1.2% of gross domestic product. Maharaj said the cost of cash would have to fall by at least 30% just for the system to stand still. — Nqobile Dludla and Kopano Gumbi, (c) 2026 Reuters, with additional reporting (2) 2026 NewsCentral Media