Business Korea · সাধারণ
Shipping Stocks Rally as KOSPI Plunges 14% on Surging Freight Rates
১৫/১০/২০২৬
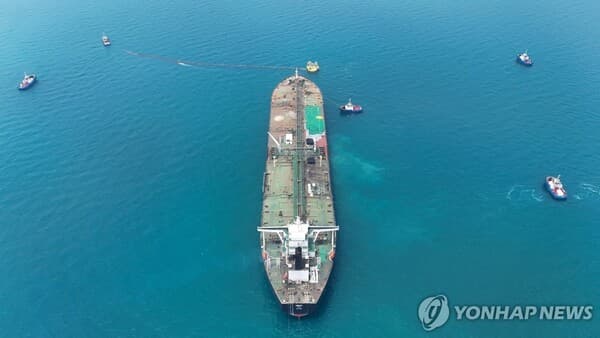
An oil tanker in the Persian Gulf.
As South Korea’s stock market undergoes a sharp correction, shipping stocks are standing out, with the KRX Transportation index the only one among the exchange’s major industry indices to post a gain. Rising maritime freight rates amid escalating geopolitical tensions in the Middle East have drawn buying interest to major shipping companies such as Pan Ocean and HMM.
According to the Korea Exchange on Oct. 14, the KRX Transportation index rose 1.76% over the previous week, making it the only one of the 40 industry indices compiled by the exchange to post a positive return. This sharply contrasts with the KOSPI’s 14.21% plunge and the KOSDAQ’s 7.77% decline over the same period. Pan Ocean surged 16.03% and HMM climbed 8.60%, leading the index higher, while Hyundai Glovis fell 8.39% and Korean Air declined 1.47%.
The main driver of the shipping sector’s strength is the disruption to logistics caused by armed conflict in the Middle East and the resulting rise in freight rates. As clashes between the Saudi-led international coalition and Yemen’s Houthi rebels have intensified, restrictions on passage through the Red Sea and the Strait of Hormuz have prompted vessels to take longer routes. This has increased “ton-miles,” the distance over which ships transport cargo, exacerbating the effective shortage of vessel capacity.
Freight rates for very large crude carriers (VLCCs) have soared to record levels. At the end of September, the average VLCC spot rate reached $700,000 per day, while rates on some routes from the Middle East to East Asia exceeded $1.2 million per day. That was more than 20 times last year’s average of $55,000 per day.
Securities firms are raising their earnings forecasts for shipping companies. HMM’s third-quarter operating profit is estimated to reach 1.0158 trillion won, a 242.2% increase from a year earlier. This would substantially exceed the market consensus of 686.5 billion won. Choi Min-gi, an analyst at Shinhan Investment Corp., upgraded his rating on HMM to “Buy,” attributing the outlook to strong peak-season cargo volumes ahead of changes in U.S.-China tariffs and supply disruptions such as port congestion.
Pan Ocean is also benefiting from its business diversification. Having expanded beyond its traditional focus on bulk carriers into VLCCs and LNG carriers, the company is forecast to post third-quarter revenue of 1.73 trillion won, or approximately $1.28 billion, and operating profit of 194 billion won. VLCCs acquired from SK Shipping are beginning to contribute more substantially to earnings, while a recently signed long-term vessel charter contract worth 148.1 billion won is also expected to improve profitability.
However, analysts caution that the shipping sector’s rally may not last. If military tensions in the Middle East ease, demand for rerouting could decline, potentially sending freight rates lower. The prospect of increased new-vessel deliveries in the container shipping market is also a concern for earnings over the medium to long term.
Nevertheless, the prevailing view is that favorable conditions will persist in the near term. Because freight-rate indices typically precede revenue recognition by about one month, any decline in fourth-quarter earnings is expected to be limited. The anticipated introduction of environmental regulations by the International Maritime Organization (IMO), along with other factors that could support stronger market conditions over the medium to long term, is also seen as a positive sign for the shipping industry.
মূল প্রতিবেদনে যান ↗