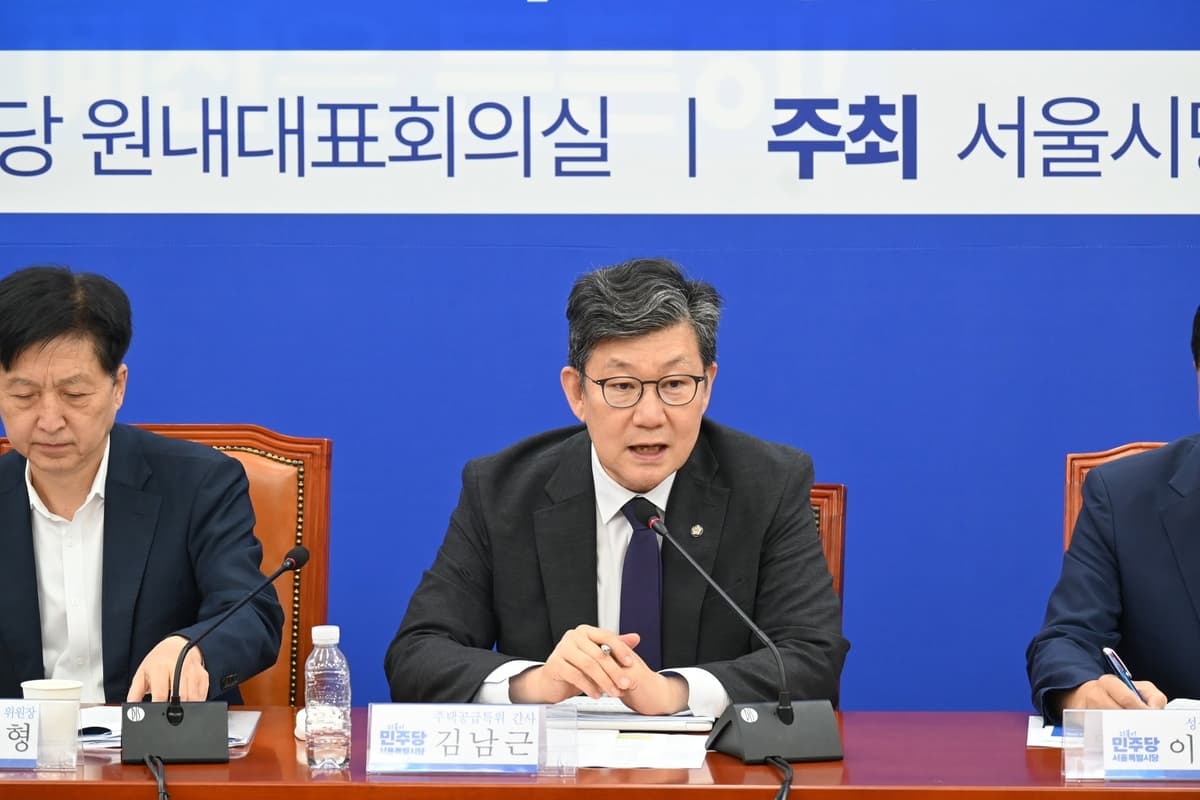
The Democratic Party of Korea is pushing to ease the large shareholding disclosure requirement, known as the 5% rule, that applies when institutional investors such as pension funds and asset managers exercise voting rights jointly. Rep. Kim Nam-keun of the Democratic Party recently introduced a bill to amend the Capital Markets Act so that institutions would have to aggregate and report their stakes only when joint voting "has a material effect on management control." The intent appears to be lifting share prices by making it easier for institutions to combine their holdings and press listed companies on dividend increases, treasury share cancellations and governance improvements. Business groups, however, worry that it will become harder to detect in advance moves by activist funds and others to attack management control.
Under current law, institutions holding less than 5% each must disclose their holdings within five days if they exercise voting rights together, because they are deemed joint holders. The bill, by contrast, would exclude temporary consultations and proxy delegations from the 5% disclosure requirement. It would also exempt demands to appoint up to two independent directors, auditors or audit committee members, as well as demands to change the size of the board. With mandatory cumulative voting and expanded separate election of audit committee members already in force, loosening disclosure of joint voting by institutions as well could leave companies exposed to surprise challenges to management control.
The bigger problem is that legislation strengthening shareholder rights is moving quickly while measures allowing companies to defend management control are nowhere in sight. Under the revised Commercial Act, mandatory cancellation of treasury shares is already in effect, and lawmakers are pursuing a bill — informally dubbed a "bear hug law" in Korea — that would tighten disclosure requirements when a listed company's controlling stake is sold, along with a mandatory tender offer system to protect minority shareholders. Bills on takeover defenses, meanwhile, including poison pills to counter hostile mergers and acquisitions and dual-class shares for ordinary listed companies, have failed to clear the National Assembly.
In the race for dominance in advanced industries such as semiconductors and artificial intelligence, stable management control is an essential condition for supporting investment. If Korean companies burn capital and managerial capacity on control disputes while rivals abroad stake everything on technology development and production capacity, they risk missing the window for investment. The Democratic Party should fundamentally reconsider the legislation easing the 5% rule and move quickly on laws providing takeover defenses. Only when protecting shareholder interests and ensuring stable management control are kept in balance can capital markets develop and companies grow in a sustained way.