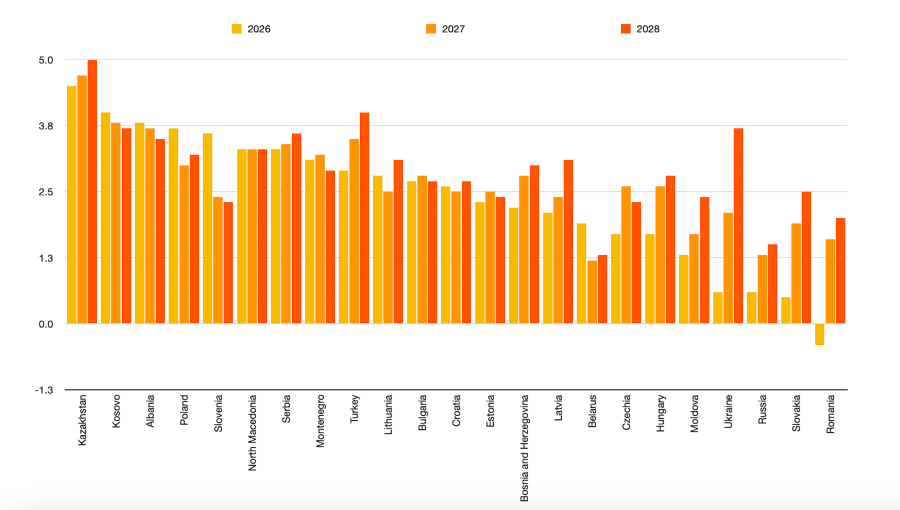
Central, East and Southeast European economies are proving more resilient than expected to energy price shocks and geopolitical turmoil, but rising inflation, higher interest rates and the threat of further disruption to trade are clouding the outlook, the Vienna Institute for International Economic Studies (wiiw) said in its autumn forecast.
The institute expects the region's economies to follow increasingly divergent paths, with Poland, Kazakhstan and the Western Balkans among the strongest performers, while Romania and Slovakia struggle with fiscal pressures and Russia and Ukraine face the mounting economic costs of the war.
“Growth could be higher, but considering everything that's happening, it's decent,” Richard Grieveson, wiiw's deputy director and lead author of the forecast, said at a webinar presenting the report on October 21.
The institute said the region had proved relatively resilient despite an energy price shock triggered by the Iran war and an increasingly dangerous geopolitical environment shaped by US foreign policy, Russia's invasion of Ukraine and China's growing economic influence.
Germany's industrial recovery was providing some support, although the benefits for eastern European economies would probably be more limited than in previous cycles, Grieveson said. At the same time, renewed inflationary pressure was prompting central banks to pause monetary easing or consider raising interest rates, creating a fresh constraint on growth.
wiiw forecasts average growth of 2.2% in the eastern European members of the European Union in 2026, unchanged from its summer outlook, accelerating to 2.5% in 2027, a slight upward revision. The group is expected to grow at more than twice the pace of the euro zone, for which the institute projects expansion of 0.9% this year and 1% next year.
Poland remains the strongest performer among the eastern EU members, with growth forecast at 3.7% in 2026 and 3% in 2027. Hungary is expected to expand by 1.7% this year and 2.6% next year, while Romania is forecast to contract by 0.4% in 2026 as fiscal austerity weighs on activity.
The six Western Balkan economies are projected to grow by an average of 3.2% this year and 3.3% in 2027. Turkey is forecast to expand by 2.9% in 2026 and 3.5% next year, although wiiw cut both forecasts by 0.4 percentage points.
“Economically, the Western Balkans continues to be one of the real bright spots of the region,” Grieveson said, noting that the institute had revised its growth outlook for the group upwards despite significant political challenges.
wiiw identified three broad groups across the region: out-performers including the Western Balkans, Turkey, Poland and Kazakhstan; countries delivering relatively stable growth of around 2-3%, mostly EU members; and weaker performers, including Russia and Belarus, alongside economies facing difficult recoveries, notably Romania and Slovakia.
Around half the region's economies are expected to grow faster this year than their average since the global financial crisis, a performance concentrated particularly in Southeast Europe, Grieveson said.
A changing growth model
EU members are moving away from their traditional role as low-cost manufacturing bases for western European industrial companies towards an economic model based more on higher-value-added production and services, domestic consumption and public investment.
“Countries that invest in technology and productivity – for example, through automation and digitalisation – stand a good chance of continuing to prosper economically. Poland and, to some extent, Czechia are showing the way,” Grieveson said in the report.
Poland's high-tech industry has grown by around 40% over the past decade, illustrating the shift towards more sophisticated production.
Germany's industrial recovery could nevertheless provide less of a boost to the region than in the past. Grieveson said purchasing managers' survey data showed German industry had moved above the 50-point threshold separating expansion from contraction for the first time in a sustained recovery since Russia's full-scale invasion of Ukraine.
However, the rebound was not being led by a revival in the automotive industry, which is closely integrated with central and eastern European manufacturing.
“According to the survey data, it's about defence spending, data centres, but it's stockpiling and risk aversion,” he said, describing the developments as a new type of German industrial model.
The recovery was positive for the region, which relies heavily on German industry, but its benefits should be interpreted cautiously, he added. Investment in eastern Europe's defence industry and inflows of EU funds were also supporting growth.
The EU's tougher approach to China presented both opportunities and risks. Greater protection for European industries could give sectors such as automotive manufacturing some breathing space from Chinese competition, but restrictions could also make Chinese investment and imports of intermediate goods more difficult and expensive.
Inflation returns as geopolitical risks mount
Energy prices have remained elevated since the spring, feeding through into inflation at different speeds across the region. 20 of the 23 countries covered by wiiw had higher inflation in August than previously, Grieveson said.
“The overall trend of inflation is up,” he said, adding that central banks had largely stopped cutting rates and were either holding policy steady or beginning to tighten, with Hungary an exception.
“The disinflation period – great for the economy, great for investment – is over for a while,” he said.
wiiw does not expect the renewed inflationary pressure to trigger a major new tightening cycle, but a pause in monetary easing and the prospect of higher borrowing costs will weigh on activity. Inflation forecasts have been revised down for Turkey and the Western Balkans, where price pressures have been more benign than expected, although Grieveson said the overall upward trend was emerging with a longer lag than anticipated.
The institute has also increased its focus on geopolitics, citing the risk of further Russian attacks on European infrastructure, a more confrontational US foreign policy and the potential for a harder EU-China trade conflict to disrupt supply chains.
Russia's intensified attacks on Ukrainian energy, civilian and export infrastructure could trigger another wave of migration to the EU and further restrict exports of grain and other commodities, with consequences extending beyond Ukraine, Grieveson said.
wiiw cut its Ukrainian growth forecast for 2026 by 0.4 percentage points to 0.6%, and lowered its 2027 projection by the same amount to 2.1%. The latter depends on continued adequate financial and military support from abroad.
Grain exports fell by 70% month on month in August, according to the report, while damage to ports and energy facilities has put additional pressure on industry and public finances. Ukraine faces a funding shortfall of around $33bn for 2027, according to its finance ministry.
Russia's economy is also slowing under the burden of war spending, sanctions and high interest rates. Wiiw forecasts growth of just 0.6% this year, recovering to 1.3% in 2027. Ukrainian drone strikes on Russian oil refineries have contributed to fuel shortages, while the central bank's 14% policy rate is constraining activity.
Political uncertainty threatens EU decision-making
Grieveson warned that an upcoming election cycle across major EU member states, apart from Germany, could complicate policymaking and slow reforms needed to strengthen the bloc's competitiveness.
He said populist parties could challenge the status quo and potentially take power, raising the prospect of a less supportive Polish government towards Ukraine and a French government that would make agreement on EU policy more difficult.
“I’m not expecting the collapse of the EU, but the reforms we need are going to happen more slowly in this environment,” he said. “There's definitely potential for gridlock – EU Council meetings ending without consensus.” He also pointed to the possibility of smaller groups of member states pursuing policies independently, further weakening common positions.