
By: Editorial Posted:
It sounds a bit like a gamble from a player in an industry that is almost pathologically averse to gambling.
Read this article for free:
To continue reading, please subscribe:
*Billed as $5.77 plus GST every four weeks. After 52 weeks, price increases to the regular rate of $19.95 plus GST every four weeks. Offer available to new and qualified returning subscribers only. Cancel any time.
It sounds a bit like a gamble from a player in an industry that is almost pathologically averse to gambling.
Read unlimited articles for free today:
It sounds a bit like a gamble from a player in an industry that is almost pathologically averse to gambling.
Manitoba Public Insurance is currently going through the Public Utilities Board process to set car insurance rates for 2027-28, and it’s asking the PUB to approve a 2.38 rate hike.
As a provincially-run insurance business, MPI is already a bit of an outlier, because, through its government masters, it’s answerable to the Manitoba public in a way that private insurers aren’t.
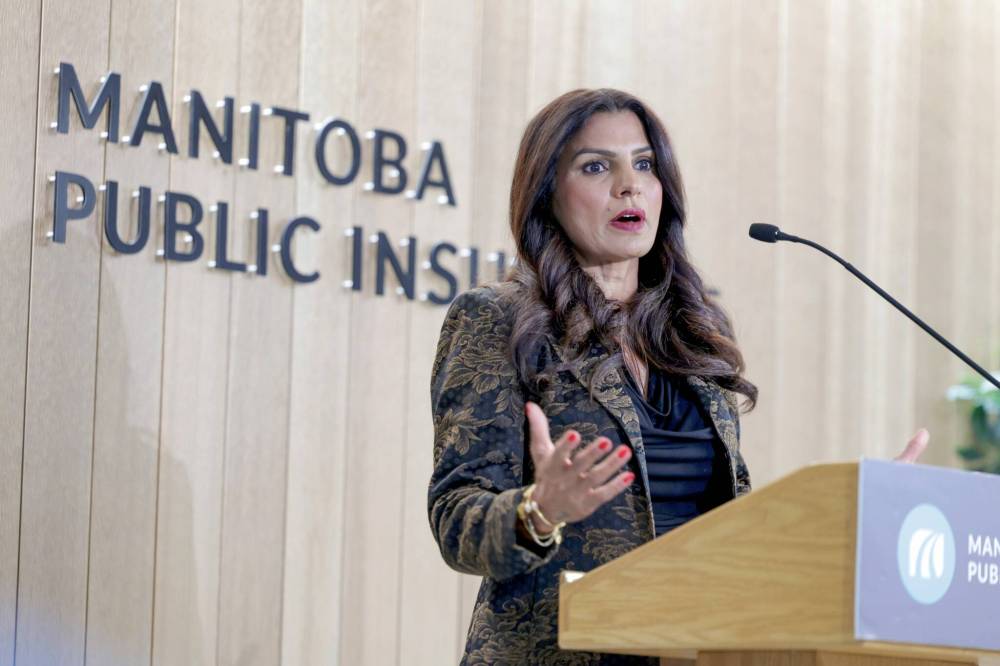
Free Press files
Satvir Jatana is president and CEO of Manitoba Public Insurance, which has asked for a 2.38 per cent rate increase for 2027-28.
Private insurers spend a fortune calculating risk, offsetting that risk with reinsurance to spread it out across the insurance spectrum, and always finding a way to ensure there’s a profit margin built in.
Actuarial accuracy is golden, and the industry leans heavily into research and the mathematics of risk to ensure it does everything it can to accurately predict what’s coming next.
It’s more difficult when that cold, hard analysis of risk is being tempered by public expectations that insurance will remain affordable.
For private insurers, the equation is simple: they calculate what it will cost to cover your risks, and you pay it. Period.
You can squeal. You can cry. You can rage. But, in the end, you pay. It’s not negotiable. You’ll pay, or you’ll absorb the risk yourself.
You need to carry insurance if you want to drive or protect assets like your home and property, and an increase in price doesn’t erase that need.
It’s not optional.
Insurance companies get what they need.
MPI, however, is asking to lose money.
MPI’s chief actuary, Cara Low, told the PUB bluntly that MPI already knows the rate increase it’s asking for won’t cover its costs: “We know it’s wrong. We don’t know how wrong it is for any estimate because we’re forecasting into the future, and no one knows what’s going to happen in the future.”
All insurers are forecasting into the future — but they don’t protect their businesses and customers by deliberately low-balling the revenue they need to cover their costs.
It may be that MPI is hoping the PUB will look cynically at MPI’s rates and order a larger rate increase. That’s what happened in 2025, when the PUB ordered a 5.7 per cent rate increase for vehicle insurance while MPI was requesting only three per cent. MPI’s own analysis said the insurer needed a 6.15 per cent increase just to break even.
The board said the three per cent ask would only serve to push costs down the road to later years.
Maybe MPI feels that the optics will make the PUB look like the bad guy in the story.
Insurance may look like professional gambling from the outside, but the fact is that insurers are the casino in this gambling equation, and public rates are designed to make sure that the house always gets its cut.
Maybe MPI feels the summer storm insurance claims that have been driving up its costs won’t show up again — even though the Canadian insurance industry as a whole is publicly warning that more frequent, more damaging storms are to be expected as part of climate change.
“Over the last decade, insured losses from extreme weather in Canada have averaged $3.7 billion annually,” the Insurance Bureau of Canada said in September, citing 10 major, damaging weather events on the prairies this past summer alone. “Annual losses have increased by approximately 320 per cent since the late 1990s and early 2000s, after accounting for inflation.”
You can, perhaps, pretend that the future is an unknowable blank slate.
But for insurers, that’s not a responsible business model.
It’s burying your head in the sand.
And digging an even bigger financial hole for the future.
- Read Later