Insurers struggle to fully cover losses from accidents at artificial intelligence data centers, or AIDCs, because the damage extends well beyond broken hardware and there is little statistical basis for pricing the rest. Service outages, compensation owed to clients, and the loss of data and trained models all have to be counted, making it difficult for insurers to set the scope and limits of coverage.
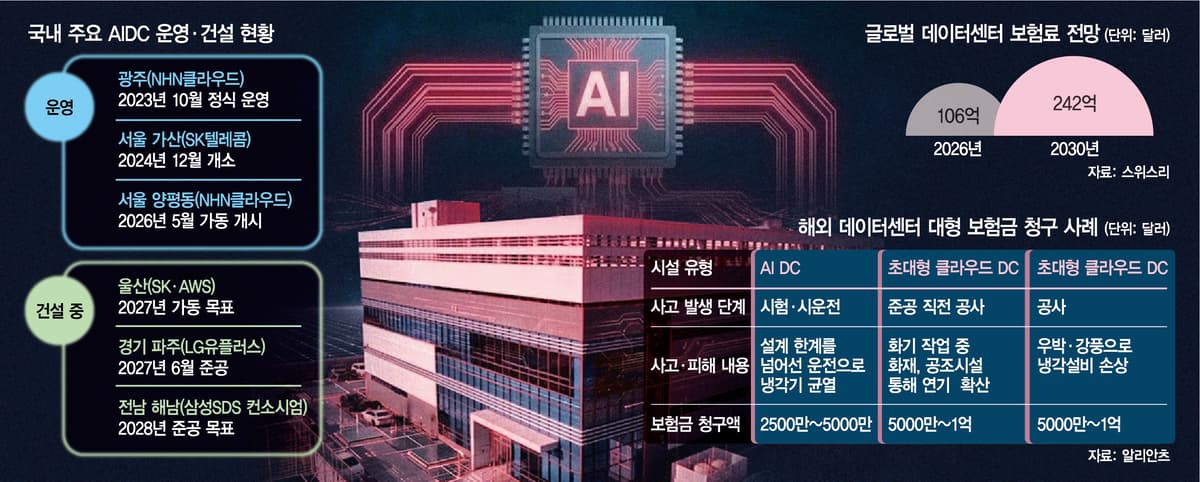
In South Korea, large AIDC projects are under way in Ulsan, Paju and Haenam, concentrating ever larger pools of assets in single facilities. The National AI Computing Center in Haenam will absorb 2.5 trillion won ($1.8 billion) in investment through 2028. As expensive graphics processing units used for AI computation sit packed alongside power and cooling equipment, the potential loss from a single accident keeps growing.
Demand for insurance against such risks is expected to expand as well. Swiss Re, the global reinsurer, projects that global data center insurance premiums, estimated at $10.6 billion this year, will rise to $24.2 billion by 2030.
The difficulty is that conventional property insurance covers physical damage to buildings and equipment such as servers, while the fallout from an AIDC accident may not stop at the cost of repairs. If a cooling system fails and damages GPUs, the services of companies using them can halt, and the longer recovery takes, the heavier the revenue losses and client compensation become. According to a report released in August by global insurer Allianz, one claim of $25 million to $50 million arose from a cracked chiller during the commissioning of an AIDC.
Kim Yeon-hee, a researcher at the Korea Insurance Research Institute, said insurers must assess not only asset values but also the likelihood of an accident, expected losses and recovery periods. "Economic losses from operational interruption need to be evaluated with precision, and coverage should be broadened on that basis," the researcher said.
Add the loss of data and trained models, and calculating the scale of damage becomes more complex still. Replacement costs can be estimated for equipment, but the value of data and models varies with how they are used and how much revenue they generate, making uniform valuation difficult. Even when cyber insurance covers data restoration costs or liability for client compensation, it does not necessarily compensate for the value of the data and models themselves.
Similar debates over whether existing policies adequately cover such losses are under way abroad. In an analysis of AIDC insurance published in August last year, the U.S. law firm Morgan Lewis noted that property policies frequently exclude the loss of electronic data. It pointed out in particular that business interruption coverage also often presumes physical damage to buildings and equipment, meaning losses stemming from the interruption of telecommunications or power supply services may fall outside coverage.
Compounding the problem is the difficulty of predicting how large such compound losses will be. Even when an insurer seeks to share losses too big to absorb alone with a reinsurer, that uncertainty remains. It can translate into high premium rates or restrictive coverage terms, while cutting coverage to lower costs leaves a larger share of losses unrecoverable when an accident occurs.
Even where losses can be estimated, securing coverage limits to match their scale has limits of its own. The Texas data center project by Meta and BlackRock, whose insurance terms were disclosed in August, carries total project costs of $14 billion. The maximum payout for damage to buildings and equipment in the early operating phase was set at $450 million. Coverage sufficient to make up the full property loss in a worst-case accident destroying the entire facility was not secured, because of the cost. Losses beyond the coverage limit remain a risk not only for the operator but also for the lenders financing the project.
Developing products to narrow that gap also requires loss assessment to come first, observers say. Major South Korean non-life insurers are reviewing products to cover the additional risks of AIDCs, but are having trouble putting together specific product structures and coverage terms.
Some argue the government should help insurers share accident and loss data now scattered across individual companies, and support the development of models to calculate expected losses, expanding the basis for setting premiums and coverage terms. Others say authorities should step in as a reinsurer to assume part of the risk, or provide subsidies. Jung Kwang-min, a professor of industrial and management engineering at POSTECH, said data centers are infrastructure for core industries, and a problem at one site can paralyze multiple services at once. "The government needs to build a market so that the private insurance sector can thrive, and taking on the role of reinsurer directly is one option worth considering," the professor said.